

Company Coverage
Thaifoods Group (TFG TB): 3Q26 Earnings To Grow yoy And qoq
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt9.55
Bt13.00
36.13%
Bt12.40
Analyst
Highlights
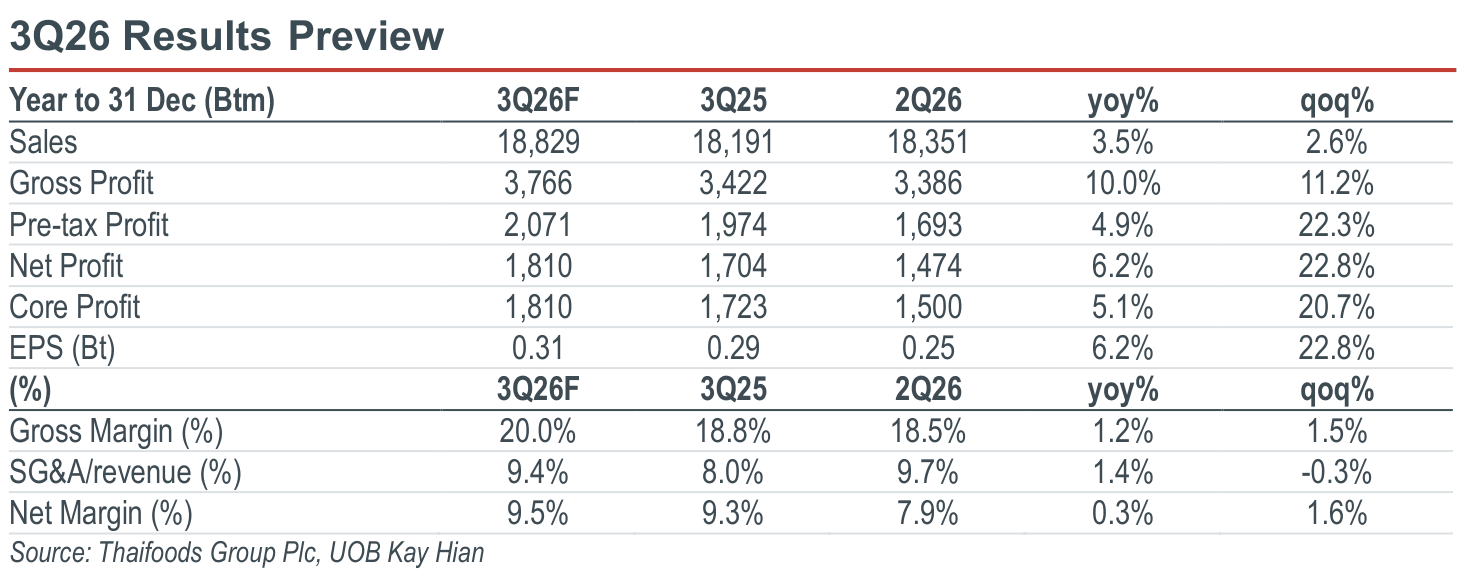
- We expect TFG to report a 3Q26 core profit of Bt1,810m (+5.1% yoy, +20.7% qoq).
- TFG is well positioned to benefit from an earnings recovery theme on higher domestic livestock prices in 3Q26 thanks to high exposure to the Thai market.
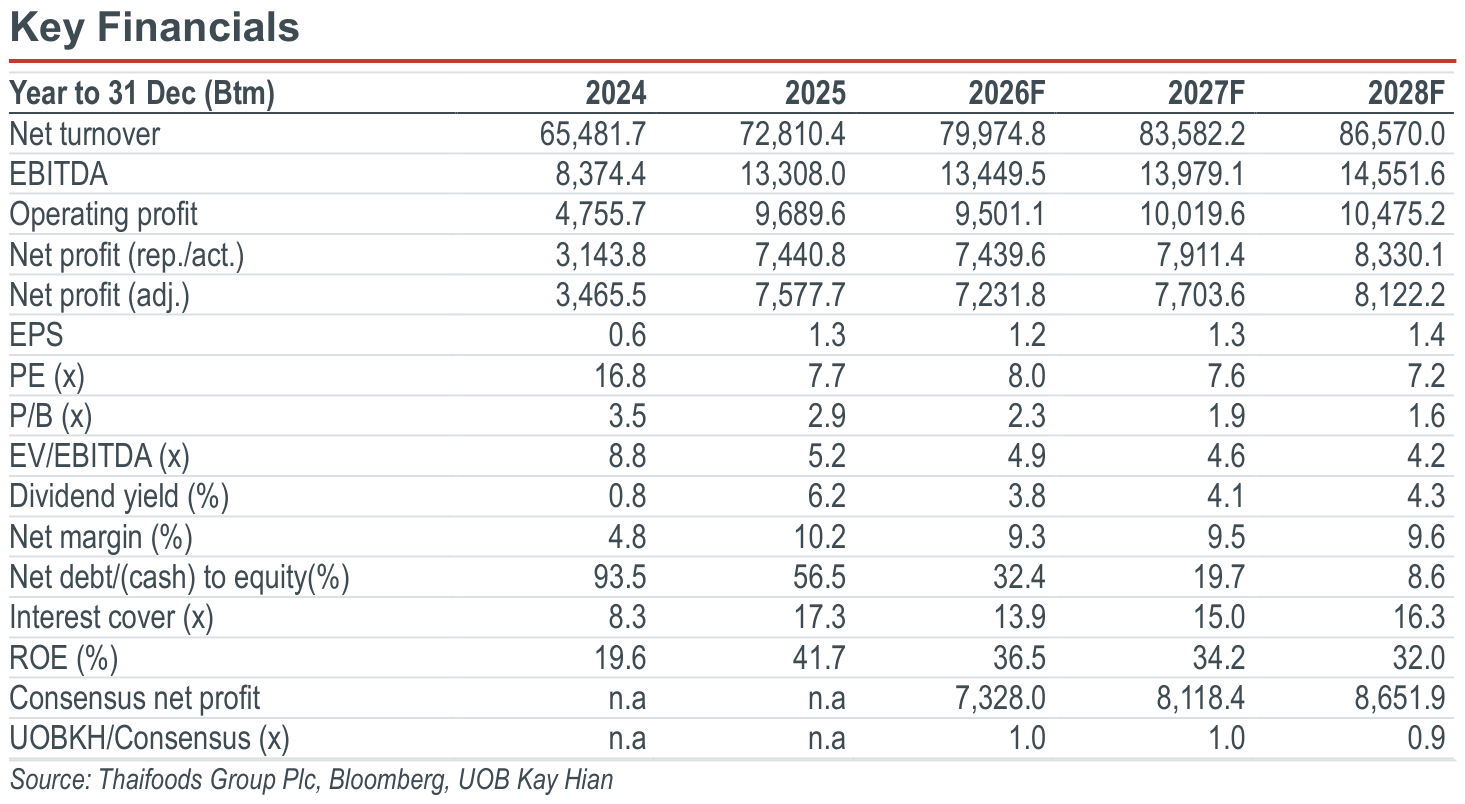
- We reaffirm our positive view on TFG for both the short and long term on the back of the ongoing livestock price upcycle and continued retail revenue growth.
- Maintain BUY with a higher target price of Bt13.00.
Analysis
- 3Q26 earnings to grow yoy and qoq. We expect Thaifoods Group (TFG) to report a 3Q26 core profit of Bt1,810m (+5.1% yoy, +20.7% qoq). The key drivers are expected to be revenue growth and resilient margins thanks to higher domestic livestock prices in 3Q26 yoy and qoq.
- Top-line continues to grow yoy and qoq. We expect TFG’s 3Q26 revenue to reach Bt18.8b (+3.5% yoy, +2.6% qoq), attributable to: a) poultry revenue growth due to higher chicken ASPs with volume in Thailand and increased export volumes yoy and qoq; and b) retail revenue growth, attributable to continued store expansion and SSSG of around +3% in 3Q26. Retail revenue could indirectly benefit from the Thai Chuay Thai co-payment scheme, which is expected to boost sales in the food service segment. TFG had 790 retail stores in 3Q26, up from 533 in 3Q25 and 748 in 2Q26. However, we expect swine revenue to decline slightly both yoy and qoq due to lower ASPs, particularly in the Vietnam market, and lower external sales volume as a greater proportion of livestock is sold through the company’s retail stores.
Highlights
- We expect TFG to report a 3Q26 core profit of Bt1,810m (+5.1% yoy, +20.7% qoq).
- TFG is well positioned to benefit from an earnings recovery theme on higher domestic livestock prices in 3Q26 thanks to high exposure to the Thai market.
- We reaffirm our positive view on TFG for both the short and long term on the back of the ongoing livestock price upcycle and continued retail revenue growth.
- Maintain BUY with a higher target price of Bt13.00.
Analysis
- 3Q26 earnings to grow yoy and qoq. We expect Thaifoods Group (TFG) to report a 3Q26 core profit of Bt1,810m (+5.1% yoy, +20.7% qoq). The key drivers are expected to be revenue growth and resilient margins thanks to higher domestic livestock prices in 3Q26 yoy and qoq.
- Top-line continues to grow yoy and qoq. We expect TFG’s 3Q26 revenue to reach Bt18.8b (+3.5% yoy, +2.6% qoq), attributable to: a) poultry revenue growth due to higher chicken ASPs with volume in Thailand and increased export volumes yoy and qoq; and b) retail revenue growth, attributable to continued store expansion and SSSG of around +3% in 3Q26. Retail revenue could indirectly benefit from the Thai Chuay Thai co-payment scheme, which is expected to boost sales in the food service segment. TFG had 790 retail stores in 3Q26, up from 533 in 3Q25 and 748 in 2Q26. However, we expect swine revenue to decline slightly both yoy and qoq due to lower ASPs, particularly in the Vietnam market, and lower external sales volume as a greater proportion of livestock is sold through the company’s retail stores.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt9.55
Bt13.00
36.13%
Bt12.40
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

22 Oct 2026
Betagro (BTG TB): 3Q26 Results Preview: Thai Livestock Producers Are Winners

20 Oct 2026
Charoen Pokphand Foods (CPF TB): 3Q26 Results Preview: Sluggish Short-term Outlook, Livestock Price Upcycle Continues

19 Oct 2026
COM7 (COM7 TB): Earnings Expected To Surge In 3Q26
Our latest research

28 Oct 2026
Amata Corporation (AMATA TB): 3Q26 Results Preview: Softer Earnings With Potential Land Sales Improvement In 4Q26

28 Oct 2026
Bangkok Chain Hospital (BCH TB): Expect Decent Earnings Growth In 3Q26

28 Oct 2026