

Company Coverage
SCG Packaging (SCGP TB): Focus On Selling Price Increases To Mitigate Cost Pressures
BUY (Maintained)
Current price:
Target price:
Upside:
Bt29.25
Bt43.00
+47.01%
Analyst
Highlights
- Demand is expected to recover following the floods in Thailand and inventory build-up ahead of the New Year festive season in Thailand, Vietnam and Indonesia. Continued selling price increases should help mitigate the impact of higher production costs.
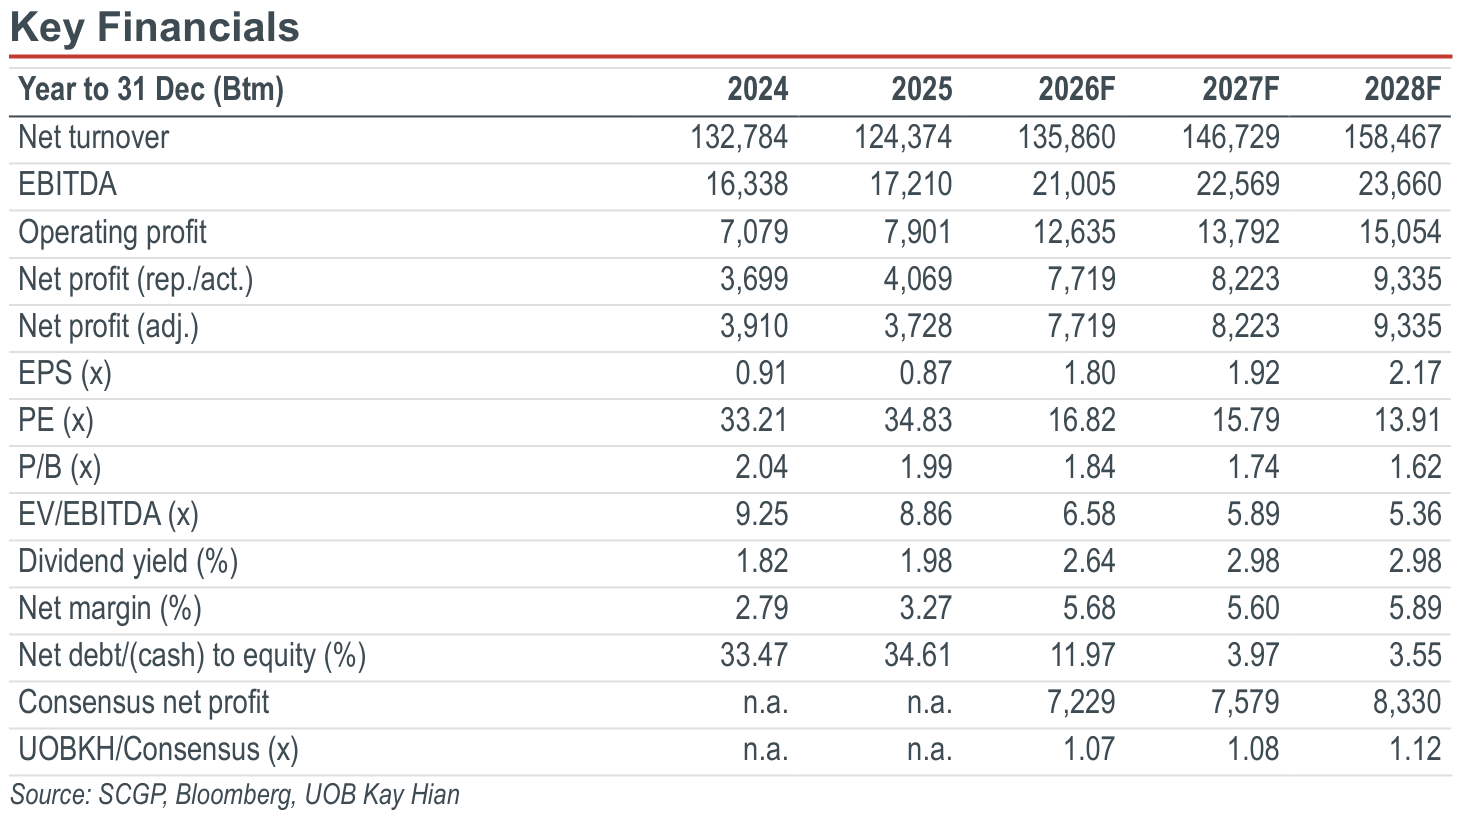
- SCGP reported a net profit of Bt2.03b, down 12% qoq but up 113% yoy, in line with both our and consensus estimates.
- Fajar continues to deliver strong earnings, supporting our unchanged 2026 forecast for SCGP to return to profitability for the first time in four years.
- Maintain BUY. Target price: Bt43.00.
Analysis
- The tone at the meeting with SCG Packaging (SCGP) was positive.
- Demand recovery to support earnings, while higher costs remain a key risk. We expect SCGP’s 4Q26 earnings to benefit from recovering demand following the floods in Thailand, year-end consumption, and inventory restocking ahead of the New Year festive season. Demand should also be supported by preparations for Tet in Vietnam and Hari Raya in Indonesia, with these seasonal tailwinds extending into 1Q27. However, higher raw material costs, particularly recycled containerboard (RCP), and rising energy costs since 2Q26 are expected to limit earnings upside. We forecast 4Q26 net profit of Bt1.8b, down qoq but significantly higher yoy from Bt1.21b in 4Q25, supported by continued selling price increases throughout 2026 and greater use of locally sourced RCP and biomass to reduce production costs.
- Fajar to sustain profitability. We expect Fajar to remain profitable in 4Q26, supported by year-end festivities that stimulate demand for F&B packaging. Fajar will continue to focus on the domestic Indonesian market while exploring new regional markets with strong demand, particularly India and other South Asian markets. Cost-saving initiatives include sourcing RCP locally and improving energy management. Fajar is also studying upgrades to its duplex paper production machinery and pursuing mergers and partnerships with packaging box manufacturers to increase the integrated-chain contribution from Fajar and MYPAK to above 26%. These initiatives should strengthen competitiveness and support sustained margin expansion. Fajar recorded 9M26 net profit of Bt435m, reversing a net loss of Bt1.48b in 9M25. We therefore maintain our 2026 net profit forecast of Bt685m, vs a net loss of Bt2.26b in 2025, marking Fajar’s return to profitability for the first time in four years.
Highlights
- Demand is expected to recover following the floods in Thailand and inventory build-up ahead of the New Year festive season in Thailand, Vietnam and Indonesia. Continued selling price increases should help mitigate the impact of higher production costs.
- SCGP reported a net profit of Bt2.03b, down 12% qoq but up 113% yoy, in line with both our and consensus estimates.
- Fajar continues to deliver strong earnings, supporting our unchanged 2026 forecast for SCGP to return to profitability for the first time in four years.
- Maintain BUY. Target price: Bt43.00.
Analysis
- The tone at the meeting with SCG Packaging (SCGP) was positive.
- Demand recovery to support earnings, while higher costs remain a key risk. We expect SCGP’s 4Q26 earnings to benefit from recovering demand following the floods in Thailand, year-end consumption, and inventory restocking ahead of the New Year festive season. Demand should also be supported by preparations for Tet in Vietnam and Hari Raya in Indonesia, with these seasonal tailwinds extending into 1Q27. However, higher raw material costs, particularly recycled containerboard (RCP), and rising energy costs since 2Q26 are expected to limit earnings upside. We forecast 4Q26 net profit of Bt1.8b, down qoq but significantly higher yoy from Bt1.21b in 4Q25, supported by continued selling price increases throughout 2026 and greater use of locally sourced RCP and biomass to reduce production costs.
- Fajar to sustain profitability. We expect Fajar to remain profitable in 4Q26, supported by year-end festivities that stimulate demand for F&B packaging. Fajar will continue to focus on the domestic Indonesian market while exploring new regional markets with strong demand, particularly India and other South Asian markets. Cost-saving initiatives include sourcing RCP locally and improving energy management. Fajar is also studying upgrades to its duplex paper production machinery and pursuing mergers and partnerships with packaging box manufacturers to increase the integrated-chain contribution from Fajar and MYPAK to above 26%. These initiatives should strengthen competitiveness and support sustained margin expansion. Fajar recorded 9M26 net profit of Bt435m, reversing a net loss of Bt1.48b in 9M25. We therefore maintain our 2026 net profit forecast of Bt685m, vs a net loss of Bt2.26b in 2025, marking Fajar’s return to profitability for the first time in four years.
BUY (Maintained)
Current price:
Target price:
Upside:
Bt29.25
Bt43.00
+47.01%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

12 Oct 2026
SCG Packaging (SCGP TB): 3Q26 Earnings Remain Strong Despite Higher RCP Costs

27 Oct 2026
Praram 9 Hospital (PR9 TB): Expect A Record High Net Profit In 3Q26

22 Oct 2026
Krung Thai Bank (KTB TB): 3Q26: Results In Line; Credit Costs Decline QOQ
Our latest research

28 Oct 2026
Amata Corporation (AMATA TB): 3Q26 Results Preview: Softer Earnings With Potential Land Sales Improvement In 4Q26

28 Oct 2026
Bangkok Chain Hospital (BCH TB): Expect Decent Earnings Growth In 3Q26

28 Oct 2026