

Company Coverage
Bangkok Chain Hospital (BCH TB): Expect Decent Earnings Growth In 3Q26
BUY (Maintained)
Current price:
Target price:
Upside:
Bt10.80
Bt13.00
+20.4%
Analyst
Analyst
Nonpawit Vathanadachakul
Highlights
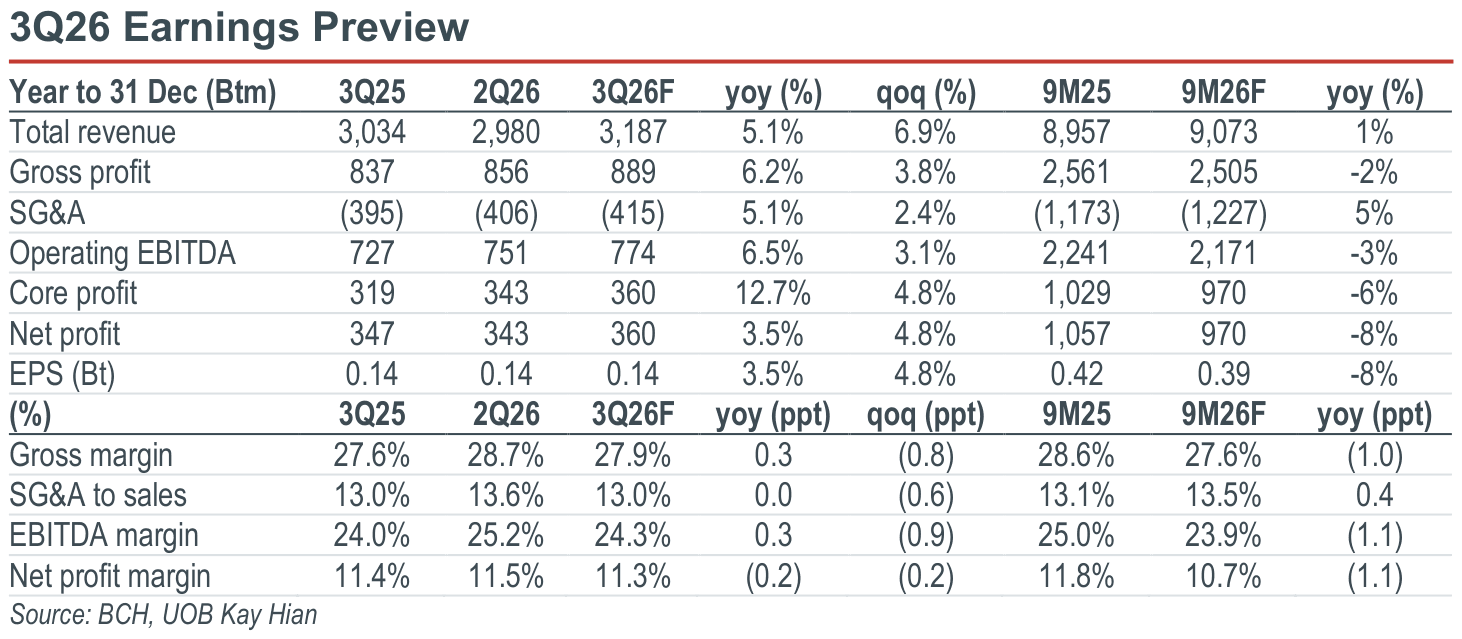
- BCH is expected to report a decent net profit of Bt360m in 3Q26 (+3.5% yoy, +4.8% qoq), driven by an increase in Thai inpatients and new Middle East referrals.
- The SSO rate increase is lower than management guidance but still in line with our assumption.
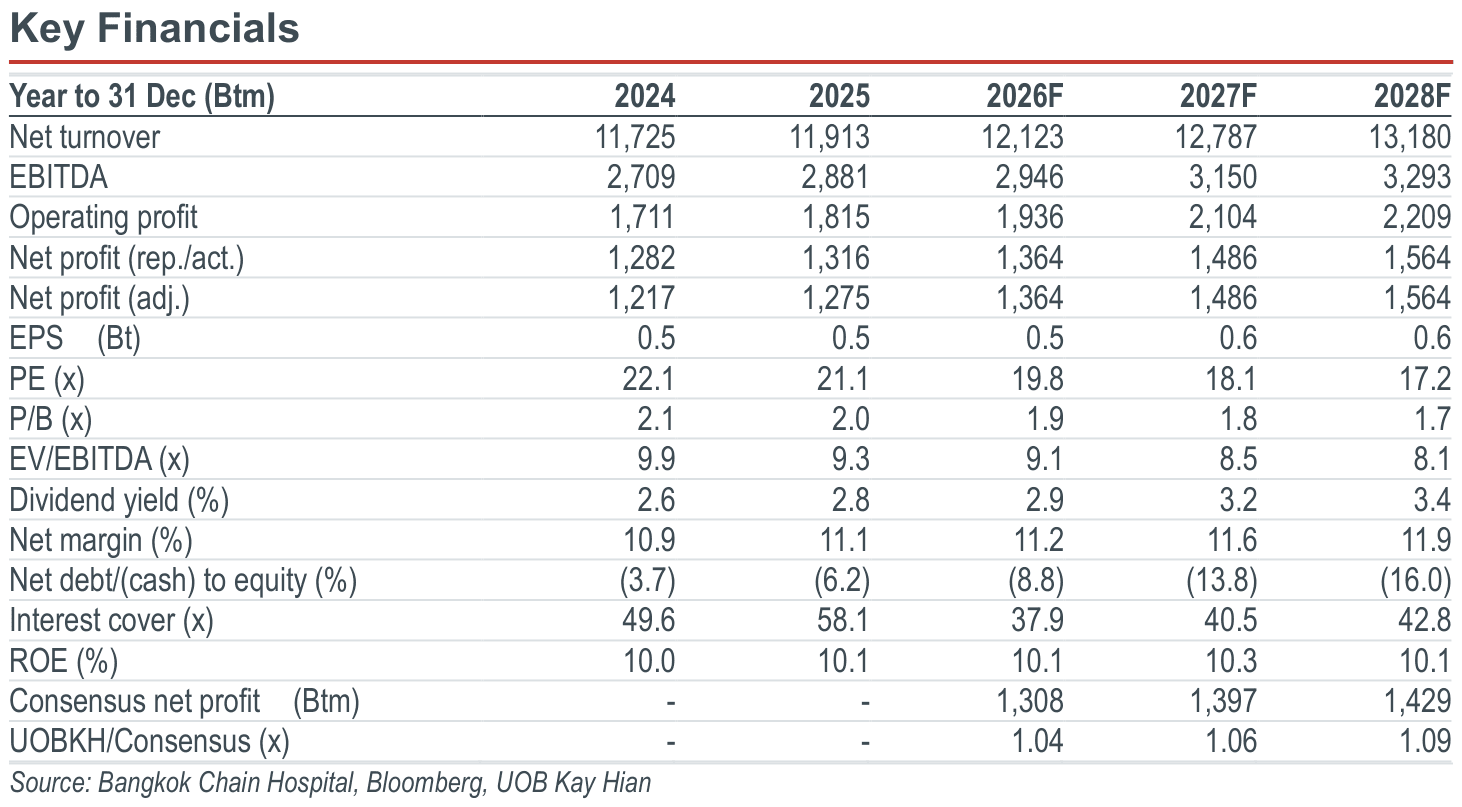
- The impact of the flooding is likely to be minimal and we could see KIH Ubon swiftly improve its performance. We remain positive on BCH’s outlook in 4Q26 due to the low base last year. Maintain BUY with a target price of Bt13.00.
Analysis
- Expect decent net profit growth in 3Q26. Bangkok Chain Hospital (BCH) is forecast to report a net profit of Bt360m in 3Q26 (+3.5% yoy, +4.8% qoq). The earnings growth yoy could be driven by an increase in Thai inpatients and new Middle Eastern patient referrals. Top-line should be at Bt3.19b (+5.1% yoy, +6.9% qoq), with the strong contributor being Thai patient revenue growth from seasonal outbreaks. Middle Eastern patient revenue is expected to continue to grow yoy and qoq due to new referrals from Qatar and UAE. Foreign patient revenue continues to show growth with main contributors such as Saudi Arabia, Laos, Myanmar and Libya. Myanmar patient revenue once again has shown growth yoy after the renovation at Kasemrad Hospital Maesai, which was completed in Aug 26. We project that gross and EBITDA margins for BCH will expand yoy due to an increase in foreign patient volumes.
Highlights
- BCH is expected to report a decent net profit of Bt360m in 3Q26 (+3.5% yoy, +4.8% qoq), driven by an increase in Thai inpatients and new Middle East referrals.
- The SSO rate increase is lower than management guidance but still in line with our assumption.
- The impact of the flooding is likely to be minimal and we could see KIH Ubon swiftly improve its performance. We remain positive on BCH’s outlook in 4Q26 due to the low base last year. Maintain BUY with a target price of Bt13.00.
Analysis
- Expect decent net profit growth in 3Q26. Bangkok Chain Hospital (BCH) is forecast to report a net profit of Bt360m in 3Q26 (+3.5% yoy, +4.8% qoq). The earnings growth yoy could be driven by an increase in Thai inpatients and new Middle Eastern patient referrals. Top-line should be at Bt3.19b (+5.1% yoy, +6.9% qoq), with the strong contributor being Thai patient revenue growth from seasonal outbreaks. Middle Eastern patient revenue is expected to continue to grow yoy and qoq due to new referrals from Qatar and UAE. Foreign patient revenue continues to show growth with main contributors such as Saudi Arabia, Laos, Myanmar and Libya. Myanmar patient revenue once again has shown growth yoy after the renovation at Kasemrad Hospital Maesai, which was completed in Aug 26. We project that gross and EBITDA margins for BCH will expand yoy due to an increase in foreign patient volumes.
BUY (Maintained)
Current price:
Target price:
Upside:
Bt10.80
Bt13.00
+20.4%
Analyst
Analyst
Nonpawit Vathanadachakul
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

19 Oct 2026
Bangkok Dusit Medical Services (BDMS TB): Expect Strong 3Q26 Earnings, Supported By Thai Patients

27 Oct 2026
Praram 9 Hospital (PR9 TB): Expect A Record High Net Profit In 3Q26

28 Oct 2026
Thaifoods Group (TFG TB): 3Q26 Earnings To Grow yoy And qoq
Our latest research

28 Oct 2026
Amata Corporation (AMATA TB): 3Q26 Results Preview: Softer Earnings With Potential Land Sales Improvement In 4Q26

28 Oct 2026
SCG Packaging (SCGP TB): Focus On Selling Price Increases To Mitigate Cost Pressures
28 Oct 2026