

Company Coverage
Amata Corporation (AMATA TB): 3Q26 Results Preview: Softer Earnings With Potential Land Sales Improvement In 4Q26
BUY (Maintained)
Current price:
Target price:
Upside:
Bt28.75
Bt38.00
32.17%
Analyst
Analyst
Panjarat Thaweesriprasert
Highlights
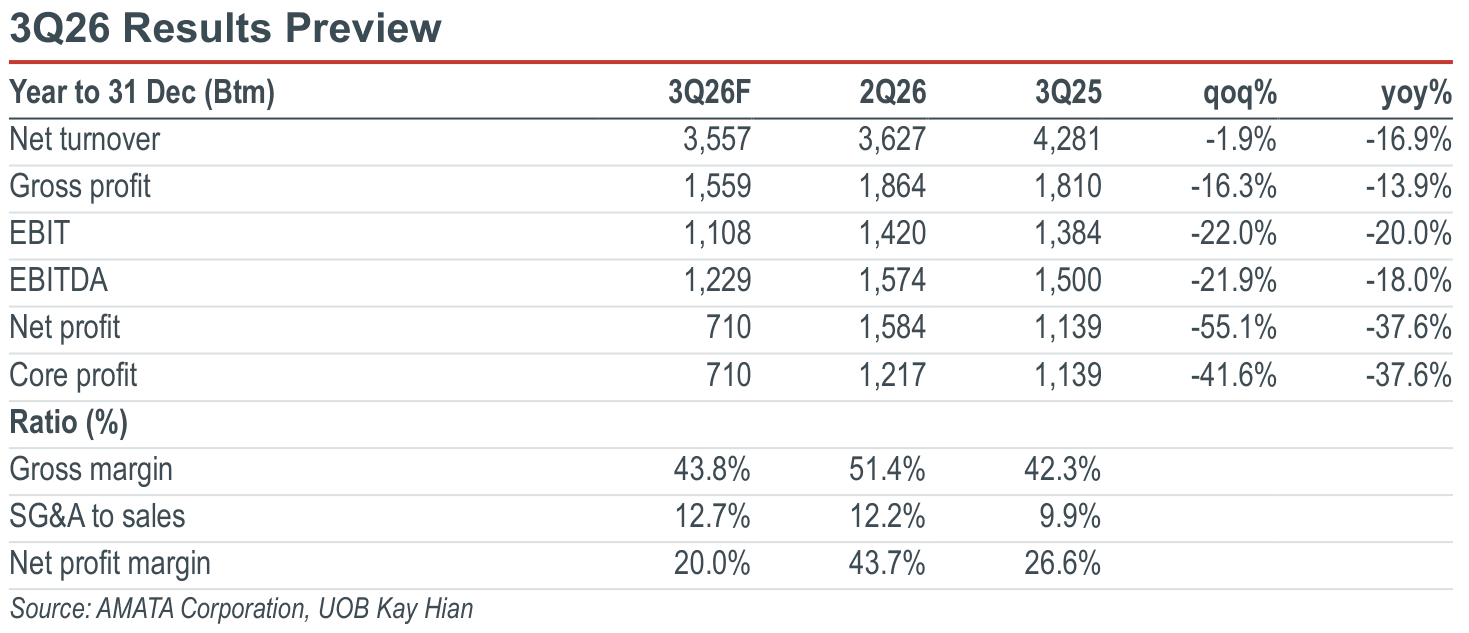
- We expect AMATA to report 3Q26 earnings of Bt710m (-38% yoy, -55% qoq).
- 9M26 land sales in Thailand and Vietnam reached 28% of target, with an 800-rai high-potential pipeline in Thailand.
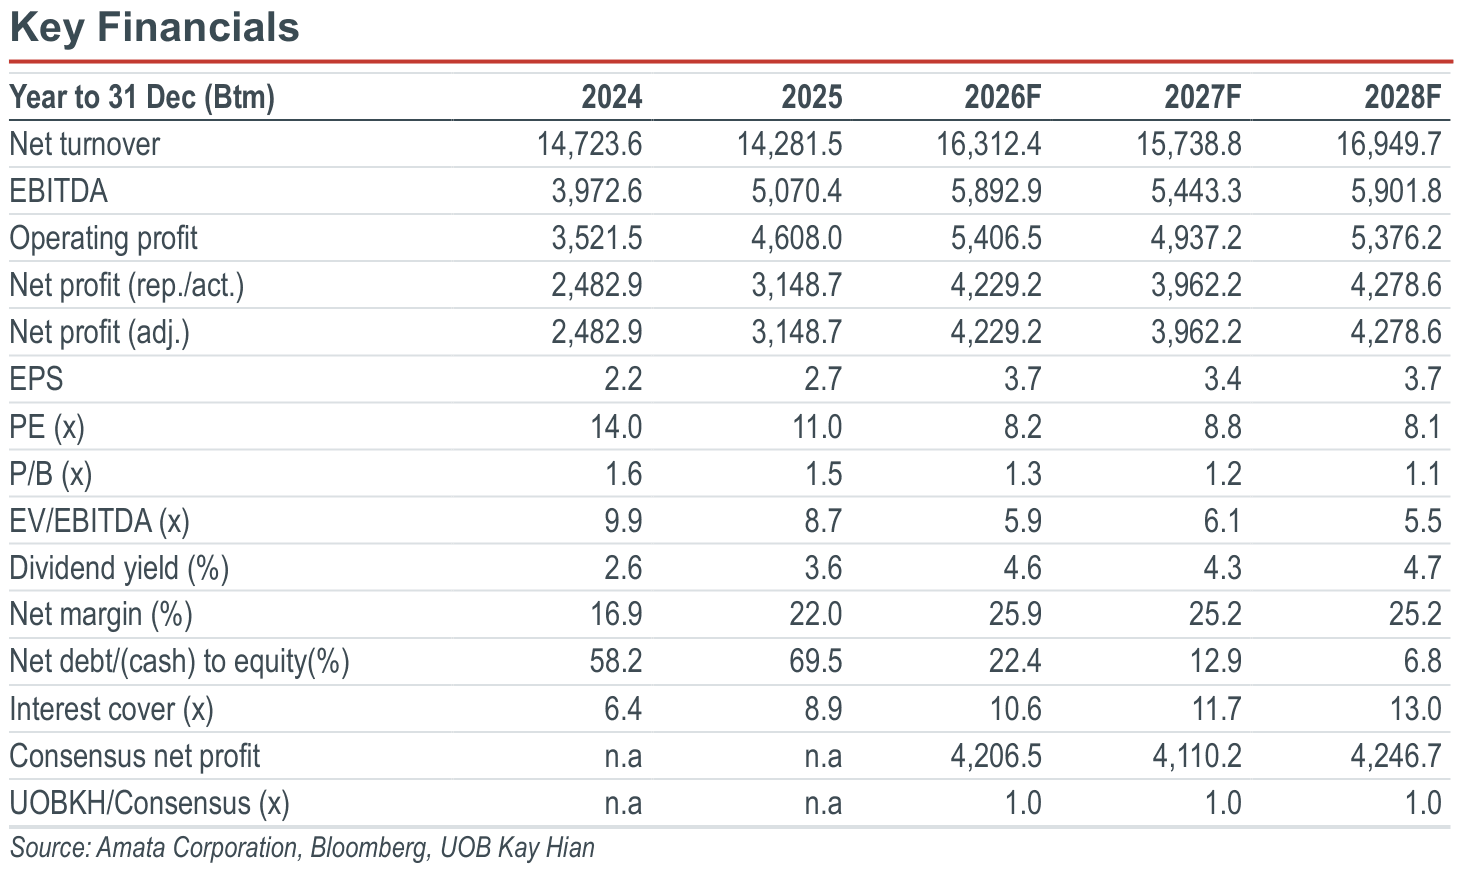
- Maintain BUY with an unchanged target price of Bt38.00.
Analysis
- 3Q26 earnings to drop yoy and qoq. We expect AMATA Corporation (AMATA) to report 3Q26 earnings of Bt710m, down 38% yoy and 55% qoq. The yoy decline is attributable to a high base of land transfers in 3Q25 at 664 rai compared with 258 rai in 3Q26. The qoq drop could be driven by lower land transfers and a reduced contribution from Amata Smart City.
- Gross margin to decline qoq. We foresee gross margin coming in at 43.8%, declining qoq due to lower land transfers from AMATA Smart City. We expect gross margin from the industrial estate business to be around 55% in 3Q26, dragged down by a higher contribution from other industrial estate sites with lower gross margins.
Highlights
- We expect AMATA to report 3Q26 earnings of Bt710m (-38% yoy, -55% qoq).
- 9M26 land sales in Thailand and Vietnam reached 28% of target, with an 800-rai high-potential pipeline in Thailand.
- Maintain BUY with an unchanged target price of Bt38.00.
Analysis
- 3Q26 earnings to drop yoy and qoq. We expect AMATA Corporation (AMATA) to report 3Q26 earnings of Bt710m, down 38% yoy and 55% qoq. The yoy decline is attributable to a high base of land transfers in 3Q25 at 664 rai compared with 258 rai in 3Q26. The qoq drop could be driven by lower land transfers and a reduced contribution from Amata Smart City.
- Gross margin to decline qoq. We foresee gross margin coming in at 43.8%, declining qoq due to lower land transfers from AMATA Smart City. We expect gross margin from the industrial estate business to be around 55% in 3Q26, dragged down by a higher contribution from other industrial estate sites with lower gross margins.
BUY (Maintained)
Current price:
Target price:
Upside:
Bt28.75
Bt38.00
32.17%
Analyst
Analyst
Panjarat Thaweesriprasert
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

25 Sept 2026
i-Tail Corporation (ITC TB): 3Q26 Results Preview: Sustained Strong Sales Growth Momentum

28 Sept 2026
Delta (Thailand) (DELTA TB) : 3Q26 Results Preview: Earnings Expected To Improve qoq, Driven By Higher Sales And Margins

21 Oct 2026
Osotspa (OSP TB): 3Q26 Results Preview: Margins Expected To Remain Resilient
Our latest research

28 Oct 2026
Bangkok Chain Hospital (BCH TB): Expect Decent Earnings Growth In 3Q26

28 Oct 2026
SCG Packaging (SCGP TB): Focus On Selling Price Increases To Mitigate Cost Pressures

28 Oct 2026