Company Coverage
Charoen Pokphand Foods (CPF TB): 3Q26 Results Preview: Sluggish Short-term Outlook, Livestock Price Upcycle Continues
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt21.10
Bt25.00
18.48%
Bt26.00
Analyst
Highlights
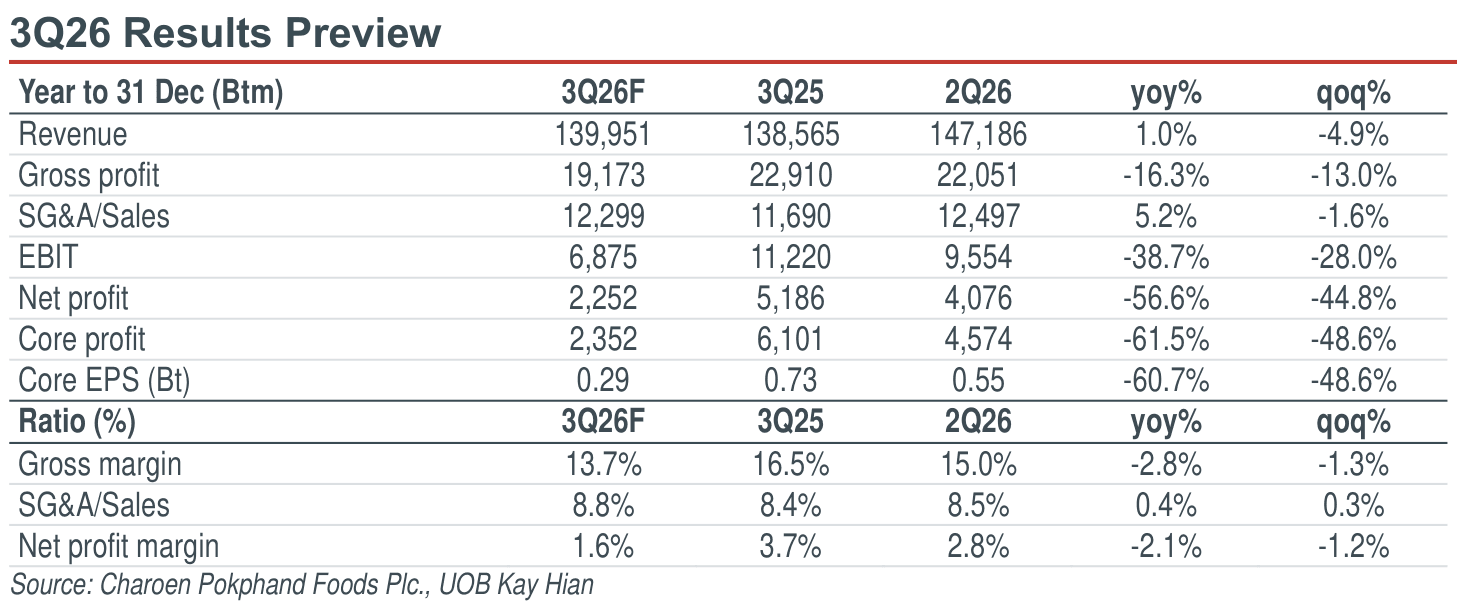
- CPF is expected to report 3Q26 core earnings of Bt2,352m, (-62% yoy and -49% qoq), pressured by lower profitability amid sluggish international livestock prices and a lower share of profit.
- Looking ahead, we see the short-term decline in livestock prices as an attractive accumulation opportunity. We reiterate our expectation of an earnings recovery theme from 4Q26 through to 1H27, on the back of the livestock price upcycle in key markets.
- Maintain BUY. Target price: Bt25.00.
Analysis
- 3Q26 earnings to be weaker than previous expectation. Charoen Pokphand Foods (CPF) is expected to report a net profit of Bt2,252m for 3Q26 (-57% yoy and -45% qoq). Excluding one-off items, 3Q26 core earnings are projected at Bt2,352m, (-62% yoy and -49% qoq)
- Lower profitability in 3Q26 due to decreasing international livestock prices. We expect gross profit margin to decline yoy and qoq to 13.7% in 3Q26, down from 16.5% in 3Q25 and 15.0% in 2Q26. This decrease should be driven by lower international livestock prices qoq in Vietnam and other markets due to seasonally lower demand. In 3Q36, Vietnam swine prices decrease to VND59,624/kg (-9% qoq, flat yoy).
Highlights
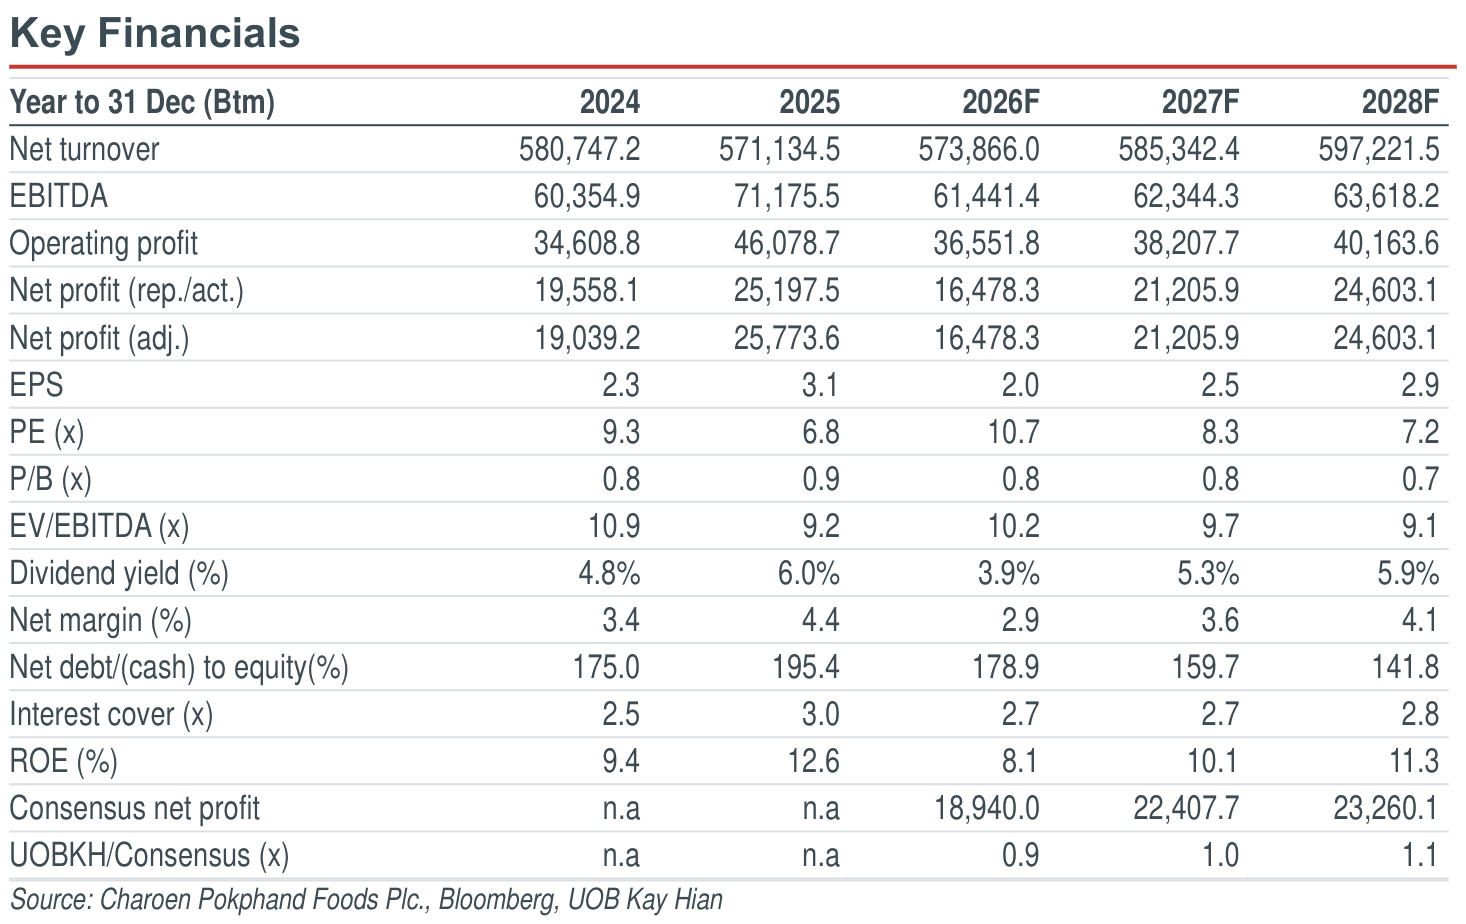
- CPF is expected to report 3Q26 core earnings of Bt2,352m, (-62% yoy and -49% qoq), pressured by lower profitability amid sluggish international livestock prices and a lower share of profit.
- Looking ahead, we see the short-term decline in livestock prices as an attractive accumulation opportunity. We reiterate our expectation of an earnings recovery theme from 4Q26 through to 1H27, on the back of the livestock price upcycle in key markets.
- Maintain BUY. Target price: Bt25.00.
Analysis
- 3Q26 earnings to be weaker than previous expectation. Charoen Pokphand Foods (CPF) is expected to report a net profit of Bt2,252m for 3Q26 (-57% yoy and -45% qoq). Excluding one-off items, 3Q26 core earnings are projected at Bt2,352m, (-62% yoy and -49% qoq)
- Lower profitability in 3Q26 due to decreasing international livestock prices. We expect gross profit margin to decline yoy and qoq to 13.7% in 3Q26, down from 16.5% in 3Q25 and 15.0% in 2Q26. This decrease should be driven by lower international livestock prices qoq in Vietnam and other markets due to seasonally lower demand. In 3Q36, Vietnam swine prices decrease to VND59,624/kg (-9% qoq, flat yoy).
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt21.10
Bt25.00
18.48%
Bt26.00
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

2 Oct 2026
Advance Info Services (ADVANC TB): Operations Remain Stable, But Costs Expected To Increase Following Resumption Of Investment Plan

25 Sept 2026
i-Tail Corporation (ITC TB): 3Q26 Results Preview: Sustained Strong Sales Growth Momentum

7 Oct 2026
CP ALL (CPALL TB): 3Q26 Earnings Dragged By CP Axtra; Recovery Expected Ahead
Our latest research

20 Oct 2026
Kiatnakin Phatra Bank (KKP TB): 3Q26: Results Beat; A Positive Surprise From Non-II

19 Oct 2026
Bangkok Dusit Medical Services (BDMS TB): Expect Strong 3Q26 Earnings, Supported By Thai Patients

19 Oct 2026