

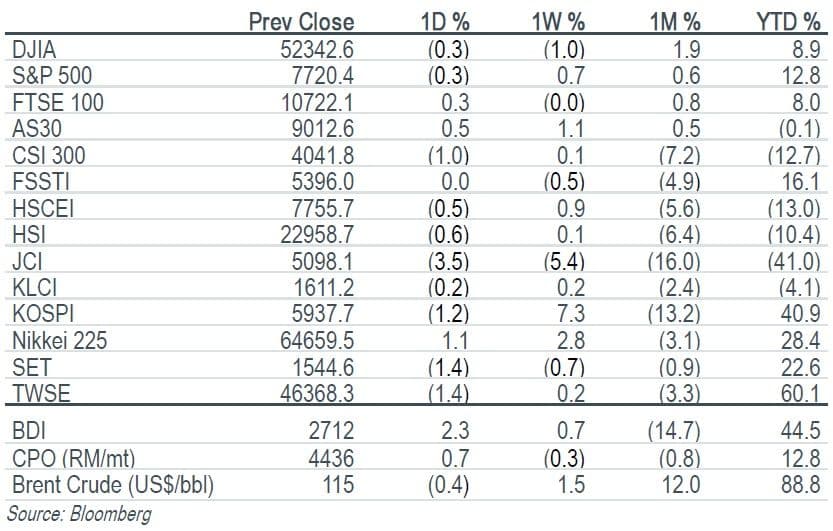
Key Indices
Top Stories
Sector Update | Oil and Gas
- While we remain cautious on the petrochemical sector and maintain an UNDERWEIGHT rating due to Chinese oversupply, we view the new JVCo as a win-win for PTTGC and SCGC. PTTGC stands to benefit more from significant asset expansion with limited financial burden, reasonable acquisition valuation, and stronger valuechain integration to accelerate its transition towards specialty chemicals. We maintain MARKET WEIGHT on the oil and gas sector, with TOP and SCGP as our top picks.
Company Update | Central Plaza Hotel (CENTEL TB/BUY/Bt46.50/Target: Bt58.00)
- CENTEL should report 3Q26 net profit of Bt220m (+37.1% yoy, +32.1% qoq), driven by strong hotel performance in the Maldives and upcountry destinations, alongside improving food margins. Refinancing and new bond issuance should generate further interest savings from 4Q26. Strong forward bookings support positive 4Q26 RevPar growth across key markets. Food performance remains resilient despite headwinds, with seasonal demand expected to strengthen. Maintain BUY with a target price of Bt58.00, supported by strong bookings, lower financing costs and margin improvement.
Company Update | Minor International (MINT TB/HOLD/Bt20.50/Target: Bt19.50)
- MINT’s 3Q26 core profit is expected to grow 2.9% yoy to Bt2.85b, supported by hotel RevPar growth, but pressured by rising interest expenses and operating costs. The postponed REIT launch limits deleveraging, while European hotel disposals remain pending. Weak 4Q26 bookings across Thailand, Europe, and the Maldives suggest limited demand recovery. With interest rates unlikely to decline and debt remaining elevated, earnings growth faces continued headwinds. Maintain HOLD, with the target price reduced to Bt19.50.
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


