

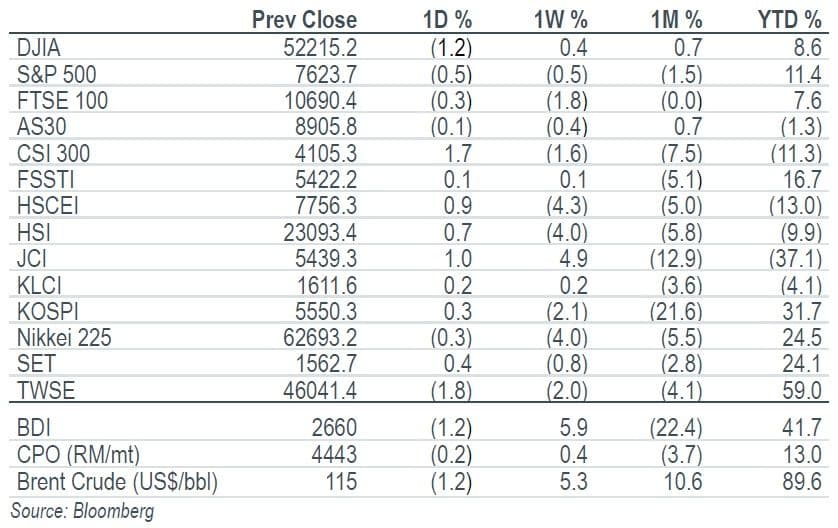
Key Indices
Top Stories
Company Update | Bangchak Corporation (BCP TB/BUY/Bt52.25/Target: Bt65.00)
- We expect BCP to report 3Q26 core profit of Bt11.1b (+249% yoy, -9% qoq), supported by resilient GRM and stronger SAF and renewable contributions, despite refinery maintenance and government diesel price intervention. Looking ahead, 4Q26 earnings should moderate as GRM normalises to around US$10/bbl, partly offset by higher refinery utilisation. Nevertheless, we remain positive on BCP’s medium-term outlook, supported by sustained middle-distillate strength, earnings diversification and SAF expansion. Maintain BUY; target price: Bt65.00 based on 1.0x 2027F P.
Company Update | The Erawan Group (ERW TB/BUY/Bt3.68/Target: Bt4.80)
- ERW’s 3Q26 net profit is expected to be outstanding at Bt181m (+226.7% yoy, +151.9% qoq), supported by stronger ADR across hotel segments, an Bt80m insurance gain, and lower interest expenses. EBITDA margins are expected to improve both yoy and qoq. RevPar growth is estimated at 7% yoy, with strong pricing momentum projected to continue into 4Q26. We raise our 2026-28 earnings forecasts by 6.8%, 8.1% and 12.8% respectively. Maintain BUY with a higher target price of Bt4.80.
Company Update | PTT Global Chemical (PTTGC TB/HOLD/Bt52.00/Target: Bt54.00)
- We expect 3Q26 net profit to decline qoq, driven by a gradual normalisation of the olefins business and the impact of government measures requesting diesel price discounts from refiners. Despite the normalisation in overall business conditions, we believe the earnings outlook remains better than pre-war levels, particularly for the refinery business, where tight overall supply is expected to persist through 1H27. Accordingly, we have revised up our 2026-27 earnings estimates by 5% each. Maintain HOLD. Target price: Bt54.00 (previously Bt48.00).
Company Update | PTT Oil and Retail (OR TB/HOLD/Bt12.60/Target: Bt12.50)
- We expect OR to return to profitability in 3Q26, driven by an improvement in marketing margin and substantial stock gains. However, excluding extra gains, we expect core profit to decline qoq due to the low season. The key issue to monitor is OR’s review of its investment plan in Cambodia, with a conclusion expected by end-26. We believe uncertainty surrounding the investment review will remain an overhang on OR’s share price until greater clarity emerges. Maintain HOLD. Target price: Bt12.50.
What’s Inside
Company Update | Central Pattana (CPN TB/BUY/Bt62.50/Target: Bt80.00)
- Core earnings are expected to grow 12% yoy, driven by revenue growth, gross margin expansion and higher equity income. Continued shopping mall expansion is expected to be a key earnings driver for CPN. Maintain BUY with an SOTP-based target price of Bt80.00.
Company Update | IRPC (IRPC TB/HOLD/Bt2.82/Target: Bt3.00)
- We forecast IRPC to report 3Q26 net profit of Bt6.05b, up 107% qoq and 1,678% yoy, benefitting from a swing to an inventory gain of Bt2.56b. We expect core profit of Bt4.00b, down 9% qoq from Bt4.40b but recovering from a core loss of Bt336m in 3Q25. from a Bt2.50b loss in 2Q26.Going forward, we raise our 2027 net profit forecast by 47% to Bt5.0b from Bt3.5b, primarily reflecting our more positive outlook for diesel refining margins. Maintain HOLD with target price of Bt3.00.
Company Update | MR. D.I.Y. Thailand (MRDIYT TB/BUY/Bt8.10/Target: Bt10.00)
- We expect 3Q26 net profit to increase 7% yoy, with the slower profit growth mainly attributable to a lower gross margin and a larger share of losses from KKV. Operating performance is expected to improve in 4Q26, driving an improvement in earnings momentum. Maintain BUY with a lower target price of Bt10.00 (from Bt11.00).
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


