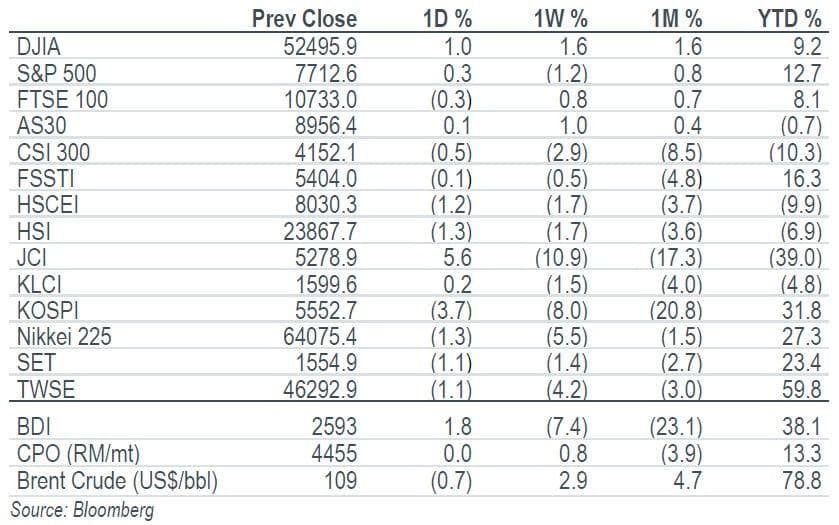
Key Indices
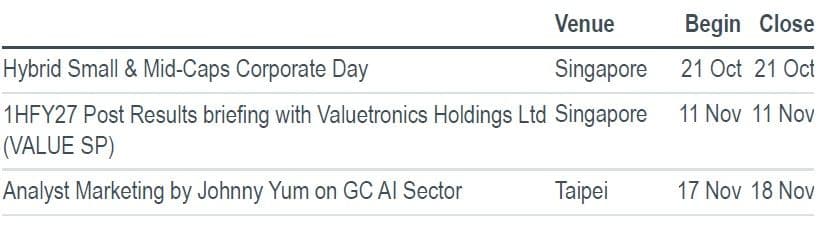
Top Stories
Company Results | Kasikorn Bank (KBANK TB/BUY/Bt234.00/Target: Bt285.00)
- KBANK posted a 3Q26 net profit of Bt12.7b (-2% yoy, -4% qoq). The actual results were in line with our and consensus forecasts. Management maintains its credit cost target for 2026 at 140-160bp, despite the credit cost being reported at the high end of the target range at 160bp. We expect the bank to release capital by increasing its dividend payment or paying out a special dividend. Maintain BUY with a target price of Bt285.00.
Company Results | Krung Thai Bank (KTB TB/BUY/Bt43.25/Target: Bt52.00)
- KTB reported a 3Q26 net profit of Bt12.6b, down 14% yoy but up 4% qoq. The results were in line with our and consensus forecasts. In 9M26, the loan portfolio grew 5.1%, higher than the 2026 loan growth target of 0-2%. Credit costs declined by 12bp qoq. In 9M26, credit costs were reported at 98bp, within its 2026 target range of 75-115bp. Meanwhile, the coverage ratio was 205% in 3Q26. Maintain BUY with a target price of Bt52.00.
Company Results | SCB X (SCB TB/BUY/Bt146.00/Target: Bt180.00)
- SCB reported a 3Q26 net profit of Bt10.7b (-11% yoy, -4% qoq). The results were in line with consensus forecasts but below our expectation by 8% due to a lower-than-expected non-II. Management said the asset quality is well controlled though the company needs another quarter to clean up the loan portfolio in the auto loan business. We should see a stable dividend per share looking forward. Maintain BUY with a lower target price of Bt180.00.
Company Update | Betagro (BTG TB/BUY/Bt20.70/Target: Bt27.00)
- We forecast BTG’s 3Q26 core profit at Bt1,370m (+11.4% yoy and +94.7% qoq). We expect BTG’s earnings to outperform its peers’ due to its greater exposure to the domestic market and lower exposure to uncertainties in international livestock prices. The company is well positioned to benefit from the domestic livestock price upcycle. BTG remains one of our top picks in the sector. Maintain BUY with a higher target price of Bt27.00.
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


