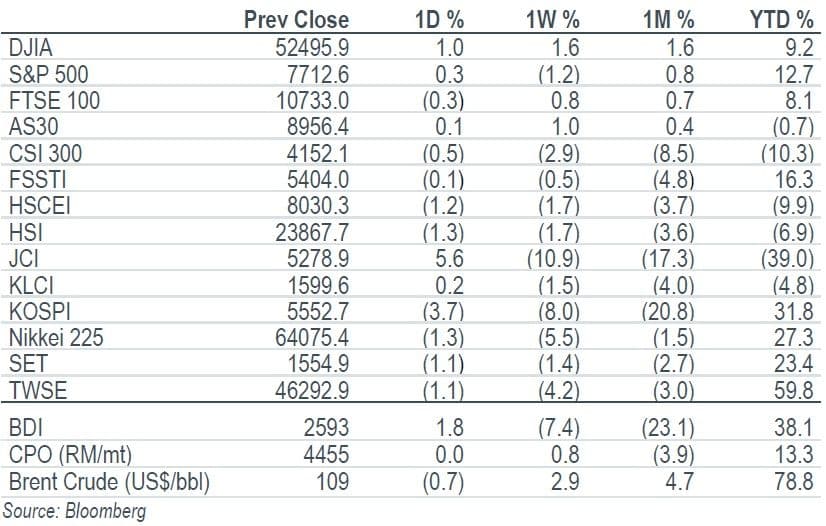
Key Indices
Top Stories
Company Results | Bangkok Bank (BBL TB/BUY/Bt182.50/Target: Bt220.00)
- BBL posted a 3Q26 net profit of B9.5b, down 31% yoy but flat qoq. The results missed our expectations by 10% but were in line with consensus forecasts. The key miss to our forecast was the higher-than-expected opex. BBL is confident about achieving its loan growth target of 3% in 2026. The qoq increase in opex was mainly attributable to accrued expenses and IT-related costs. Credit costs declined qoq with a decrease in NPL ratio. Maintain BUY; target price: Bt220.00.
Company Update | Airports of Thailand (AOT TB/BUY/Bt58.00/Target: Bt85.00)
- AOT’s 4QFY26 net profit is expected at Bt5.6b (+45.5% yoy, +26.5% qoq), supported by the first full quarter of the higher international PSC of Bt1,120, offsetting lower concession revenue from KPD. Despite weaker passenger and flight volumes due to high airfares, traffic recovered in Oct 26, supporting the high season outlook. AOT also has potential upside from new land concessions near Suvarnabhumi Airport and reinstating inbound duty-free shops. Maintain BUY with a target price of Bt85.00.
Company Update | Osotspa (OSP TB/BUY/Bt16.50/Target: Bt22.00)
- Osotspa is expected to report a 3Q26 core profit of Bt856m (+22.3% yoy, but -22.2% qoq). The yoy increase is driven by improved profitability, while the qoq decline reflects seasonal factors. We are now more positive on OSP, as it is supported by resilient gross profit margins despite rising input costs. 4Q26 earnings are expected to rise both yoy and qoq on sustained sales growth and resilient margins. Maintain BUY with a target price of Bt22.00.
Company Update | Thai Oil (TOP TB/BUY/Bt69.75/Target: Bt100.00)
- We expect TOP’s 3Q26 net profit to increase both qoq and yoy. Although market GRM is expected to decline slightly qoq due to government-imposed diesel price discounts and increased jet fuel supply from higher Chinese exports, refining margins should remain high, while higher stock gains will further support earnings. We maintain a positive outlook on GRM, which we expect to remain above pre-war levels in 1H27. Maintain BUY. Target price: Bt100.00 (previously Bt88.00).
What’s Inside
Company Results | Bank of Ayudhya (BAY TB/BUY/Bt39.00/Target: Bt50.00)
- BAY posted a 3Q26 net profit of Bt8.7b, down 1% yoy but up 4% qoq. The results were in line with our and consensus forecasts. BAY reported outstanding loans of around Bt1.95t in 3Q26, decreasing 1% yoy and flat qoq. In 9M26, the total loan portfolio grew 0.4% yoy. Credit costs fell 13bp qoq to 222bp in 3Q26.ASEAN loans recorded robust growth of 7.7% in 9M26, supported by continued market expansion opportunities in the region. Maintain BUY with a target price of Bt50.00.
Company Results | Krungthai Card (KTC TB/BUY/Bt35.50/Target: Bt50.00)
- KTC reported a net profit of Bt2.1b in 3Q26, up 9% yoy but down 5% qoq. The results were in line with our and consensus estimates. The total loan portfolio grew 0.8% in 9M26. Credit costs increased from 490bp in 2Q26 to 540bp in 3Q26. We saw a small increase in gross NPLs for the credit card and personal loan portfolios but a drop in the lease portfolio. KTC will maintain a prudent approach. Maintain BUY; target price: Bt50.00.
Company Results | TMBThanachart Bank (TTB TB/HOLD/Bt2.90/Target: Bt3.20)
- TTB reported 3Q26 net profit of Bt5.46bn (+3% yoy, +0.9% qoq). The results are in line with our and consensus estimates. Loan portfolio contracted 0.8% yoy but expanded 0.3% qoq, while credit cost edged down 1bp qoq to 136bp. TTB continues to expand high-yield lending and expects wealth management to drive fee income growth. Management prefers share buybacks and higher regular dividends over a special dividend to enhance shareholder returns. Maintain HOLD on TTB with a target price of Bt3.20.
Company Update | GFPT (GFPT TB/BUY/Bt10.10/Target: Bt11.40)
- We expect GFPT to report a 3Q26 core profit of Bt584m (-17.8% yoy, flat qoq). Overall, we foresee the results being in line with our previous expectations but lower than market expectations. The key qoq pressure is expected to come from a lower gross profit margin, partly offset by higher sales and an increased share of profit. Maintain BUY with a target price of Bt11.40.
Company Update | Kiatnakin Phatra Bank (KKP TB/BUY/Bt114.50/Target: Bt150.00)
- The tone during the analyst meeting was positive. Management said overall businesses are on track. Asset quality is healthy, and the wealth business performed well. The bank has added management overlay as a buffer for: a) economic uncertainties, and b) flooding impacts. The wealth management business is one of the prominent drivers to boost non-II. Meanwhile, Dime is growing fast and would soon become the key driver for non-II. Maintain BUY on KKP with a target price of Bt150.00.
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


