

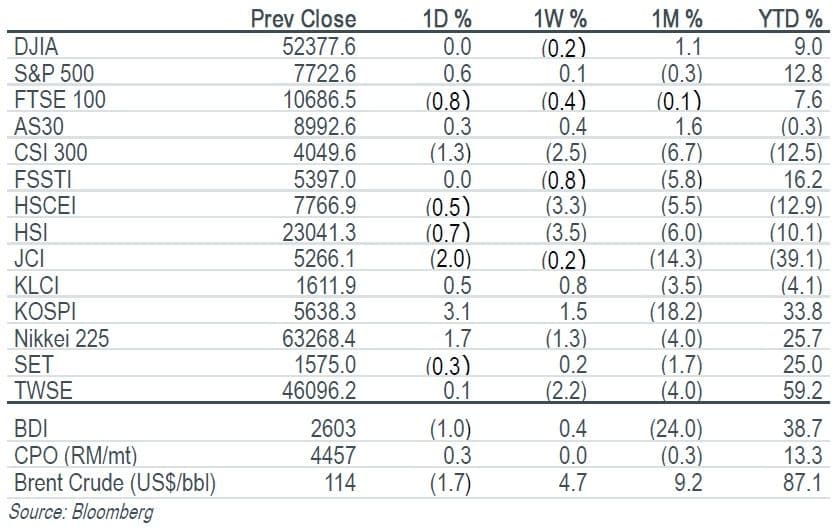
Key Indices
Top Stories
Company Update | Amata Corporation (AMATA TB/BUY/Bt28.75/Target: Bt38.00)
- We expect AMATA to report a 3Q26 net profit of Bt710m (-38% yoy, -55% qoq). Revenue is forecast at Bt3.6b (-17% yoy, -2% qoq), supported by 258 rai of land transfers and an increase in prices. 9M26 land sales reached 605 rai, or 28% of the full-year target. Thailand's high-potential pipeline stands at 800 rai including 200 rai from data centre customers. Maintain BUY with an unchanged target price of Bt38.00.
Company Update | Bangkok Chain Hospital (BCH TB/BUY/Bt10.80/Target: Bt13.00)
- BCH expects a 3Q26 net profit of Bt360m (+3.5% yoy, +4.8% qoq), supported by Thai and foreign patient growth. The SSO’s 3-4% capitation rate increase from Jan 27 should benefit earnings. The floods in Sep-Oct 26 are expected to have a limited impact on a revenue of Bt23m. The newly-acquired KIH Ubon has turned profitable, with further upside from pricing adjustments and cost savings. Maintain BUY with a target price of Bt13.00, supported by an earnings recovery and improving operations.
Company Update | SCG Packaging (SCGP TB/BUY/Bt29.25/Target: Bt43.00)
- The 4Q26 outlook remains strong, supported by recovering demand following the floods in Thailand and inventory restocking ahead of the New Year festive season in Thailand, Vietnam and Indonesia. Continued selling price hikes should help mitigate the impact of higher production costs. For 3Q26, SCGP reported a net profit of Bt2.03b, down 12% qoq but up 113% yoy, in line with our and consensus estimates. Maintain BUY. Target price: Bt43.00.
Company Update | Thaifoods Group (TFG TB/BUY/Bt9.55/Target: Bt13.00)
- We expect TFG to report a 3Q26 core profit of Bt1,810m (+5.1% yoy, +20.7% qoq). TFG is well positioned to benefit from an earnings recovery theme on higher domestic livestock prices in 3Q26 thanks to high exposure to the Thai market. We reaffirm our positive view on TFG for both the short and long term on the back of the ongoing livestock price upcycle and continued retail revenue growth. Maintain BUY with a higher target price of Bt13.00.
What’s Inside
Company Update | Star Petroleum Refining (SPRC TB/BUY/Bt15.20/Target: Bt17.00)
- We upgrade SPRC to BUY with a higher target price of Bt17.00, reflecting resilient refining margins and potential earnings upgrades. We forecast 3Q26 net profit of Bt9.5b (+504% yoy, +38% qoq), supported by inventory gains, while core profit should reach Bt4.2b (+269% yoy). Market GRM remains strong at US$15/bbl. Despite higher crude premiums and government diesel price cuts weighing on earnings, we expect refining margins to remain above historical mid-cycle levels throughout 1H27, supporting SPRC’s earnings outlook.
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


