

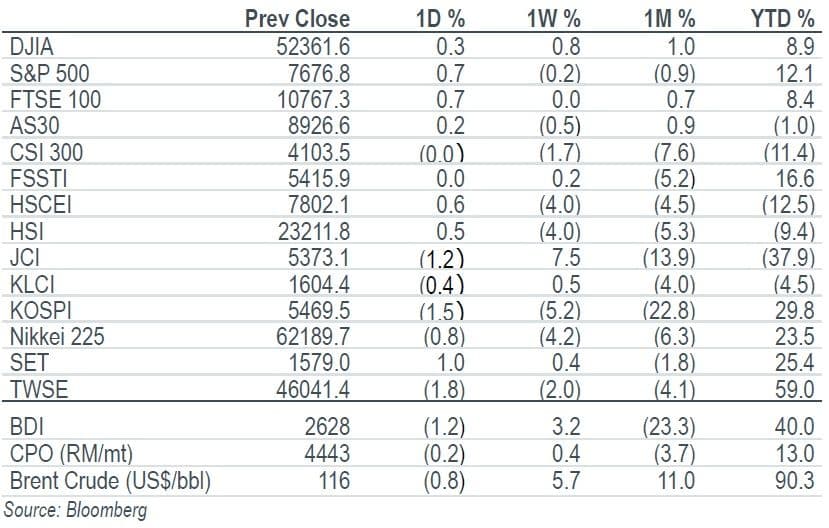
Key Indices
Top Stories
Sector Update | Banking
- Banks under our coverage reported a net profit of Bt63.8b, down 10% yoy and flat qoq, in line with our and market expectations. We expect banks to continue to focus on growing the wealth business to boost non-II going forward. Banks have stated that they have adequate provisions to cushion against many uncertainties including the flooding in late-Sep 26. Maintain OVERWEIGHT. Our top picks are KBANK and KTB.
Company Update | HANA (Thailand) (HANA TB/BUY/Bt47.50/Target: Bt56.00)
- We expect HANA to report a 3Q26 core profit of Bt303m (+697% yoy, +9% qoq), continuing its earnings recovery. Earnings recovery in 2H26 should be driven by narrowing losses at PMS, higher IC utilisation rates and resilient PCBA sales. HANA entered mass production for two AI-related projects in 3Q26, including solid-state cooling and high-density PCBA. Maintain BUY with a higher target price of Bt56.00, backed by a 38% earnings CAGR in 2026-28 and continued operational improvements at PMS in 2H26.
Company Update | i-Tail Corporation (ITC TB/BUY/Bt17.10/Target: Bt22.00)
- ITC announced the acquisition of Phelps, which is a US-based manufacturer and distributor of pet food products. We view the acquisition positively for ITC’s long-term US business, attributable to commercial expansion and operational synergies. Maintain BUY with a target price of Bt22.00.
Company Update | Praram 9 Hospital (PR9 TB/BUY/Bt19.00/Target: Bt24.60)
- PR9 is expected to deliver a 3Q26 net profit of Bt232m (+3.7% yoy, +25.7% qoq), supported by Thai patient revenue growth, higher margins and cost control. The Bangkok floods temporarily disrupted hospital access, but deferred appointments should support 4Q26 revenue. The outlook remains positive, driven by recovering Middle Eastern patient arrivals, pent-up demand, and strict cost management. PR9 is expanding its specialty care market reach and investing in advanced technology. Maintain BUY with a target price of Bt24.60.
What’s Inside
Company Update | AP (Thailand) (AP TB/BUY/Bt8.05/Target: Bt9.25)
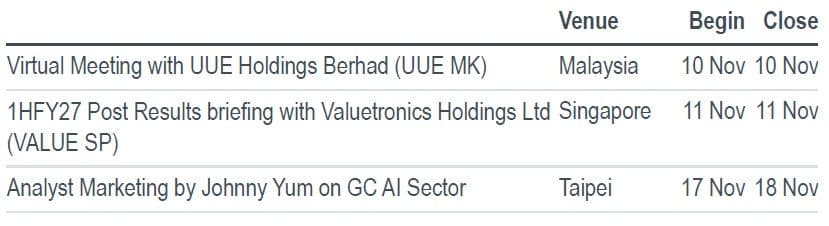
- AP will report its 3Q26 earnings on 12 November, with an expected net profit of Bt1.14b (+7.4% qoq, -1.1% yoy), supported by property transfers of Bt11.0b and presales of Bt13.40b. Gross margin is forecast at 29.9%, while JV profit contribution should recover to Bt121m, driven by new project transfers. Government housing stimulus may provide an additional upside, although near-term benefits remain limited. Maintain BUY with a target price of Bt9.25, supported by resilient operations and a strong competitive position in Thailand’s property market.
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


