

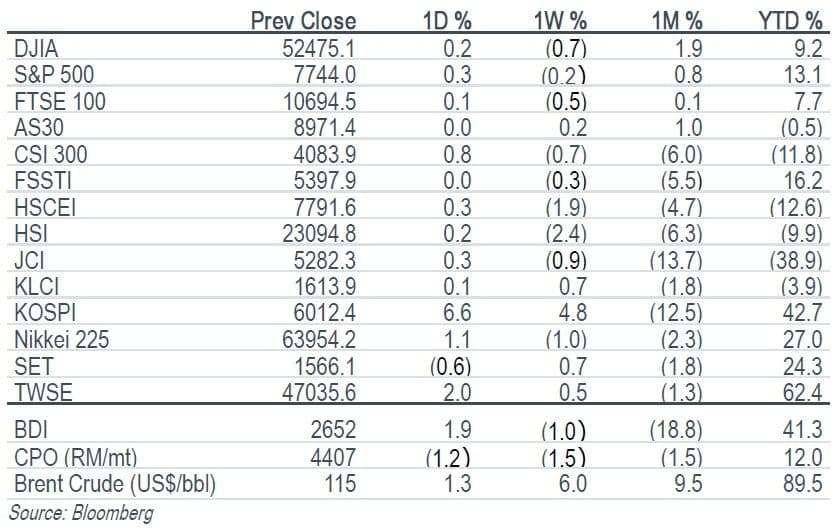
Key Indices
Top Stories
Sector Update | Oil and Gas
- Refinery stocks yesterday traded lower due to new fuel price reforms, effective on 29 Oct 26, a negative surprise. However, we expect overall impact to be manageable. Meanwhile, the government is reducing the existing diesel price cut from Bt4.00 to Bt2.00 per litre, effective 1 to 30 November, which is better than our current assumption. Maintain MARKET WEIGHT. TOP and SCGP remain our top picks in the sector.
Company Results | Siam Cement (SCC TB/HOLD/Bt278.00/Target: Bt278.00)
- SCC reported 3Q26 net profit of Bt2.39b, down 79% qoq, and 27% and 42% below our and consensus estimates respectively, due to a steeper-than-expected decline in chemical sales. Earnings from CBM and packaging also weakened due to seasonal factors. However, we expect net profit to recover qoq in 4Q26, supported by dividend income and a recovery in the chemical business. Maintain HOLD. Target price: Bt278.00.
Company Update | Delta (Thailand) (DELTA TB/HOLD/Bt232.00/Target: Bt280.00)
- DELTA reported a net profit of Bt7.76b (+4% yoy, +28% qoq), 14% below our and market expectations, as continued inventory provisions limited margin recovery. Management guided for very strong sales growth in 4Q26, supported by orders that were not fully delivered during 2Q-3Q26 and no sign of demand slowdown for the next one year. Inventory provision risks are expected to persist throughout 1Q27, but we remain bullish on sales growth over the next 12 months. Maintain BUY. Lower target price to Bt280.00.
Company Update | WHA Corporation (WHA TB/BUY/Bt4.88/Target: Bt6.10)
- We expect WHA to report 3Q26 core earnings of Bt936m (+38% yoy, +55% qoq), supported by higher land selling prices and improved margins. Revenue is expected to reach Bt2.8b (+46% yoy, +13% qoq), driven by higher industrial estate revenue and continued growth in recurring businesses. Management reiterated its Thailand land sales target, although Vietnam remains challenging despite some improvement in its sales pipeline. Maintain BUY with a target price of Bt6.10.
What’s Inside
Company Update | Bangkok Bank (BBL TB/BUY/Bt185.00/Target: Bt220.00)
- We came away from BBL’s analyst meeting with a neutral view. Management said NIM has already bottomed out and showed a slight increase qoq in 3Q26, while maintaining its 2026 financial targets. Management stated that the 2026 credit cost should be slightly above 1%. BBL confirmed that there are no impairment losses on Permata Bank due to the good performance and high coverage. Maintain BUY with a target price of Bt220.00.
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


