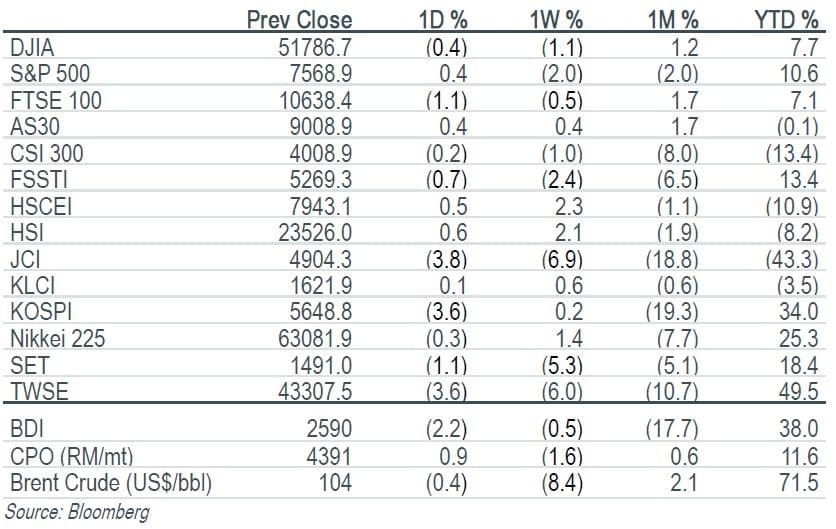
Key Indices
Top Stories
Company Results | Home Product Center (HMPRO TB/BUY/Bt6.40/Target: Bt8.00)
- HMPRO reported 3Q26 net profit of Bt1.32b (+1% yoy,-17% qoq), in line with our and consensus estimates. October SSSG remained promising, with HomePro’s at +6.5% yoy and Mega Home’s at +11.5% yoy, driven by post-flood demand for home repairs. With annual store expansion slowing to around five stores, earnings growth will be driven primarily by gross margin improvement. Maintain BUY with a target price of Bt8.00. The stock offers an attractive valuation, with a 5.8% dividend yield and 14x PE.
Company Update | Advance Info Services (ADVANC TB/BUY/Bt340.00/Target: Bt415.00)
- ADVANC reported a 3Q26 net profit of Bt13.5b (+12% yoy, -2% qoq), slightly above our and Bloomberg consensus by 1.2% and 2.8%. Strong handset sales drove the 3Q26 beat, offsetting softer core service revenue. The tone at the meeting was positive. Core service sales growth is expected to meet the upper bound of its 2026 guidance, while EBITDA growth is likely to beat guidance. Maintain BUY with a target price of Bt415.00.
Top Stories
Company Results | Home Product Center (HMPRO TB/BUY/Bt6.40/Target: Bt8.00)
- HMPRO reported 3Q26 net profit of Bt1.32b (+1% yoy,-17% qoq), in line with our and consensus estimates. October SSSG remained promising, with HomePro’s at +6.5% yoy and Mega Home’s at +11.5% yoy, driven by post-flood demand for home repairs. With annual store expansion slowing to around five stores, earnings growth will be driven primarily by gross margin improvement. Maintain BUY with a target price of Bt8.00. The stock offers an attractive valuation, with a 5.8% dividend yield and 14x PE.
Company Update | Advance Info Services (ADVANC TB/BUY/Bt340.00/Target: Bt415.00)
- ADVANC reported a 3Q26 net profit of Bt13.5b (+12% yoy, -2% qoq), slightly above our and Bloomberg consensus by 1.2% and 2.8%. Strong handset sales drove the 3Q26 beat, offsetting softer core service revenue. The tone at the meeting was positive. Core service sales growth is expected to meet the upper bound of its 2026 guidance, while EBITDA growth is likely to beat guidance. Maintain BUY with a target price of Bt415.00.
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


