

Company Coverage
PTT Oil and Retail (OR TB): 3Q26 Results Preview: Earnings Expected To Return To Profitability
HOLD (Maintained)
Current price:
Target price:
Upside:
Bt12.60
Bt12.50
-0.79%
Analyst
Highlights
- We expect OR to return to profitability in 3Q26, driven by a higher marketing margin and substantial stock gains.
- Uncertainty surrounding the review of its Cambodia investment plan remains an overhang on OR’s share price.
- Maintain HOLD with a target price of Bt12.50.
Analysis
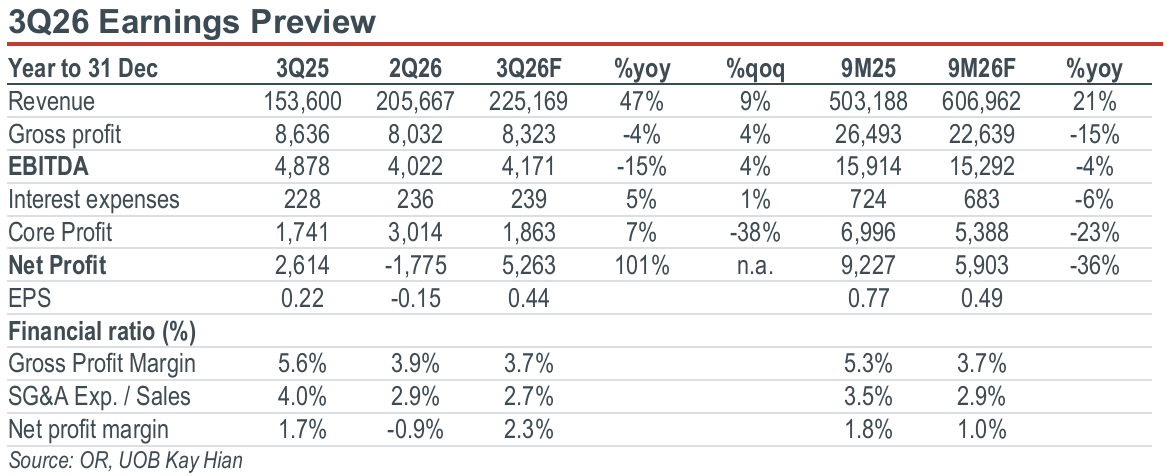
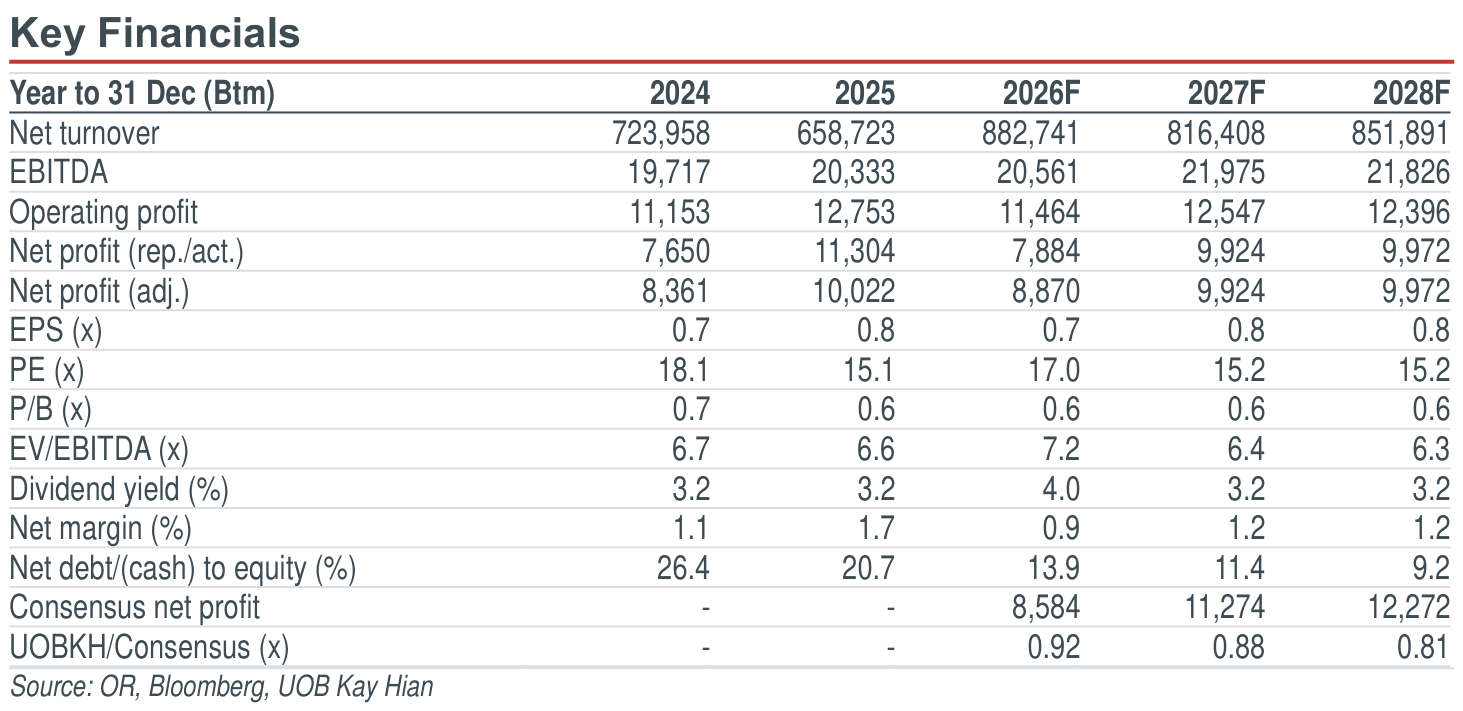
- 3Q26 earnings outlook. We expect PTT Oil and Retail (OR) to report a net profit of Bt5.26b in 3Q26, reversing from a net loss of Bt1.78b in 2Q26, driven by a higher marketing margin and stock gains in the mobility business. Excluding extra gains, core profit is estimated at Bt1.86b, down 38% qoq due to the seasonal low season. 9M26 net profit is expected to account for 75% of our 2026 forecast.
- Higher marketing margin offsets seasonally lower sales volume. We expect the mobility business’ profit to increase qoq, supported by a sharp recovery in marketing margin to Bt1.50/litre (vs Bt0.24/litre in 2Q26), more than offsetting the lower fuel sales volume amid higher oil prices and seasonal weakness. Oil sales volume is estimated at 5,480m litres, down 1.4% qoq and 7.6% yoy. However, excluding stock gains of Bt3.4b in 3Q26, the underlying marketing margin would be Bt1.10/litre, compared with Bt1.50/litre in 2Q26.
- Sales volume pressured by government measures and seasonal factors. We expect the lifestyle segment’s profit to decline qoq due to the impact of the Thai Chuay Thai Plus Co-Payment Scheme as well as seasonal weakness. Café Amazon coffee sales are expected to edge down qoq to 116m cups, while the lifestyle EBITDA margin should remain near the targeted 30% (vs 30.8% in 2Q26).
Highlights
- We expect OR to return to profitability in 3Q26, driven by a higher marketing margin and substantial stock gains.
- Uncertainty surrounding the review of its Cambodia investment plan remains an overhang on OR’s share price.
- Maintain HOLD with a target price of Bt12.50.
Analysis
- 3Q26 earnings outlook. We expect PTT Oil and Retail (OR) to report a net profit of Bt5.26b in 3Q26, reversing from a net loss of Bt1.78b in 2Q26, driven by a higher marketing margin and stock gains in the mobility business. Excluding extra gains, core profit is estimated at Bt1.86b, down 38% qoq due to the seasonal low season. 9M26 net profit is expected to account for 75% of our 2026 forecast.
- Higher marketing margin offsets seasonally lower sales volume. We expect the mobility business’ profit to increase qoq, supported by a sharp recovery in marketing margin to Bt1.50/litre (vs Bt0.24/litre in 2Q26), more than offsetting the lower fuel sales volume amid higher oil prices and seasonal weakness. Oil sales volume is estimated at 5,480m litres, down 1.4% qoq and 7.6% yoy. However, excluding stock gains of Bt3.4b in 3Q26, the underlying marketing margin would be Bt1.10/litre, compared with Bt1.50/litre in 2Q26.
- Sales volume pressured by government measures and seasonal factors. We expect the lifestyle segment’s profit to decline qoq due to the impact of the Thai Chuay Thai Plus Co-Payment Scheme as well as seasonal weakness. Café Amazon coffee sales are expected to edge down qoq to 116m cups, while the lifestyle EBITDA margin should remain near the targeted 30% (vs 30.8% in 2Q26).
HOLD (Maintained)
Current price:
Target price:
Upside:
Bt12.60
Bt12.50
-0.79%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

28 Sept 2026
Delta (Thailand) (DELTA TB) : 3Q26 Results Preview: Earnings Expected To Improve qoq, Driven By Higher Sales And Margins

21 Oct 2026
Osotspa (OSP TB): 3Q26 Results Preview: Margins Expected To Remain Resilient

21 Oct 2026
Thai Oil (TOP TB): Strong Market GIM To Drive Robust 3Q26 Earnings
Our latest research

26 Oct 2026
Bangchak Corporation (BCP TB): Expect Another Solid Quarter

26 Oct 2026
PTT Global Chemical (PTTGC TB): 3Q26 Earnings Expected To Decline qoq

26 Oct 2026