

Company Coverage
The Erawan Group (ERW TB): 3Q26 Results Preview: Expect Outstanding Earnings
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt3.68
Bt4.80
+30.4%
Bt4.40
Analyst
Analyst
Nonpawit Vathanadachakul
Highlights
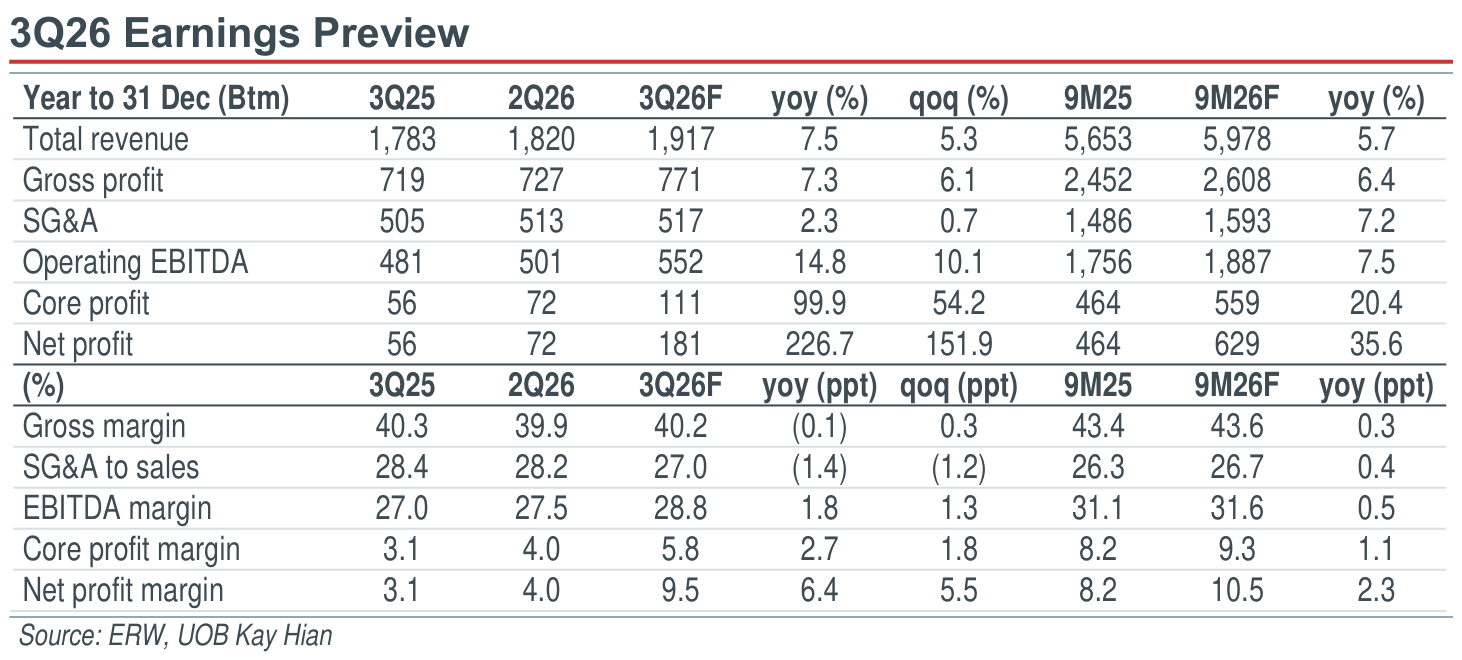
- We expect ERW to report an outstanding net profit of Bt181m (+226.7% yoy, +151.9% qoq) in 3Q26.
- We are seeing a strong trend of room rate pricing power in 3Q26 and 4Q26 thus far due to strong booking demand from foreign tourists.
- We remain optimistic on ERW and maintain it as one of our top picks in the hotel sector. The decline in interest cost remains the key growth driver and the booking demand remains robust in 4Q26. Maintain BUY with a target price of Bt4.80 (previously: Bt4.40).
Analysis
- Outstanding yoy earnings growth expected in 3Q26. We expect The Erawan Group (ERW) to report an outstanding net profit of Bt181m (+226.7% yoy, +151.9% qoq) in 3Q26. Top-line should come in at Bt1.92b (+7.5% yoy, +5.3% qoq). The strong earnings growth should mainly be contributed by a strong yoy increase in average daily rate (ADR) across all segments of ERW’s hotel portfolio and an extra Bt80m gain from insurance claims related to last year’s earthquake. This should lead to a 7.0% yoy growth in RevPar of the total portfolio (excluding Hop Inns). Meanwhile, the RevPar of Hop Inn hotels excluding new openings should increase around 1% yoy, driven by ADR. Interest expense is expected to decrease significantly by 15% yoy and 10% qoq due to the declining cost of debt. We also expect EBITDA margin to expand significantly both yoy and qoq.
Highlights
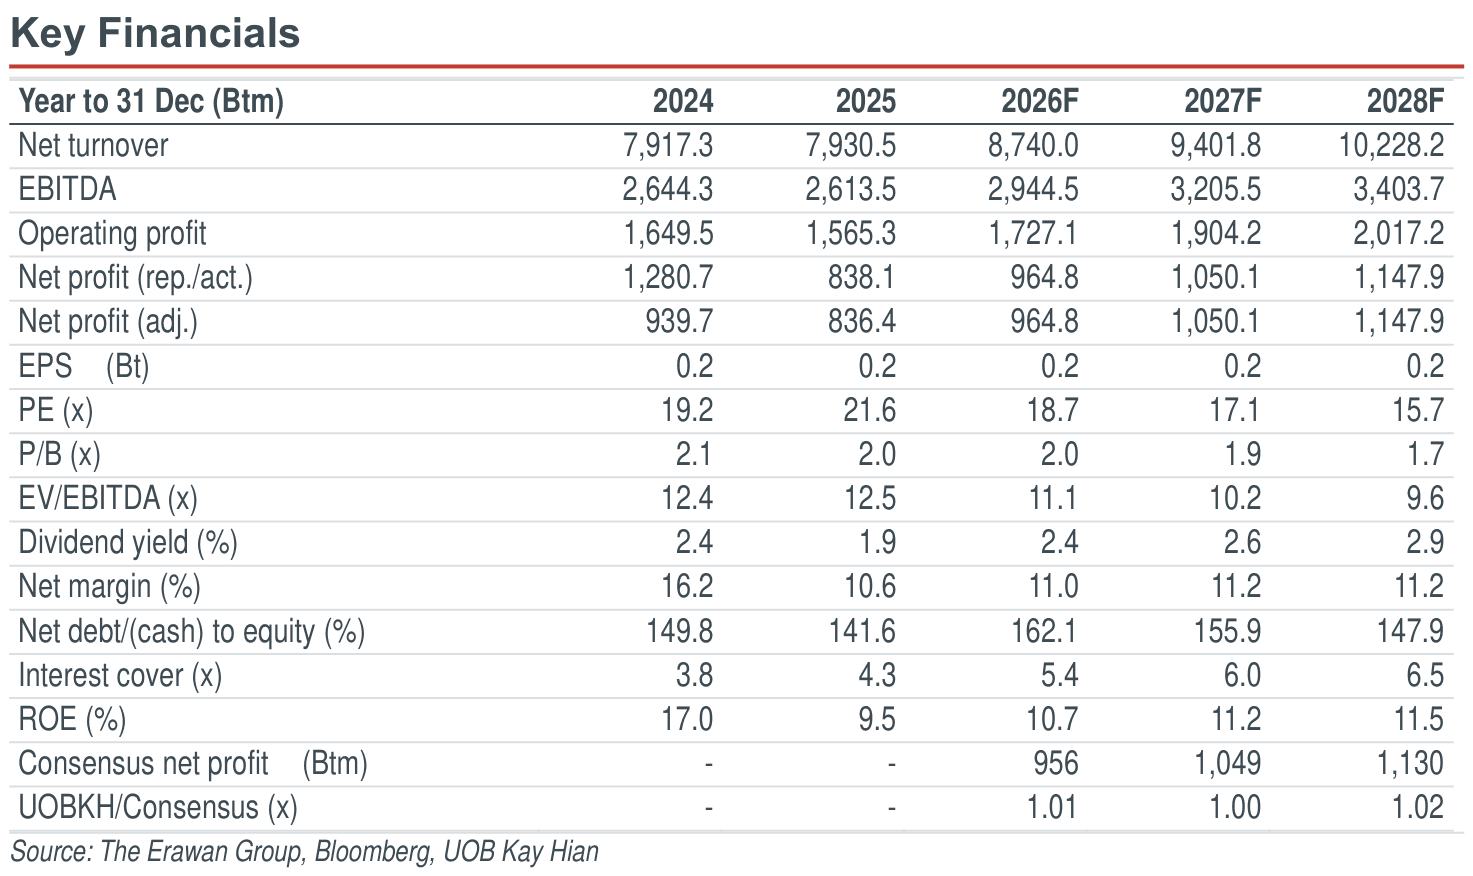
- We expect ERW to report an outstanding net profit of Bt181m (+226.7% yoy, +151.9% qoq) in 3Q26.
- We are seeing a strong trend of room rate pricing power in 3Q26 and 4Q26 thus far due to strong booking demand from foreign tourists.
- We remain optimistic on ERW and maintain it as one of our top picks in the hotel sector. The decline in interest cost remains the key growth driver and the booking demand remains robust in 4Q26. Maintain BUY with a target price of Bt4.80 (previously: Bt4.40).
Analysis
- Outstanding yoy earnings growth expected in 3Q26. We expect The Erawan Group (ERW) to report an outstanding net profit of Bt181m (+226.7% yoy, +151.9% qoq) in 3Q26. Top-line should come in at Bt1.92b (+7.5% yoy, +5.3% qoq). The strong earnings growth should mainly be contributed by a strong yoy increase in average daily rate (ADR) across all segments of ERW’s hotel portfolio and an extra Bt80m gain from insurance claims related to last year’s earthquake. This should lead to a 7.0% yoy growth in RevPar of the total portfolio (excluding Hop Inns). Meanwhile, the RevPar of Hop Inn hotels excluding new openings should increase around 1% yoy, driven by ADR. Interest expense is expected to decrease significantly by 15% yoy and 10% qoq due to the declining cost of debt. We also expect EBITDA margin to expand significantly both yoy and qoq.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt3.68
Bt4.80
+30.4%
Bt4.40
Analyst
Analyst
Nonpawit Vathanadachakul
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

19 Oct 2026
COM7 (COM7 TB): Earnings Expected To Surge In 3Q26

25 Sept 2026
i-Tail Corporation (ITC TB): 3Q26 Results Preview: Sustained Strong Sales Growth Momentum

28 Sept 2026
Delta (Thailand) (DELTA TB) : 3Q26 Results Preview: Earnings Expected To Improve qoq, Driven By Higher Sales And Margins
Our latest research

26 Oct 2026
Bangchak Corporation (BCP TB): Expect Another Solid Quarter

26 Oct 2026
PTT Global Chemical (PTTGC TB): 3Q26 Earnings Expected To Decline qoq

26 Oct 2026