

Company Coverage
PTT Global Chemical (PTTGC TB): 3Q26 Earnings Expected To Decline qoq
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt52.00
Bt54.00
+3.85%
Bt48.00
Analyst
Analyst
Highlights
- We expect 3Q26 net profit to decline qoq, driven by further normalisation in the olefins business and the impact of government measures requesting diesel price discounts from refiners.
- Despite the gradual normalisation of business conditions, we expect the overall outlook to remain better than pre-war levels, particularly for the refinery business, where supply is expected to remain tight through 1H27.
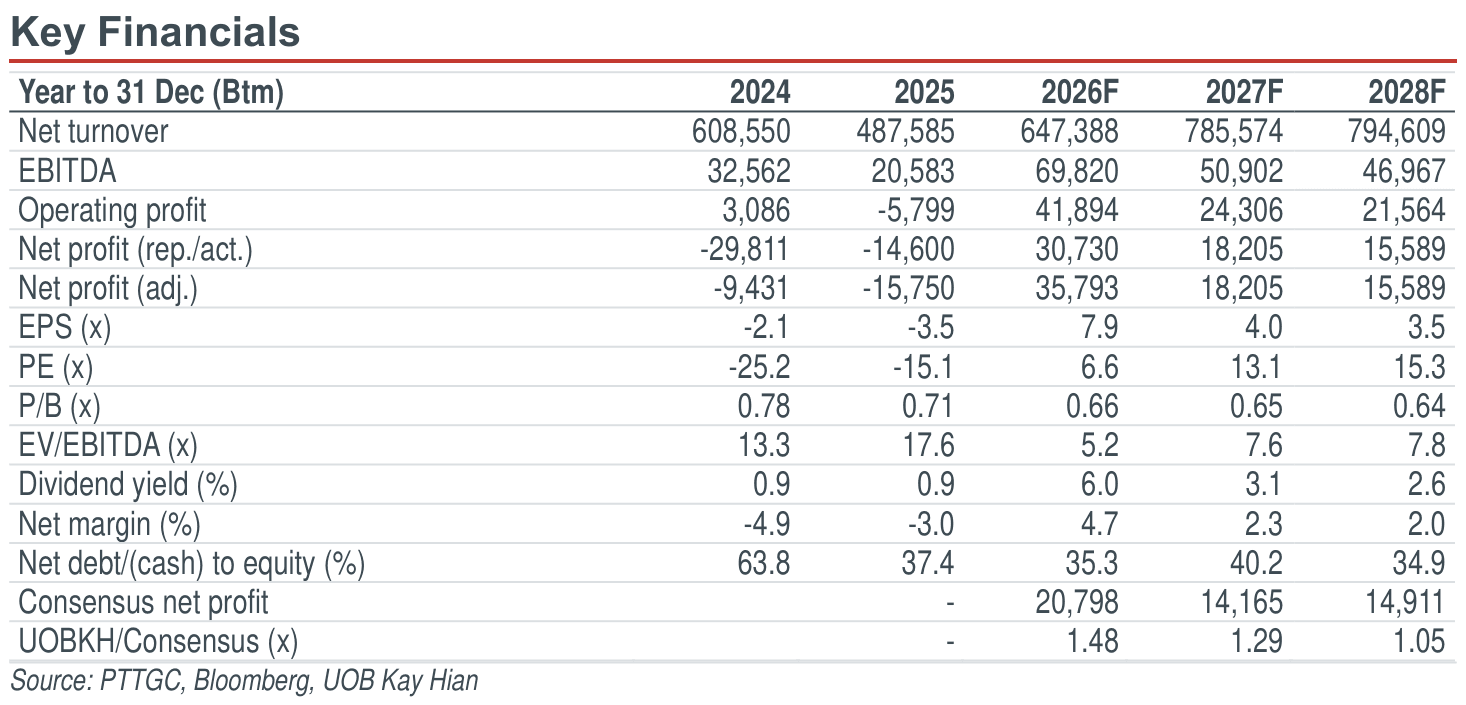
- Maintain HOLD with a target price of Bt54.00 (previously Bt48.00).
Analysis
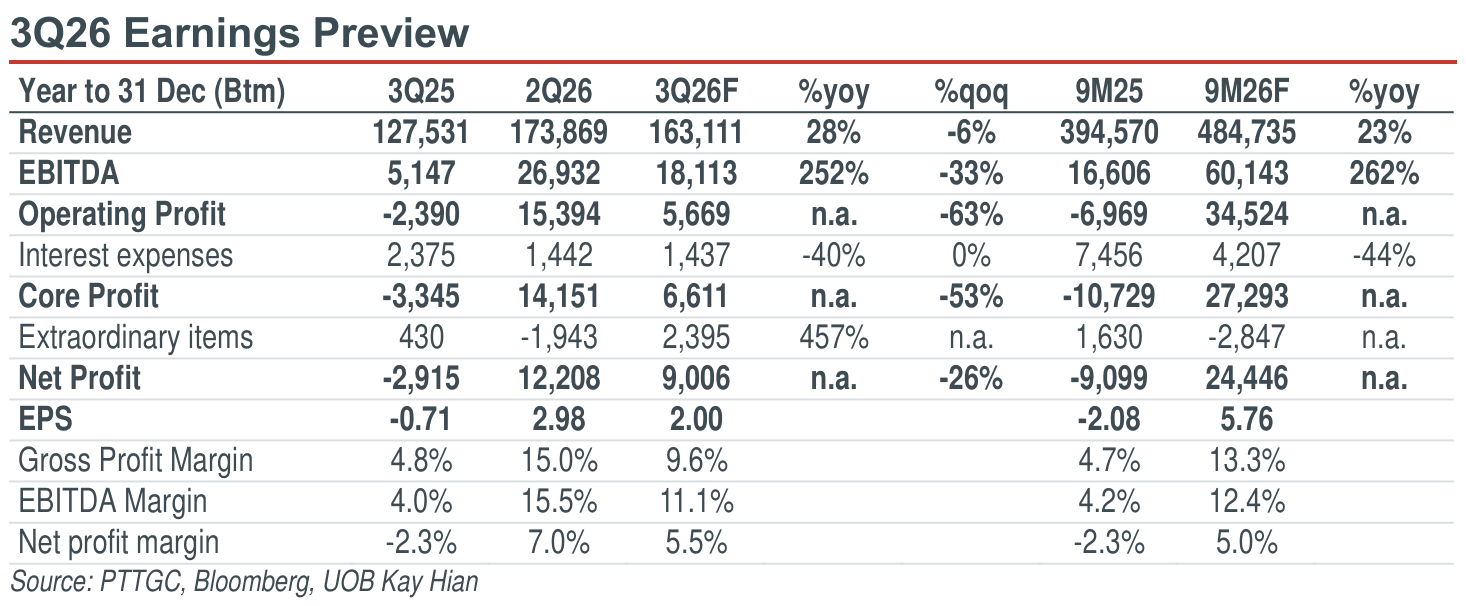
- 3Q26 earnings outlook. We expect PTT Global Chemical (PTTGC) to report 3Q26 net profit of Bt9.01b, down 26% qoq, but recovering from a net loss of Bt2.92b in 3Q25. Excluding extra gains, core profit is estimated at Bt6.61b, down 53% qoq, due to lower prices and spreads in the olefins business, alongside a greater impact from government requests for diesel price discounts.
- Refinery business. We expect refinery EBITDA to decline qoq due to the impact from government intervention, including: a) increased requests for diesel price discounts, and b) restrictions on diesel exports. These measures are expected to weigh on market gross refinery margin (GRM) and utilisation. We estimate 3Q26 market GRM at US$15.00/bbl, down from US$15.60/bbl in 2Q26, while utilisation is expected to decline to 90% from 96%.
- Olefins business. Supply conditions eased in 3Q26, leading high-density polyethylene (HDPE) prices and spreads to gradually decline from late-2Q26 and weigh on olefins chain EBITDA. In addition, the naphtha feedstock mix is expected to increase to 45%, as naphtha replaces lower-cost liquefied petroleum gas (LPG) and Ethane amid the shutdown of both Aromatics unit #1 (ARO1) and PTT's Third Gas Separation Plant (GSP #3). This higher-cost feedstock mix is expected to further pressure EBITDA margin.
Highlights
- We expect 3Q26 net profit to decline qoq, driven by further normalisation in the olefins business and the impact of government measures requesting diesel price discounts from refiners.
- Despite the gradual normalisation of business conditions, we expect the overall outlook to remain better than pre-war levels, particularly for the refinery business, where supply is expected to remain tight through 1H27.
- Maintain HOLD with a target price of Bt54.00 (previously Bt48.00).
Analysis
- 3Q26 earnings outlook. We expect PTT Global Chemical (PTTGC) to report 3Q26 net profit of Bt9.01b, down 26% qoq, but recovering from a net loss of Bt2.92b in 3Q25. Excluding extra gains, core profit is estimated at Bt6.61b, down 53% qoq, due to lower prices and spreads in the olefins business, alongside a greater impact from government requests for diesel price discounts.
- Refinery business. We expect refinery EBITDA to decline qoq due to the impact from government intervention, including: a) increased requests for diesel price discounts, and b) restrictions on diesel exports. These measures are expected to weigh on market gross refinery margin (GRM) and utilisation. We estimate 3Q26 market GRM at US$15.00/bbl, down from US$15.60/bbl in 2Q26, while utilisation is expected to decline to 90% from 96%.
- Olefins business. Supply conditions eased in 3Q26, leading high-density polyethylene (HDPE) prices and spreads to gradually decline from late-2Q26 and weigh on olefins chain EBITDA. In addition, the naphtha feedstock mix is expected to increase to 45%, as naphtha replaces lower-cost liquefied petroleum gas (LPG) and Ethane amid the shutdown of both Aromatics unit #1 (ARO1) and PTT's Third Gas Separation Plant (GSP #3). This higher-cost feedstock mix is expected to further pressure EBITDA margin.
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt52.00
Bt54.00
+3.85%
Bt48.00
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


