Company Coverage
Thai Oil (TOP TB): Strong Market GIM To Drive Robust 3Q26 Earnings
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt69.75
Bt100.00
+43.37%
Bt88.00
Analyst
Analyst
Highlights
- We expect TOP’s 3Q26 net profit to increase both qoq and yoy, driven by a persistently high market GIM and higher stock gains.
- The CFP project continues to progress, with TOP maintaining its target for full COD in 3Q28. A decision on the ERU project is expected by end-October.
- Maintain BUY. Target price: Bt100.00.
What’s News
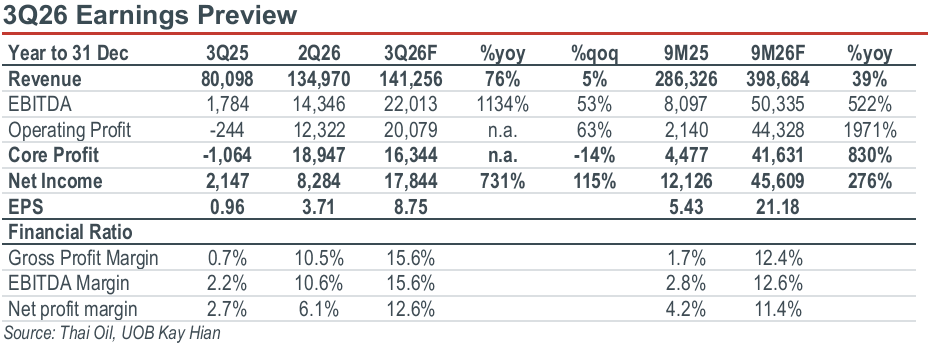
- 3Q26 net profit expected to increase both qoq and yoy. We expect Thai Oil (TOP) to report a 3Q26 net profit of Bt17.84b, up 115% qoq and 731% yoy, driven by a still-high market gross integrated margin (GIM) and higher stock gains. Excluding extra gains, we expect 3Q26 core profit of Bt16.34bn, down 14% qoq. 9M26’s core profit would account for 87% of our 2026 forecast.
- Market GIM remains high. We expect market GIM to reach US$23.20/bbl in 3Q26 (vs US$23.9/bbl in 2Q26), remaining at a high level. Market gross refinery margin (GRM) is projected at US$20.50/bbl (vs US$21.2/bbl in 2Q26). The modest qoq decline reflects increased jet fuel supply following higher Chinese exports to the region, as well as the impact of government measures requiring refineries to provide diesel price discounts. We estimate the government measures reduced GRM by approximately US$3.00/bbl or Bt2.59b after tax in 3Q26, comprising discounts of Bt1.40/litre from 9-23 July, Bt2.40/litre from 24 July to 15 September, and Bt4.00/litre from 16-30 September.
- Subsidiary contributions remain stable qoq. We expect contributions from Thai paraxylene (TPX) and Thai Lube Base (TLB) to remain unchanged qoq at US$2.70/bbl. Despite higher utilisation rates at both subsidiaries, with TPX rising to 74% (vs 67% in 2Q26) and TLB increasing to 122% (vs 118% in 2Q26), the improvement is offset by weaker product spreads.
Highlights
- We expect TOP’s 3Q26 net profit to increase both qoq and yoy, driven by a persistently high market GIM and higher stock gains.
- The CFP project continues to progress, with TOP maintaining its target for full COD in 3Q28. A decision on the ERU project is expected by end-October.
- Maintain BUY. Target price: Bt100.00.
What’s News
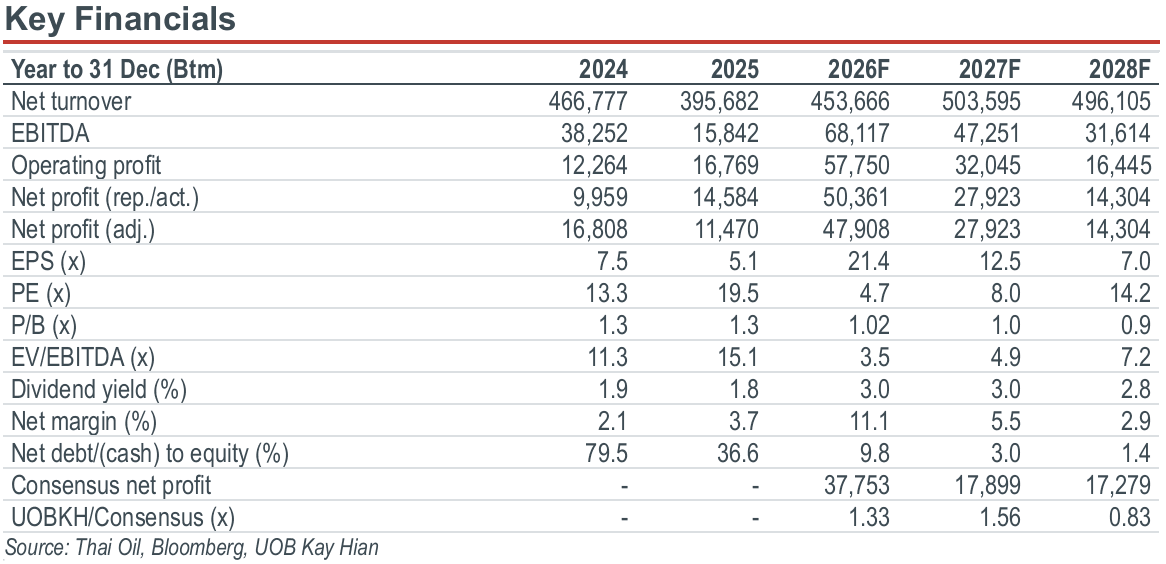
- 3Q26 net profit expected to increase both qoq and yoy. We expect Thai Oil (TOP) to report a 3Q26 net profit of Bt17.84b, up 115% qoq and 731% yoy, driven by a still-high market gross integrated margin (GIM) and higher stock gains. Excluding extra gains, we expect 3Q26 core profit of Bt16.34bn, down 14% qoq. 9M26’s core profit would account for 87% of our 2026 forecast.
- Market GIM remains high. We expect market GIM to reach US$23.20/bbl in 3Q26 (vs US$23.9/bbl in 2Q26), remaining at a high level. Market gross refinery margin (GRM) is projected at US$20.50/bbl (vs US$21.2/bbl in 2Q26). The modest qoq decline reflects increased jet fuel supply following higher Chinese exports to the region, as well as the impact of government measures requiring refineries to provide diesel price discounts. We estimate the government measures reduced GRM by approximately US$3.00/bbl or Bt2.59b after tax in 3Q26, comprising discounts of Bt1.40/litre from 9-23 July, Bt2.40/litre from 24 July to 15 September, and Bt4.00/litre from 16-30 September.
- Subsidiary contributions remain stable qoq. We expect contributions from Thai paraxylene (TPX) and Thai Lube Base (TLB) to remain unchanged qoq at US$2.70/bbl. Despite higher utilisation rates at both subsidiaries, with TPX rising to 74% (vs 67% in 2Q26) and TLB increasing to 122% (vs 118% in 2Q26), the improvement is offset by weaker product spreads.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt69.75
Bt100.00
+43.37%
Bt88.00
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

8 Oct 2026
PTT Exploration & Production (PTTEP TB): 3Q26 Net Profit To Decline qoq On Lower Sales And Oil Hedging Loss

28 Sept 2026
Delta (Thailand) (DELTA TB) : 3Q26 Results Preview: Earnings Expected To Improve qoq, Driven By Higher Sales And Margins

21 Oct 2026
Osotspa (OSP TB): 3Q26 Results Preview: Margins Expected To Remain Resilient
Our latest research

21 Oct 2026
Airports of Thailand (AOT TB): Expect Robust Earnings In 4QFY26, Supported By PSC

21 Oct 2026
Bangkok Bank (BBL TB): 3Q26: Results In Line With Consensus; Showing Clean Loan Portfolio
21 Oct 2026