Company Coverage
PTT Global Chemical (PTTGC TB): Olefins Business Outlook Remains Under Pressure From Persistent Oversupply
HOLD (Maintained)
Current price:
Target price:
Upside:
Bt39.20
Bt45.00
+13.80%
Analyst
Analyst
Highlights
- Management remains confident in achieving the targeted synergy value from the JVCo, with the deal expected to be completed by 2H27.
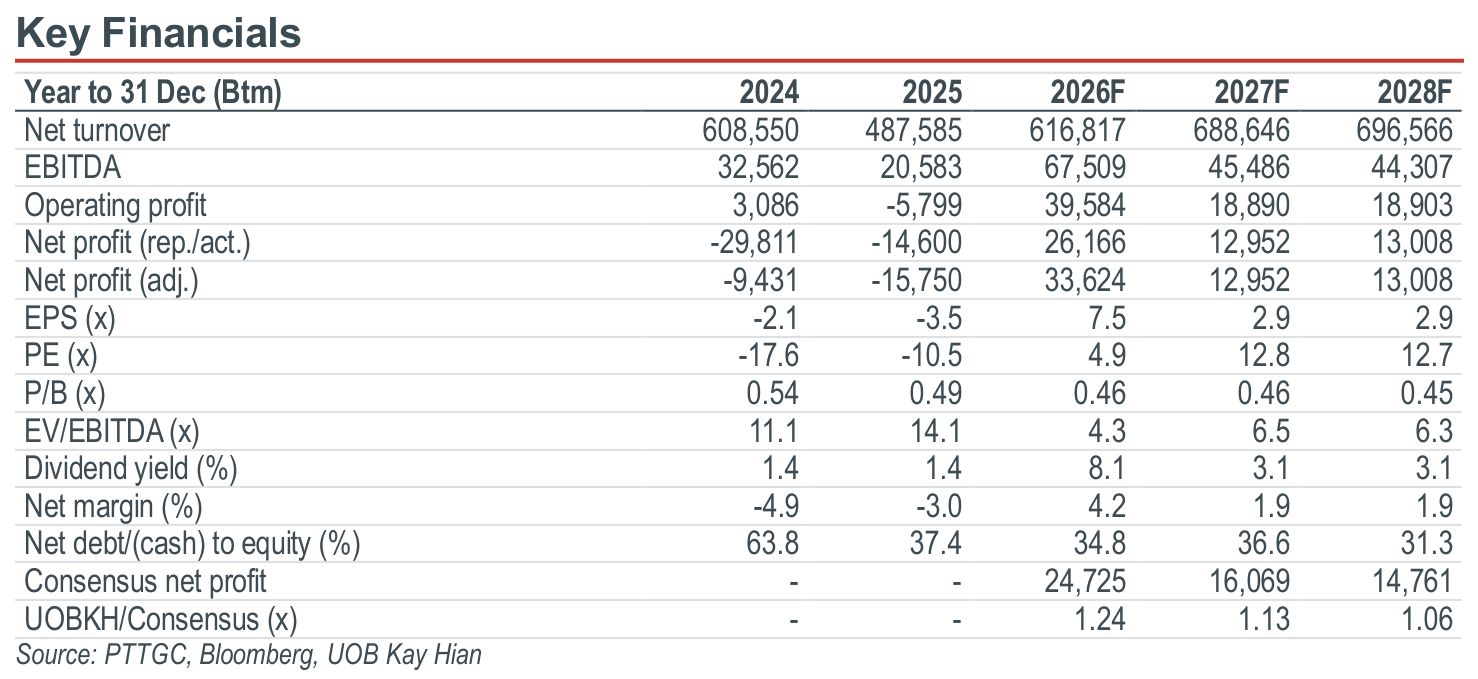
- We maintain a cautious and bearish outlook on the petrochemical business due to the persistent oversupply. Meanwhile, the GRM outlook is expected to improve, supported by seasonal demand and the upcoming maintenance season.
- Maintain HOLD with a target price of Bt45.00.
Analysis
- The tone during the meeting with PTT Global Chemical (PTTGC) was neutral.
- JVCo to strengthen long-term competitiveness. We see the JV between PTTGC and SCGC as a major step towards restructuring Thailand’s petrochemical industry. The transaction involves the integration of the two companies’ Thai olefins, polyolefins and downstream businesses, with a combined olefins capacity of 7.10m tonnes/year. The JV aims to enhance competitiveness through asset consolidation, cost reduction and economies of scale. PTTGC will hold a 56% majority stake and maintain control of the JVCo, which is expected to generate long-term synergies of US$150m-200m/year.
- Management highlighted three key synergy areas:
- Feedstock optimisation: Integrating the procurement of ethane, naphtha and LPG, while optimising the shared management of utilities, including power, steam and hydrogen.
- Portfolio optimisation: Coordinating polyethylene (PE) production schedules to reduce grade-switching costs and eliminate overlapping inventory.
- Cost optimisation: Strengthening bargaining power in the procurement of chemicals, catalysts and maintenance services through increased economies of scale.
- Feedstock optimisation: Integrating the procurement of ethane, naphtha and LPG, while optimising the shared management of utilities, including power, steam and hydrogen.
- The proximity of both companies' plants in Map Ta Phut is a key advantage, enabling practical integration of utilities and supply chains without requiring significant investment in new assets. In the longer term, PTTGC aims to increase its specialty product contribution to 30% by 2030, while greater feedstock flexibility should help reduce reliance on commodity petrochemicals.
- PTTGC expects the JVCo to be established by 2H27, with synergies starting to materialise from 2028 onwards. This will also include the US ethane import project, which has a planned capacity of 400,000 tonnes/year and COD targeted for 2029; this should enhance feedstock flexibility and reduce feedstock costs.
Highlights
- Management remains confident in achieving the targeted synergy value from the JVCo, with the deal expected to be completed by 2H27.
- We maintain a cautious and bearish outlook on the petrochemical business due to the persistent oversupply. Meanwhile, the GRM outlook is expected to improve, supported by seasonal demand and the upcoming maintenance season.
- Maintain HOLD with a target price of Bt45.00.
Analysis
- The tone during the meeting with PTT Global Chemical (PTTGC) was neutral.
- JVCo to strengthen long-term competitiveness. We see the JV between PTTGC and SCGC as a major step towards restructuring Thailand’s petrochemical industry. The transaction involves the integration of the two companies’ Thai olefins, polyolefins and downstream businesses, with a combined olefins capacity of 7.10m tonnes/year. The JV aims to enhance competitiveness through asset consolidation, cost reduction and economies of scale. PTTGC will hold a 56% majority stake and maintain control of the JVCo, which is expected to generate long-term synergies of US$150m-200m/year.
- Management highlighted three key synergy areas:
- Feedstock optimisation: Integrating the procurement of ethane, naphtha and LPG, while optimising the shared management of utilities, including power, steam and hydrogen.
- Portfolio optimisation: Coordinating polyethylene (PE) production schedules to reduce grade-switching costs and eliminate overlapping inventory.
- Cost optimisation: Strengthening bargaining power in the procurement of chemicals, catalysts and maintenance services through increased economies of scale.
- Feedstock optimisation: Integrating the procurement of ethane, naphtha and LPG, while optimising the shared management of utilities, including power, steam and hydrogen.
- The proximity of both companies' plants in Map Ta Phut is a key advantage, enabling practical integration of utilities and supply chains without requiring significant investment in new assets. In the longer term, PTTGC aims to increase its specialty product contribution to 30% by 2030, while greater feedstock flexibility should help reduce reliance on commodity petrochemicals.
- PTTGC expects the JVCo to be established by 2H27, with synergies starting to materialise from 2028 onwards. This will also include the US ethane import project, which has a planned capacity of 400,000 tonnes/year and COD targeted for 2029; this should enhance feedstock flexibility and reduce feedstock costs.
HOLD (Maintained)
Current price:
Target price:
Upside:
Bt39.20
Bt45.00
+13.80%
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

12 Nov 2026
PTT Global Chemical (PTTGC TB): 3Q26: Net Profit Lower qoq

26 Oct 2026
PTT Global Chemical (PTTGC TB): 3Q26 Earnings Expected To Decline qoq

19 Nov 2026
Berli Jucker (BJC TB): Strongly Positive Takeaways from Analyst Meeting
Our latest research

20 Nov 2026
Asset World Corporation (AWC TB): Outlook Remains Robust Throughout The High Travel Season

19 Nov 2026
PTT (PTT TB): Geopolitical Tightness Now, Supply Glut Ahead – PTT Ramps Up Global Trading
19 Nov 2026