Company Coverage
PTT Global Chemical (PTTGC TB): 3Q26: Net Profit Lower qoq
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt41.50
Bt45.00
+8.43%
Bt54.00
Analyst
Analyst
Highlights
- PTTGC reported a lower net profit qoq in 3Q26, but above our and consensus estimates, partly due to higher-than-expected stock gains. However, overall earnings remained weak due to lower market GRM and olefins spreads.
- Going forward, the petrochemical industry remains weak due to oversupply while the GRM outlook should improve on seasonality and the maintenance season.
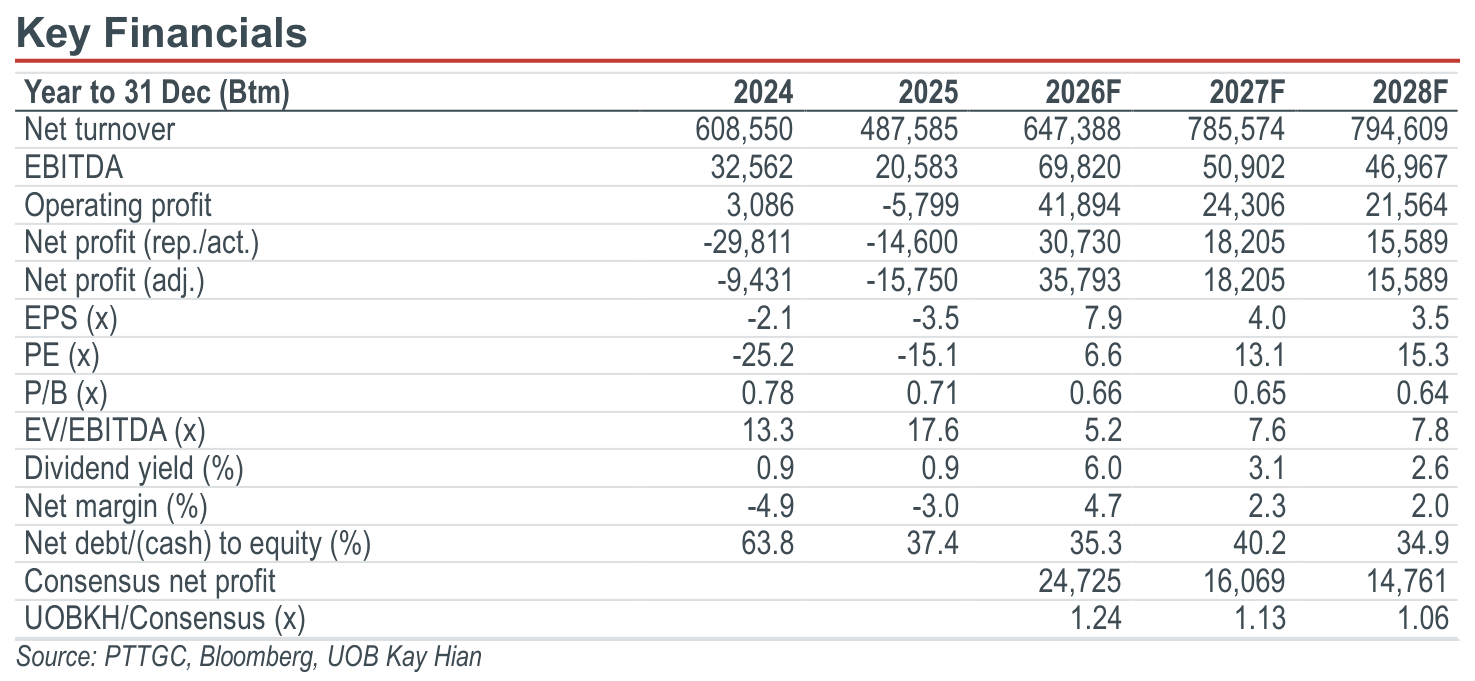
- Maintain HOLD with a target price of Bt45.00 (previously Bt54.00).
Analysis
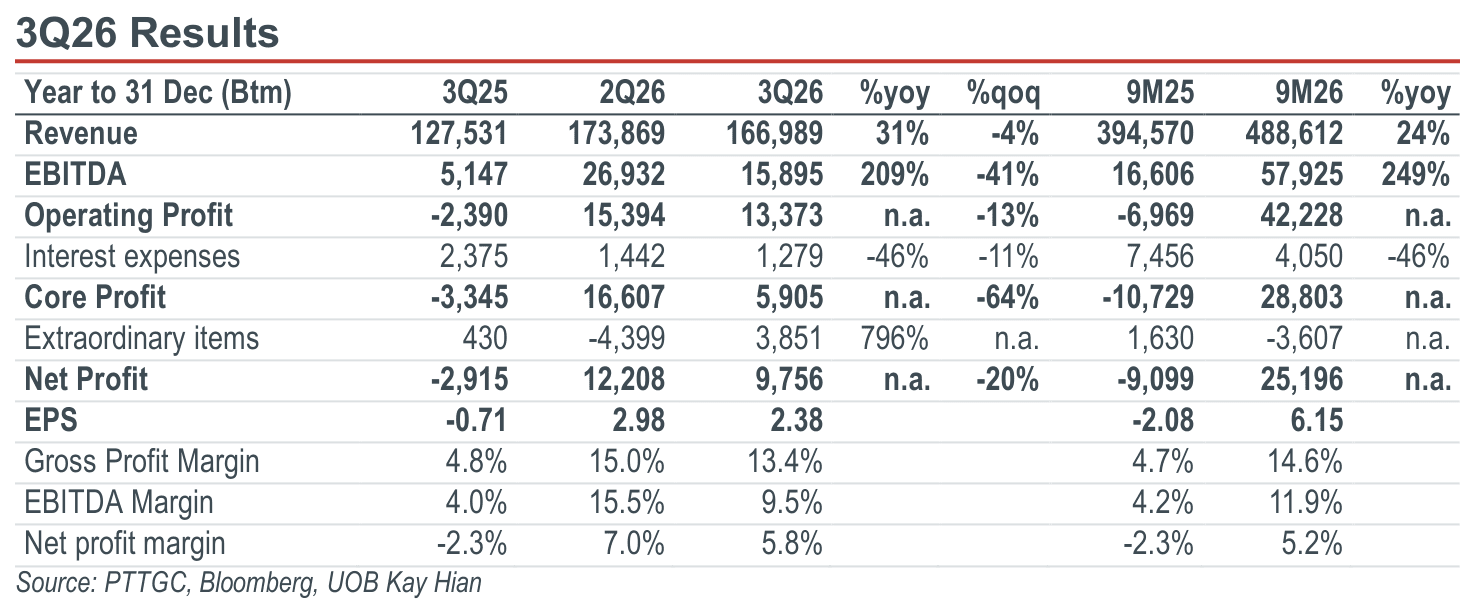
- 3Q26 net profit beat expectations. PTT Global Chemical (PTTGC) reported 3Q26 net profit of Bt9.76b, down 20% qoq but turning profitable from a net loss in 3Q25. The result was 8% above our estimate and 19% above consensus, partly due to higher-than-expected stock gains. Excluding extra gains, core profit was Bt5.9b, down 64% qoq.
- Core profit declined qoq on weaker olefins and refinery performance. The decline was mainly attributable to lower polyethylene (PE) product prices and spreads amid rising regional supply as producers gradually resumed operations, together with a lower market gross refinery margin (GRM). a) Weaker market GRM. Refinery EBITDA declined 13% qoq due to a weaker market GRM, which fell to US$14.30/bbl in 3Q26 (vs US$15.60/bbl in 2Q26). Earnings were further pressured by persistently high crude premiums amid ongoing uncertainty in the Middle East, as well as government intervention measures. These included the reduction in domestic diesel ex-refinery prices, which negatively impacted PTTGC by approximately Bt3.00b, equivalent to US$6.00/bbl in 3Q26 (vs US$4.00/bbl in 2Q26), and restrictions on fuel exports. Although the government eased the export restrictions to allow Jet A-1 exports to certain countries from the middle of the year, the measures continued to weigh on refinery performance.
Highlights
- PTTGC reported a lower net profit qoq in 3Q26, but above our and consensus estimates, partly due to higher-than-expected stock gains. However, overall earnings remained weak due to lower market GRM and olefins spreads.
- Going forward, the petrochemical industry remains weak due to oversupply while the GRM outlook should improve on seasonality and the maintenance season.
- Maintain HOLD with a target price of Bt45.00 (previously Bt54.00).
Analysis
- 3Q26 net profit beat expectations. PTT Global Chemical (PTTGC) reported 3Q26 net profit of Bt9.76b, down 20% qoq but turning profitable from a net loss in 3Q25. The result was 8% above our estimate and 19% above consensus, partly due to higher-than-expected stock gains. Excluding extra gains, core profit was Bt5.9b, down 64% qoq.
- Core profit declined qoq on weaker olefins and refinery performance. The decline was mainly attributable to lower polyethylene (PE) product prices and spreads amid rising regional supply as producers gradually resumed operations, together with a lower market gross refinery margin (GRM). a) Weaker market GRM. Refinery EBITDA declined 13% qoq due to a weaker market GRM, which fell to US$14.30/bbl in 3Q26 (vs US$15.60/bbl in 2Q26). Earnings were further pressured by persistently high crude premiums amid ongoing uncertainty in the Middle East, as well as government intervention measures. These included the reduction in domestic diesel ex-refinery prices, which negatively impacted PTTGC by approximately Bt3.00b, equivalent to US$6.00/bbl in 3Q26 (vs US$4.00/bbl in 2Q26), and restrictions on fuel exports. Although the government eased the export restrictions to allow Jet A-1 exports to certain countries from the middle of the year, the measures continued to weigh on refinery performance.
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt41.50
Bt45.00
+8.43%
Bt54.00
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

26 Oct 2026
PTT Global Chemical (PTTGC TB): 3Q26 Earnings Expected To Decline qoq

29 Oct 2026
Siam Cement (SCC TB): 3Q26: Earnings Miss Expectations As Chemical Business Records Losses

2 Nov 2026
PTT Exploration & Production (PTTEP TB) - 3Q26: Net Profit Below Expectations
Our latest research

13 Nov 2026
Asset World Corporation (AWC TB): 3Q26: Robust Results In Line

13 Nov 2026
Charoen Pokphand Foods (CPF TB): 3Q26: Earnings Beat On Higher Share Of Profit From China Swine Business Restructuring

13 Nov 2026