Company Coverage
PTT Exploration & Production (PTTEP TB) - 3Q26: Net Profit Below Expectations
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt165.00
Bt190.00
+15.15%
Bt170.00
Analyst
Analyst
Highlights
- Net profit came in below our and market consensus estimates, partly due to an impairment loss on Malaysia projects. Excluding exceptional items, 3Q26 core profit was flat qoq, in line with our estimate and 13% above market consensus.
- 3Q26 core profit was supported by lower unit costs, which more than offset the impact of lower ASP and sales volume.
- We expect core profit to remain strong in 4Q26, supported by higher oil prices.
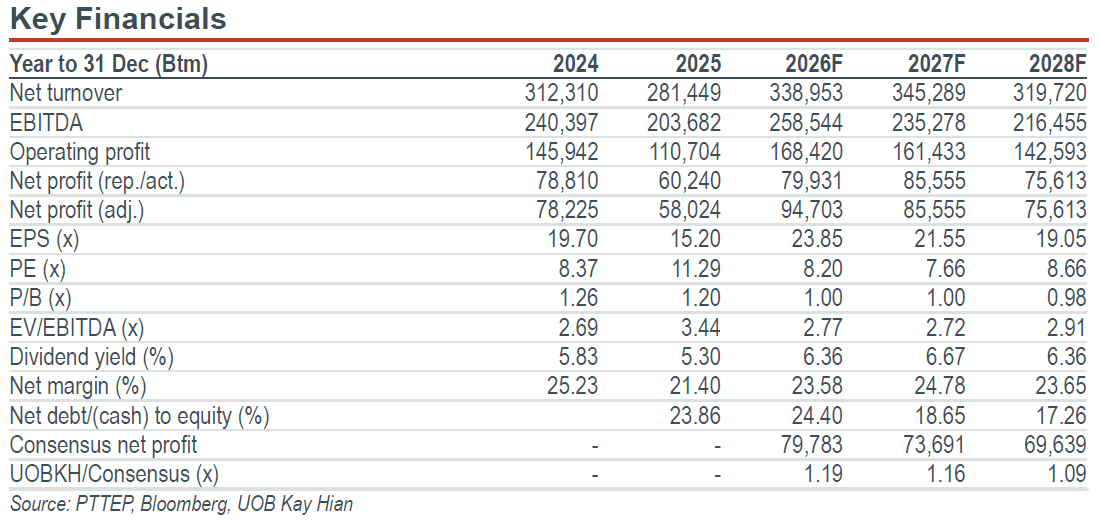
- Maintain BUY with a target price of Bt190.00 (previously: Bt170.00).
Analysis
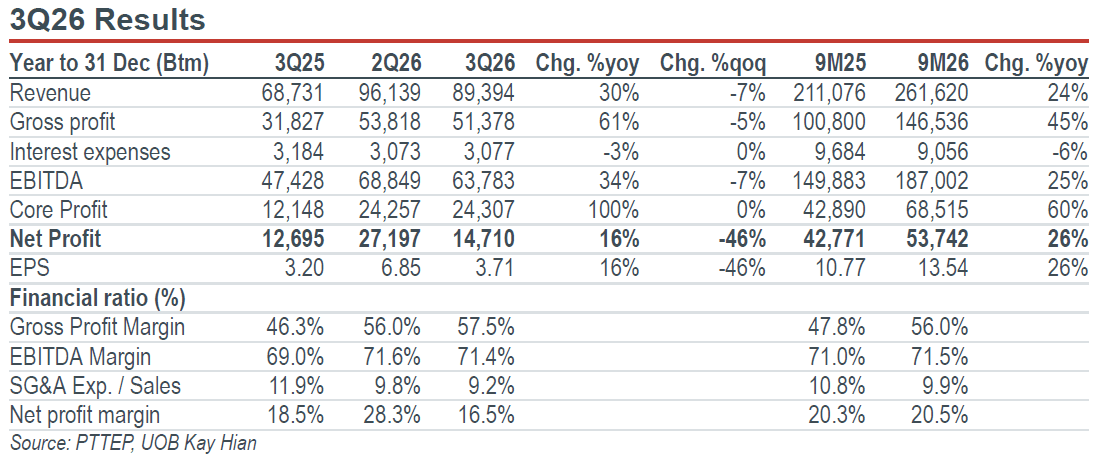
- 3Q26 net profit hit by impairment losses. PTT Exploration & Production (PTTEP) reported a 3Q26 net profit of Bt14.71b, down 46% qoq but up 16% yoy, missing our and market consensus estimates by 28% and 25%, respectively. The earnings shortfall was partly attributable to a Bt6.64b impairment loss on the Sabah K project. Excluding this impairment, an oil hedging loss of Bt1.68b and a forex loss of Bt1.28b, 3Q26 core profit stood at Bt24.31b, flat qoq but up 100% yoy. This is in line with our estimate and 13% above market consensus.
- 3Q26 core profit in line with expectations. The key factors supporting 3Q26 core profit were:
- Lower sales volume. Sales volume stood at 521,163 barrels of oil equivalent per day (BOED), down 9% qoq but up 2.1% yoy. The qoq decline was mainly due to lower natural gas production in the Gulf of Thailand following PTT's planned gas separation plant maintenance shutdowns. Lower sales contributions from Malaysia and Algeria also weighed on overall volume.
Highlights
- Net profit came in below our and market consensus estimates, partly due to an impairment loss on Malaysia projects. Excluding exceptional items, 3Q26 core profit was flat qoq, in line with our estimate and 13% above market consensus.
- 3Q26 core profit was supported by lower unit costs, which more than offset the impact of lower ASP and sales volume.
- We expect core profit to remain strong in 4Q26, supported by higher oil prices.
- Maintain BUY with a target price of Bt190.00 (previously: Bt170.00).
Analysis
- 3Q26 net profit hit by impairment losses. PTT Exploration & Production (PTTEP) reported a 3Q26 net profit of Bt14.71b, down 46% qoq but up 16% yoy, missing our and market consensus estimates by 28% and 25%, respectively. The earnings shortfall was partly attributable to a Bt6.64b impairment loss on the Sabah K project. Excluding this impairment, an oil hedging loss of Bt1.68b and a forex loss of Bt1.28b, 3Q26 core profit stood at Bt24.31b, flat qoq but up 100% yoy. This is in line with our estimate and 13% above market consensus.
- 3Q26 core profit in line with expectations. The key factors supporting 3Q26 core profit were:
- Lower sales volume. Sales volume stood at 521,163 barrels of oil equivalent per day (BOED), down 9% qoq but up 2.1% yoy. The qoq decline was mainly due to lower natural gas production in the Gulf of Thailand following PTT's planned gas separation plant maintenance shutdowns. Lower sales contributions from Malaysia and Algeria also weighed on overall volume.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt165.00
Bt190.00
+15.15%
Bt170.00
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at the this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

2 Nov 2026
Siam Global House (GLOBAL TB) - 3Q26: Earnings Beat Our And Consensus Estimates

8 Oct 2026
PTT Exploration & Production (PTTEP TB): 3Q26 Net Profit To Decline qoq On Lower Sales And Oil Hedging Loss

2 Nov 2026
i-Tail Corporation (ITC TB) - 3Q26: Earnings In Line; Positive On Industry Growth
Our latest research
2 Nov 2026
i-Tail Corporation (ITC TB) - 3Q26: Earnings In Line; Positive On Industry Growth
2 Nov 2026
Siam Global House (GLOBAL TB) - 3Q26: Earnings Beat Our And Consensus Estimates

2 Nov 2026