Company Coverage
Siam Global House (GLOBAL TB) - 3Q26: Earnings Beat Our And Consensus Estimates
BUY (Maintained)
Current price:
Target price:
Upside:
Bt7.15
Bt9.00
+25.9%
Analyst
Highlights
- GLOBAL reported 3Q26 net profit of Bt551m, spiking 40% yoy and 10% above our and consensus estimates due to a higher-than-expected margin.
- House brand sales accelerated, reflecting consumers’ increasing preference for lower-priced products amid a sluggish economic recovery.
- Maintain BUY with a target price of Bt9.00, based on 2027F PE of 17x.
Analysis
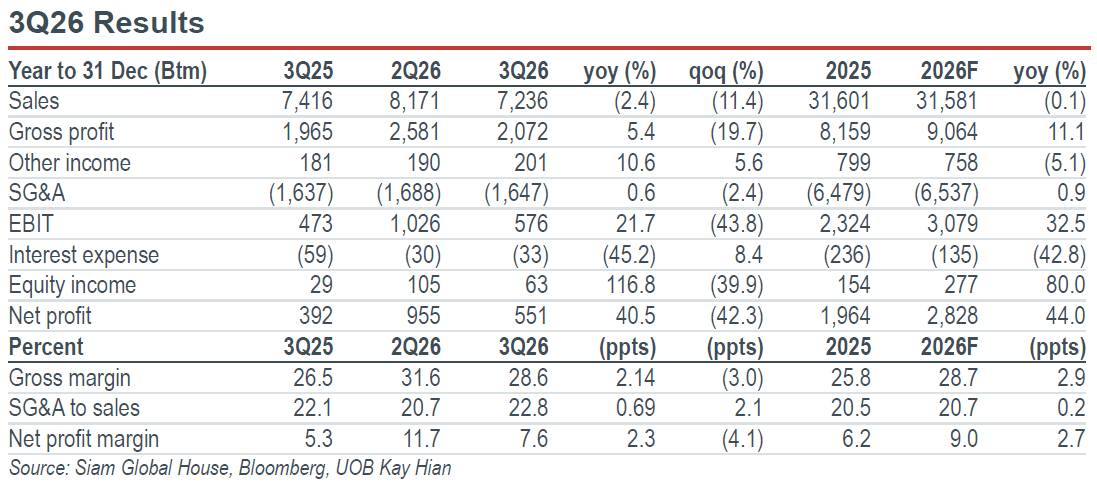
- Results beat. Siam Global Houses (GLOBAL) reported 3Q26 net profit of Bt551m (+40% yoy, -42% qoq), 10% above our and consensus estimates, due to a higher-than-expected gross profit margin. House brand sales accelerated despite a decline in overall sales, reflecting consumers’ increasing preference for lower-priced house brand products amid a limited economic recovery. This drove a stronger-than-expected improvement in gross profit margin.
- 3Q26 operating highlights. a) Revenue declined 2% yoy, with SSSG of -6.94% yoy; b) gross profit margin increased by 214bps yoy to 28.6% (vs our estimate of 27.8%), driven by a higher house brand sales contribution of 29.0% (3Q25: 27.0%; 2Q26: 27.5%); c) other income increased 11% yoy, supported by Bt19m in insurance claim proceeds; d) SG&A-to-sales increased by 69 bps yoy to 22.8%, mainly due to higher depreciation expenses following store expansion; e) interest expenses remained flat qoq; and f) share of profit from investments increased by 117% yoy, supported by improved operations in Myanmar.
Highlights
- GLOBAL reported 3Q26 net profit of Bt551m, spiking 40% yoy and 10% above our and consensus estimates due to a higher-than-expected margin.
- House brand sales accelerated, reflecting consumers’ increasing preference for lower-priced products amid a sluggish economic recovery.
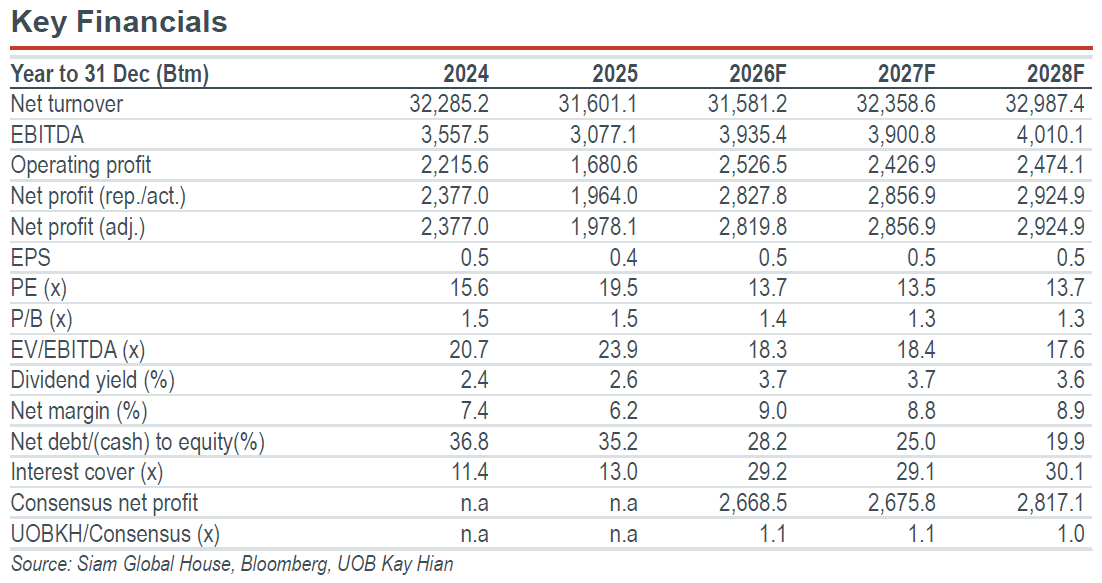
- Maintain BUY with a target price of Bt9.00, based on 2027F PE of 17x.
Analysis
- Results beat. Siam Global Houses (GLOBAL) reported 3Q26 net profit of Bt551m (+40% yoy, -42% qoq), 10% above our and consensus estimates, due to a higher-than-expected gross profit margin. House brand sales accelerated despite a decline in overall sales, reflecting consumers’ increasing preference for lower-priced house brand products amid a limited economic recovery. This drove a stronger-than-expected improvement in gross profit margin.
- 3Q26 operating highlights. a) Revenue declined 2% yoy, with SSSG of -6.94% yoy; b) gross profit margin increased by 214bps yoy to 28.6% (vs our estimate of 27.8%), driven by a higher house brand sales contribution of 29.0% (3Q25: 27.0%; 2Q26: 27.5%); c) other income increased 11% yoy, supported by Bt19m in insurance claim proceeds; d) SG&A-to-sales increased by 69 bps yoy to 22.8%, mainly due to higher depreciation expenses following store expansion; e) interest expenses remained flat qoq; and f) share of profit from investments increased by 117% yoy, supported by improved operations in Myanmar.
BUY (Maintained)
Current price:
Target price:
Upside:
Bt7.15
Bt9.00
+25.9%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at the following link: https://research-api.uobkayhian.com/assets/disclaimer/df64a6ea-7980-447c-ae9e-fd19b93257dc, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

2 Nov 2026
PTT Exploration & Production (PTTEP TB) - 3Q26: Net Profit Below Expectations

29 Oct 2026
Siam Cement (SCC TB): 3Q26: Earnings Miss Expectations As Chemical Business Records Losses

19 Oct 2026
COM7 (COM7 TB): Earnings Expected To Surge In 3Q26
Our latest research

2 Nov 2026
i-Tail Corporation (ITC TB) - 3Q26: Earnings In Line; Positive On Industry Growth
2 Nov 2026
PTT Exploration & Production (PTTEP TB) - 3Q26: Net Profit Below Expectations

2 Nov 2026