

Company Coverage
Siam Cement (SCC TB): 3Q26: Earnings Miss Expectations As Chemical Business Records Losses
HOLD (Maintained)
Current price:
Target price:
Upside:
Bt278.00
Bt278.00
+0.00%
Analyst
Highlights
- 3Q26 earnings missed our and consensus estimates by 27% and 42%, respectively, due to a steeper-than-expected decline in chemical sales, while CBM and packaging earnings weakened due to seasonal factors.
- We expect 4Q26 net profit to recover qoq, supported by dividend income and a recovery in the chemical business.
- Maintain HOLD. Target price: Bt278.00.
Analysis
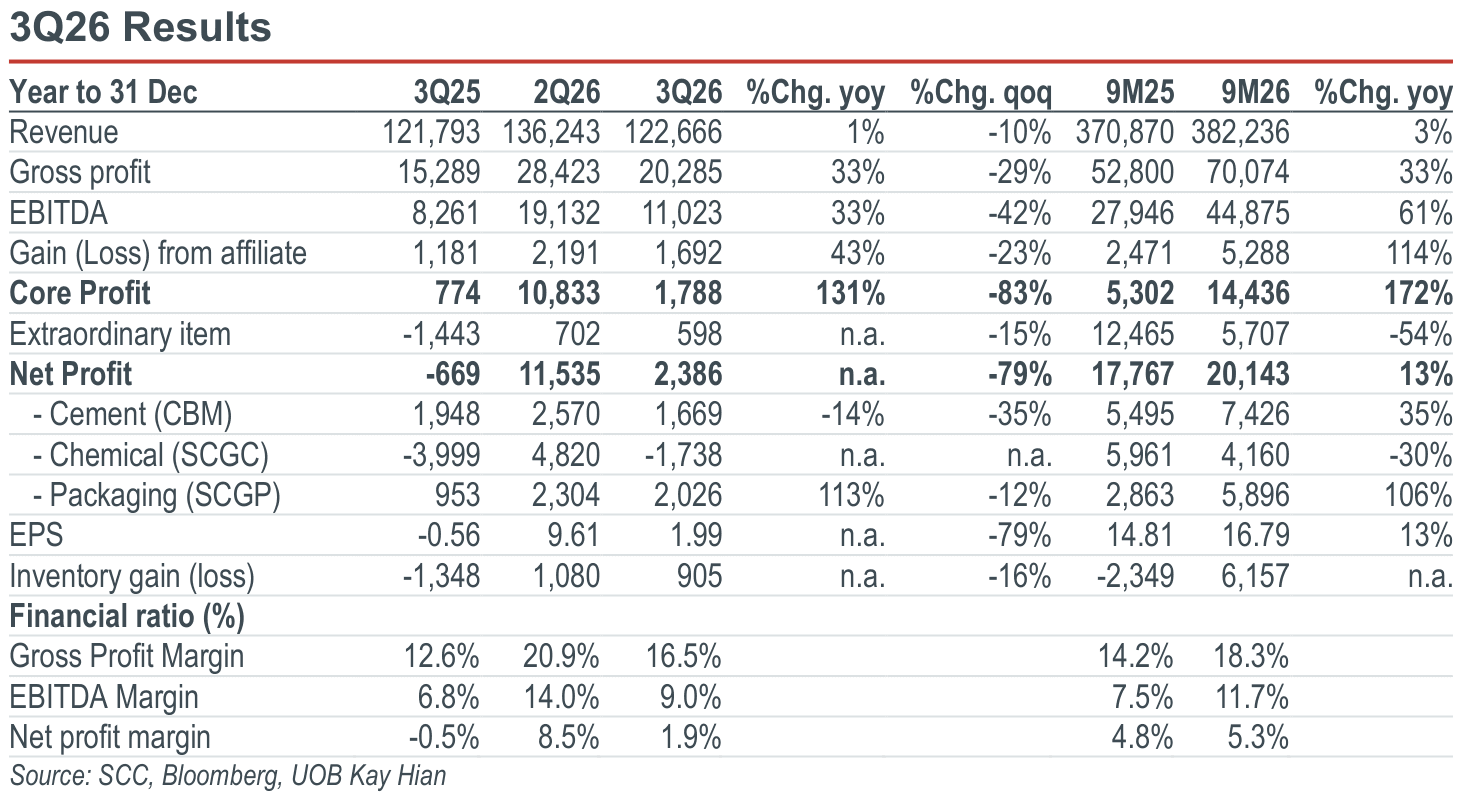
- 3Q26 net profit missed our and consensus estimates. Siam Cement (SCC) SCC reported 3Q26 net profit of Bt2.39b, down 79% qoq but recovering from a net loss of Bt669m in 3Q25. Earnings were 27% below our estimate and 42% below market consensus, partly due to lower-than-expected earnings from the chemical business. SCC recorded extra gains of Bt598m in 3Q26, comprising a stock gain of Bt905m, offset by restructuring expenses in the cement building material (CBM) business. Excluding these items, core profit stood at Bt1.79b, down 83% qoq but up 131% yoy. 9M26 net profit accounted for 74% of our 2026 forecast.
- Seasonal weakness in cement sales. CBM net profit was Bt1.67b in 3Q26, down 35% qoq and 14% yoy, partly due to lower cement sales volume during the rainy season and higher energy costs, in line with coal prices (ICI3), which rose 6% qoq and 66% yoy to US$96/tonne.
Highlights
- 3Q26 earnings missed our and consensus estimates by 27% and 42%, respectively, due to a steeper-than-expected decline in chemical sales, while CBM and packaging earnings weakened due to seasonal factors.
- We expect 4Q26 net profit to recover qoq, supported by dividend income and a recovery in the chemical business.
- Maintain HOLD. Target price: Bt278.00.
Analysis
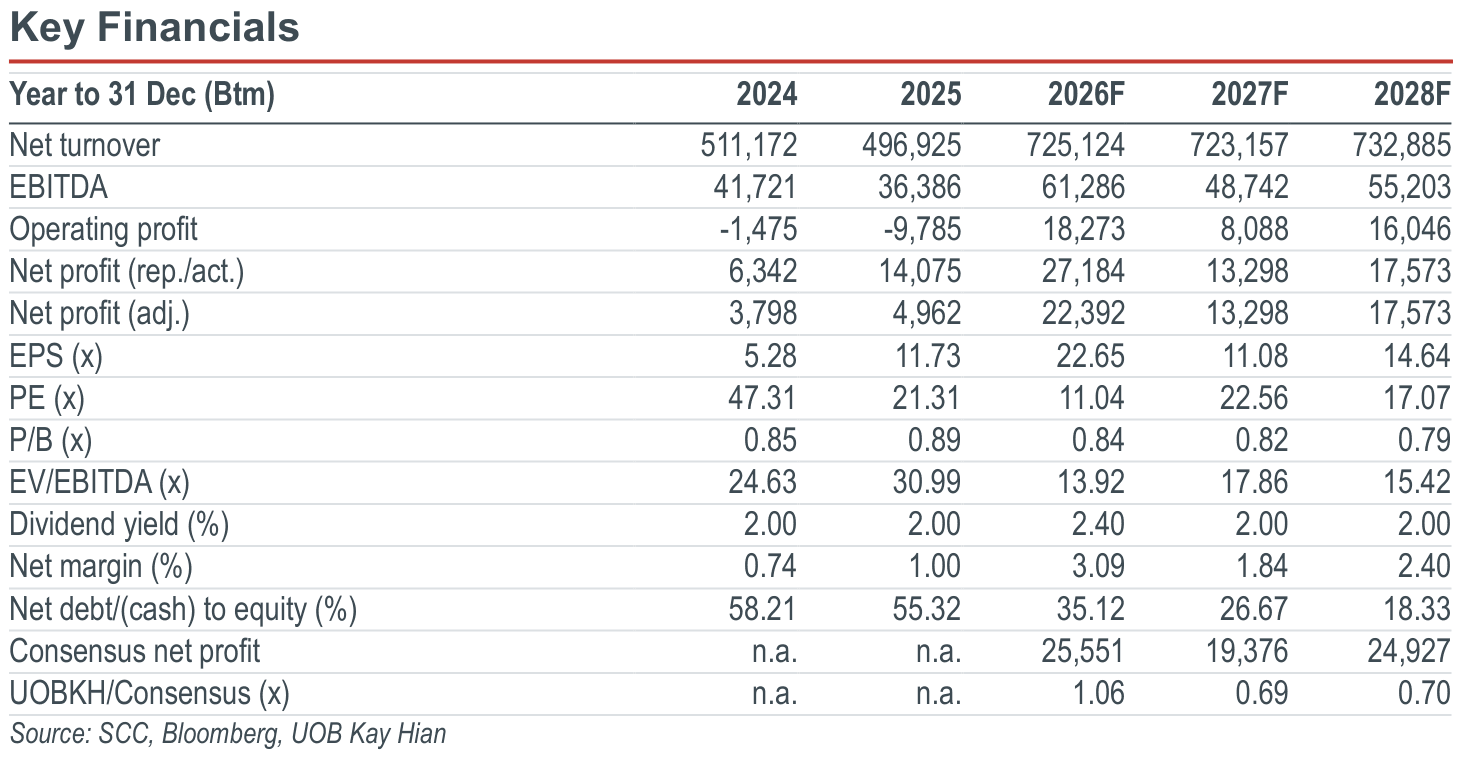
- 3Q26 net profit missed our and consensus estimates. Siam Cement (SCC) SCC reported 3Q26 net profit of Bt2.39b, down 79% qoq but recovering from a net loss of Bt669m in 3Q25. Earnings were 27% below our estimate and 42% below market consensus, partly due to lower-than-expected earnings from the chemical business. SCC recorded extra gains of Bt598m in 3Q26, comprising a stock gain of Bt905m, offset by restructuring expenses in the cement building material (CBM) business. Excluding these items, core profit stood at Bt1.79b, down 83% qoq but up 131% yoy. 9M26 net profit accounted for 74% of our 2026 forecast.
- Seasonal weakness in cement sales. CBM net profit was Bt1.67b in 3Q26, down 35% qoq and 14% yoy, partly due to lower cement sales volume during the rainy season and higher energy costs, in line with coal prices (ICI3), which rose 6% qoq and 66% yoy to US$96/tonne.
HOLD (Maintained)
Current price:
Target price:
Upside:
Bt278.00
Bt278.00
+0.00%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


