

Company Coverage
Delta (Thailand) (DELTA TB): Guides For Strong Sales Growth; Slower Gross Margin Recovery Outlook Through 1Q27 Presents Opportunity To Accumulate
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt232.00
Bt280.00
20.7%
Bt300.00
Analyst
Analyst
Sirithat Prasertwuti
Highlights
- DELTA reported a net profit of Bt7.76b (+4% yoy, +28% qoq), 14% below our and market expectations, as continued inventory provisions limited margin recovery.
- Management guided for very strong sales growth in 4Q26, supported by orders that were not fully delivered during 2Q-3Q26 and no sign of demand slowdown for the next one year.
- Inventory provision risks are expected to persist throughout 1Q27, but we remain bullish on sales growth over the next 12 months.
- Maintain BUY with a target price of Bt280.00, as we view the valuation overhang from inventory provision uncertainties as an accumulation opportunity, with the current valuation already reflecting weaker margins and a slower margin recovery pace.
Analysis
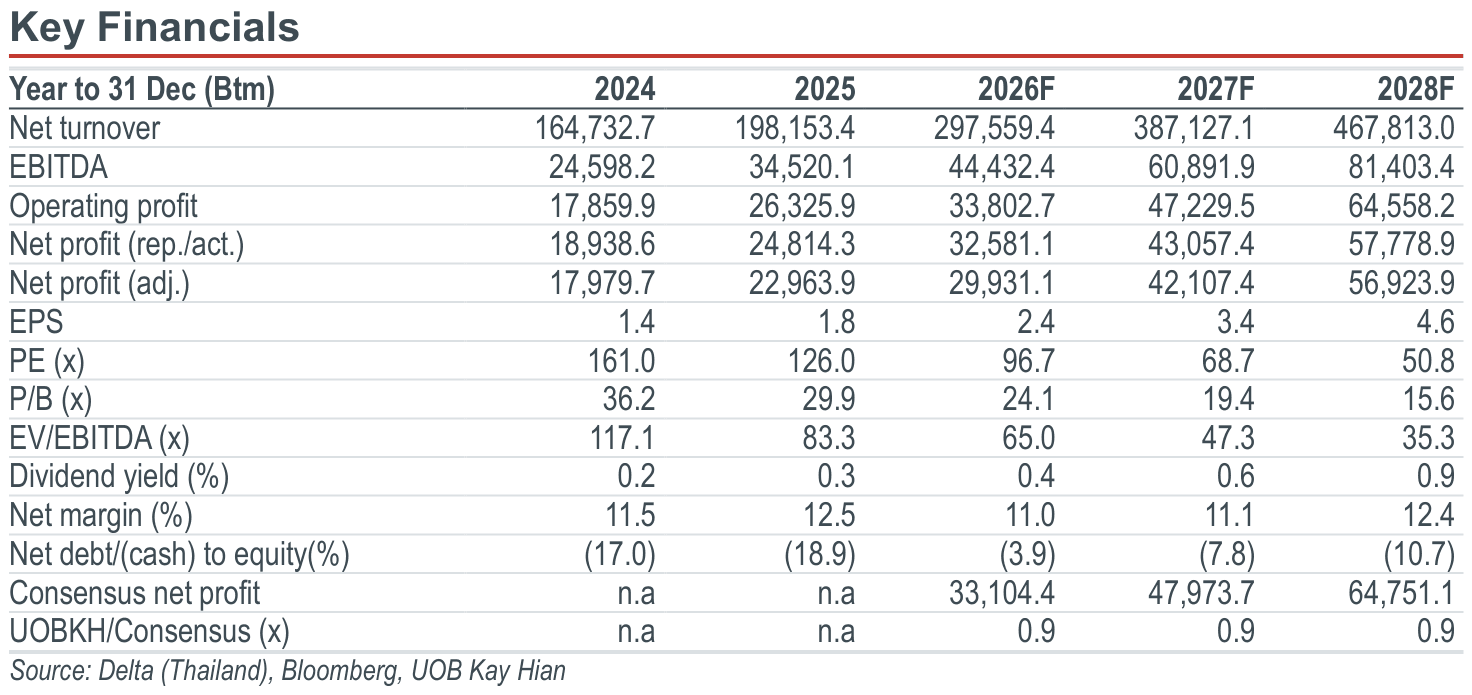
- 3Q26 results: Despite strong sales momentum, earnings missed expectations as another inventory provision limited gross margin recovery. On 27 Oct 26, Delta (Thailand) (DELTA) reported a net profit of Bt7.76b (+4% yoy, +28% qoq), 14% below our estimate and consensus forecasts. Despite strong sales of Bt75.8b (+42% yoy, +16% qoq), broadly in line with expectations, the earnings miss was mainly due to weaker-than-expected gross margin recovery from continued inventory provision. Gross margin came in at 27.3% (vs 26.8% in 2Q26), below expectations of 29.1-29.5%, mainly due to: a) elevated inventory provisions amid persistent raw material shortages and inventory build-up to support existing customer orders, and b) short-term customer demand fluctuations causing inventories to remain at DELTA’s hubs for more than 90 days. As a result, inventory provisions had a negative impact of 2.62ppts on gross margin in 3Q26 (vs 0.55ppts/2.05ppts in 1Q26/2Q26).
- Tone was slightly positive: Strong 4Q26 sales momentum expected, but we remain neutral on the pace of gross margin recovery. We are slightly positive on DELTA as management maintained its aggressive 40:60 sales split guidance between 1H26 and 2H26, implying roughly 50% qoq sales growth in 4Q26 (or potential net profit of Bt10b-11b). The expected sales peak is supported by strong demand for power supplies and data centre infrastructure solutions, along with orders from 2Q-3Q26 that have yet to be fully delivered. However, we forecast 4Q26 sales at Bt95.2b (+65% yoy, +26% qoq), reflecting short-term demand fluctuations among major cloud customers amid persistent raw material shortages. Our forecast implies a 42:58 sales split, leaving room for potential upside if management's guidance materialises, while maintaining a cautious gross margin outlook.
Highlights
- DELTA reported a net profit of Bt7.76b (+4% yoy, +28% qoq), 14% below our and market expectations, as continued inventory provisions limited margin recovery.
- Management guided for very strong sales growth in 4Q26, supported by orders that were not fully delivered during 2Q-3Q26 and no sign of demand slowdown for the next one year.
- Inventory provision risks are expected to persist throughout 1Q27, but we remain bullish on sales growth over the next 12 months.
- Maintain BUY with a target price of Bt280.00, as we view the valuation overhang from inventory provision uncertainties as an accumulation opportunity, with the current valuation already reflecting weaker margins and a slower margin recovery pace.
Analysis
- 3Q26 results: Despite strong sales momentum, earnings missed expectations as another inventory provision limited gross margin recovery. On 27 Oct 26, Delta (Thailand) (DELTA) reported a net profit of Bt7.76b (+4% yoy, +28% qoq), 14% below our estimate and consensus forecasts. Despite strong sales of Bt75.8b (+42% yoy, +16% qoq), broadly in line with expectations, the earnings miss was mainly due to weaker-than-expected gross margin recovery from continued inventory provision. Gross margin came in at 27.3% (vs 26.8% in 2Q26), below expectations of 29.1-29.5%, mainly due to: a) elevated inventory provisions amid persistent raw material shortages and inventory build-up to support existing customer orders, and b) short-term customer demand fluctuations causing inventories to remain at DELTA’s hubs for more than 90 days. As a result, inventory provisions had a negative impact of 2.62ppts on gross margin in 3Q26 (vs 0.55ppts/2.05ppts in 1Q26/2Q26).
- Tone was slightly positive: Strong 4Q26 sales momentum expected, but we remain neutral on the pace of gross margin recovery. We are slightly positive on DELTA as management maintained its aggressive 40:60 sales split guidance between 1H26 and 2H26, implying roughly 50% qoq sales growth in 4Q26 (or potential net profit of Bt10b-11b). The expected sales peak is supported by strong demand for power supplies and data centre infrastructure solutions, along with orders from 2Q-3Q26 that have yet to be fully delivered. However, we forecast 4Q26 sales at Bt95.2b (+65% yoy, +26% qoq), reflecting short-term demand fluctuations among major cloud customers amid persistent raw material shortages. Our forecast implies a 42:58 sales split, leaving room for potential upside if management's guidance materialises, while maintaining a cautious gross margin outlook.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt232.00
Bt280.00
20.7%
Bt300.00
Analyst
Analyst
Sirithat Prasertwuti
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

28 Oct 2026
SCG Packaging (SCGP TB): Focus On Selling Price Increases To Mitigate Cost Pressures

28 Sept 2026
Delta (Thailand) (DELTA TB) : 3Q26 Results Preview: Earnings Expected To Improve qoq, Driven By Higher Sales And Margins

21 Oct 2026
Osotspa (OSP TB): 3Q26 Results Preview: Margins Expected To Remain Resilient
Our latest research

29 Oct 2026
Siam Cement (SCC TB): 3Q26: Earnings Miss Expectations As Chemical Business Records Losses

29 Oct 2026
WHA Corporation (WHA TB): 3Q26 Preview: Improved Land Transfer Mix To Drive Earnings Growth

28 Oct 2026