Company Coverage
Berli Jucker (BJC TB): Strongly Positive Takeaways from Analyst Meeting
BUY (Maintained)
Current price:
Target price:
Upside:
Bt20.30
Bt24.50
20.69%
Analyst
Highlights
- We attended BJC’s analyst meeting on 18 November and came away with a more bullish view.
- Management expects the business restructuring to generate Bt1.3b in cost savings.
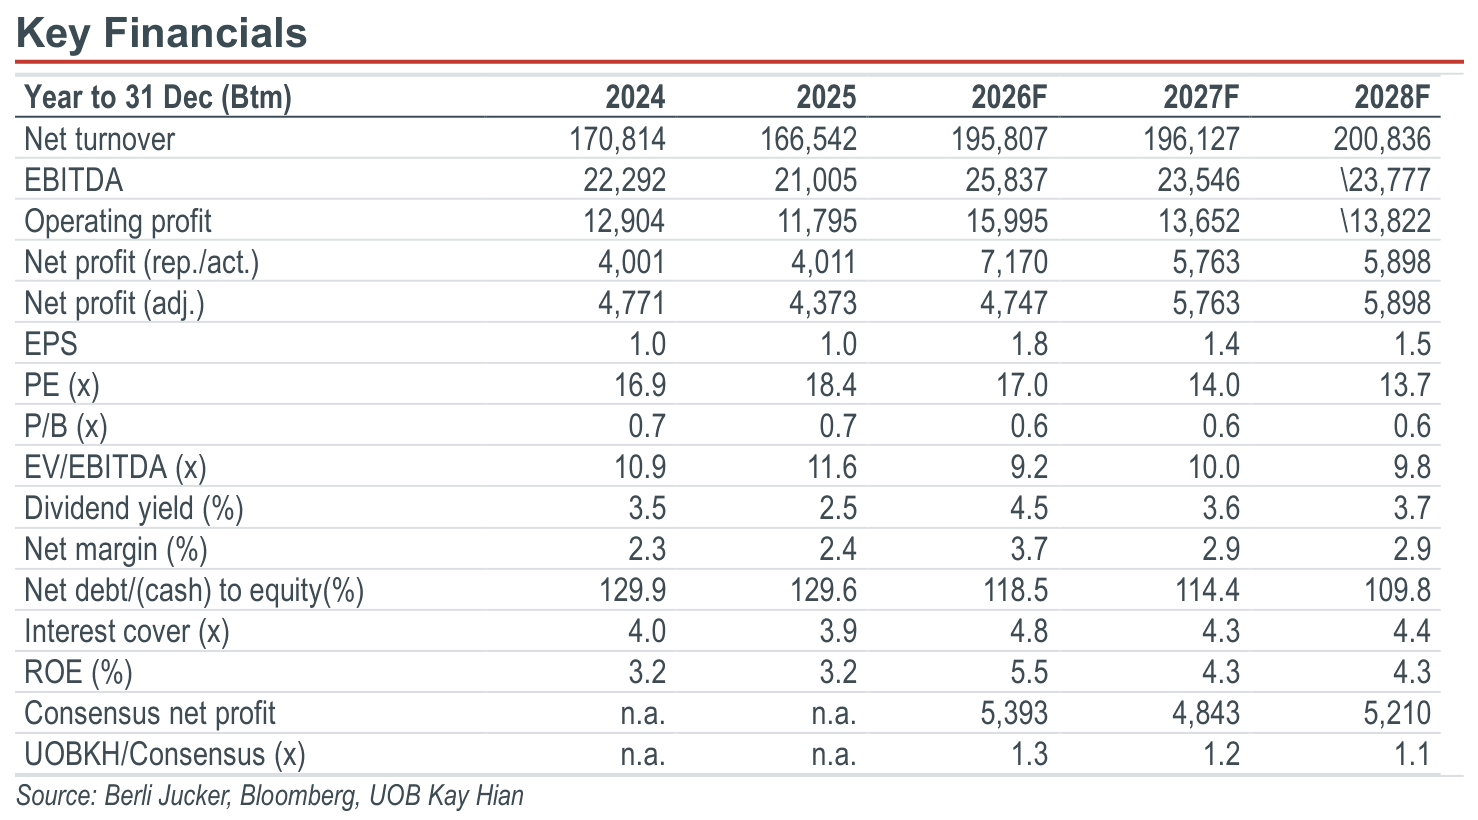
- If the company achieves its cost-saving target as guided, 2027 earnings could be 11% above our forecast, implying a Bt2.60 upside to our target price.
- Maintain BUY with a target price of Bt24.50, based on 2027F PE of 17x.
Analysis
- Restructuring to generate over Bt1b in annual savings. Management indicated that the business restructuring is expected to generate more than Bt1.3b in cost savings, which will provide meaningful support to its 2027 earnings growth.
- Workforce restructuring. Berli Jucker (BJC) restructured its workforce during 2H26, resulting in one-off severance expenses after tax of Bt98m in 3Q26 and Bt176m in 4Q26. However, the restructuring is expected to generate significant cost savings going forward. Management targets annual cost savings of around Bt1.37b before tax, comprising Bt500m from head office operations and Bt800m from store employees. After tax, the savings are estimated at Bt1.1b, equivalent to 23% of our 2026 net profit forecast. We view this as a key earnings growth driver from 2027 onwards.
- Closure of loss-making stores to improve profitability. BJC plans to close 12 loss-making large-format stores, of which eight have already been closed. The closures are expected to generate EBITDA savings of around Bt170m. Management also plans to review its store portfolio and consider further closures of underperforming stores to improve overall profitability. The company expects to book the gain from asset disposals of Bt900m– 1,000m from the sale of non-performing assets.
- Workforce restructuring. Berli Jucker (BJC) restructured its workforce during 2H26, resulting in one-off severance expenses after tax of Bt98m in 3Q26 and Bt176m in 4Q26. However, the restructuring is expected to generate significant cost savings going forward. Management targets annual cost savings of around Bt1.37b before tax, comprising Bt500m from head office operations and Bt800m from store employees. After tax, the savings are estimated at Bt1.1b, equivalent to 23% of our 2026 net profit forecast. We view this as a key earnings growth driver from 2027 onwards.
- The recovery of Big C. Big C's qtd SSSG stands at 3-4% yoy (up 1–2% yoy in Oct 26 and +5% in Nov 26), driven by fresh food, dry food and homeline categories. Meanwhile, managements target annual gross margin improvement of 15–20bps in the longer term. Key initiatives include better promotional management, increasing direct sourcing to improve purchasing costs and reducing obsolete inventory. These initiatives should help improve sales mix and inventory efficiency, supporting a gradual gross margin improvement over the medium term.
Highlights
- We attended BJC’s analyst meeting on 18 November and came away with a more bullish view.
- Management expects the business restructuring to generate Bt1.3b in cost savings.
- If the company achieves its cost-saving target as guided, 2027 earnings could be 11% above our forecast, implying a Bt2.60 upside to our target price.
- Maintain BUY with a target price of Bt24.50, based on 2027F PE of 17x.
Analysis
- Restructuring to generate over Bt1b in annual savings. Management indicated that the business restructuring is expected to generate more than Bt1.3b in cost savings, which will provide meaningful support to its 2027 earnings growth.
- Workforce restructuring. Berli Jucker (BJC) restructured its workforce during 2H26, resulting in one-off severance expenses after tax of Bt98m in 3Q26 and Bt176m in 4Q26. However, the restructuring is expected to generate significant cost savings going forward. Management targets annual cost savings of around Bt1.37b before tax, comprising Bt500m from head office operations and Bt800m from store employees. After tax, the savings are estimated at Bt1.1b, equivalent to 23% of our 2026 net profit forecast. We view this as a key earnings growth driver from 2027 onwards.
- Closure of loss-making stores to improve profitability. BJC plans to close 12 loss-making large-format stores, of which eight have already been closed. The closures are expected to generate EBITDA savings of around Bt170m. Management also plans to review its store portfolio and consider further closures of underperforming stores to improve overall profitability. The company expects to book the gain from asset disposals of Bt900m– 1,000m from the sale of non-performing assets.
- Workforce restructuring. Berli Jucker (BJC) restructured its workforce during 2H26, resulting in one-off severance expenses after tax of Bt98m in 3Q26 and Bt176m in 4Q26. However, the restructuring is expected to generate significant cost savings going forward. Management targets annual cost savings of around Bt1.37b before tax, comprising Bt500m from head office operations and Bt800m from store employees. After tax, the savings are estimated at Bt1.1b, equivalent to 23% of our 2026 net profit forecast. We view this as a key earnings growth driver from 2027 onwards.
- The recovery of Big C. Big C's qtd SSSG stands at 3-4% yoy (up 1–2% yoy in Oct 26 and +5% in Nov 26), driven by fresh food, dry food and homeline categories. Meanwhile, managements target annual gross margin improvement of 15–20bps in the longer term. Key initiatives include better promotional management, increasing direct sourcing to improve purchasing costs and reducing obsolete inventory. These initiatives should help improve sales mix and inventory efficiency, supporting a gradual gross margin improvement over the medium term.
BUY (Maintained)
Current price:
Target price:
Upside:
Bt20.30
Bt24.50
20.69%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

13 Nov 2026
Charoen Pokphand Foods (CPF TB): 3Q26: Earnings Beat On Higher Share Of Profit From China Swine Business Restructuring

2 Nov 2026
Siam Global House (GLOBAL TB) - 3Q26: Earnings Beat Our And Consensus Estimates

22 Oct 2026
Betagro (BTG TB): 3Q26 Results Preview: Thai Livestock Producers Are Winners
Our latest research

20 Nov 2026
Asset World Corporation (AWC TB): Outlook Remains Robust Throughout The High Travel Season

19 Nov 2026
PTT (PTT TB): Geopolitical Tightness Now, Supply Glut Ahead – PTT Ramps Up Global Trading

19 Nov 2026