Company Coverage
Bumrungrad Hospital (BH TB): Positive On 4Q26 Earnings Outlook
BUY (Maintained)
Current price:
Target price:
Upside:
Bt193.00
Bt240.00
+24.4%
Analyst
Analyst
Nonpawit Vathanadachakul
Highlights
- The meeting tone was positive, as management updated that it is seeing a continuous flow of Middle East patients coming to BH.
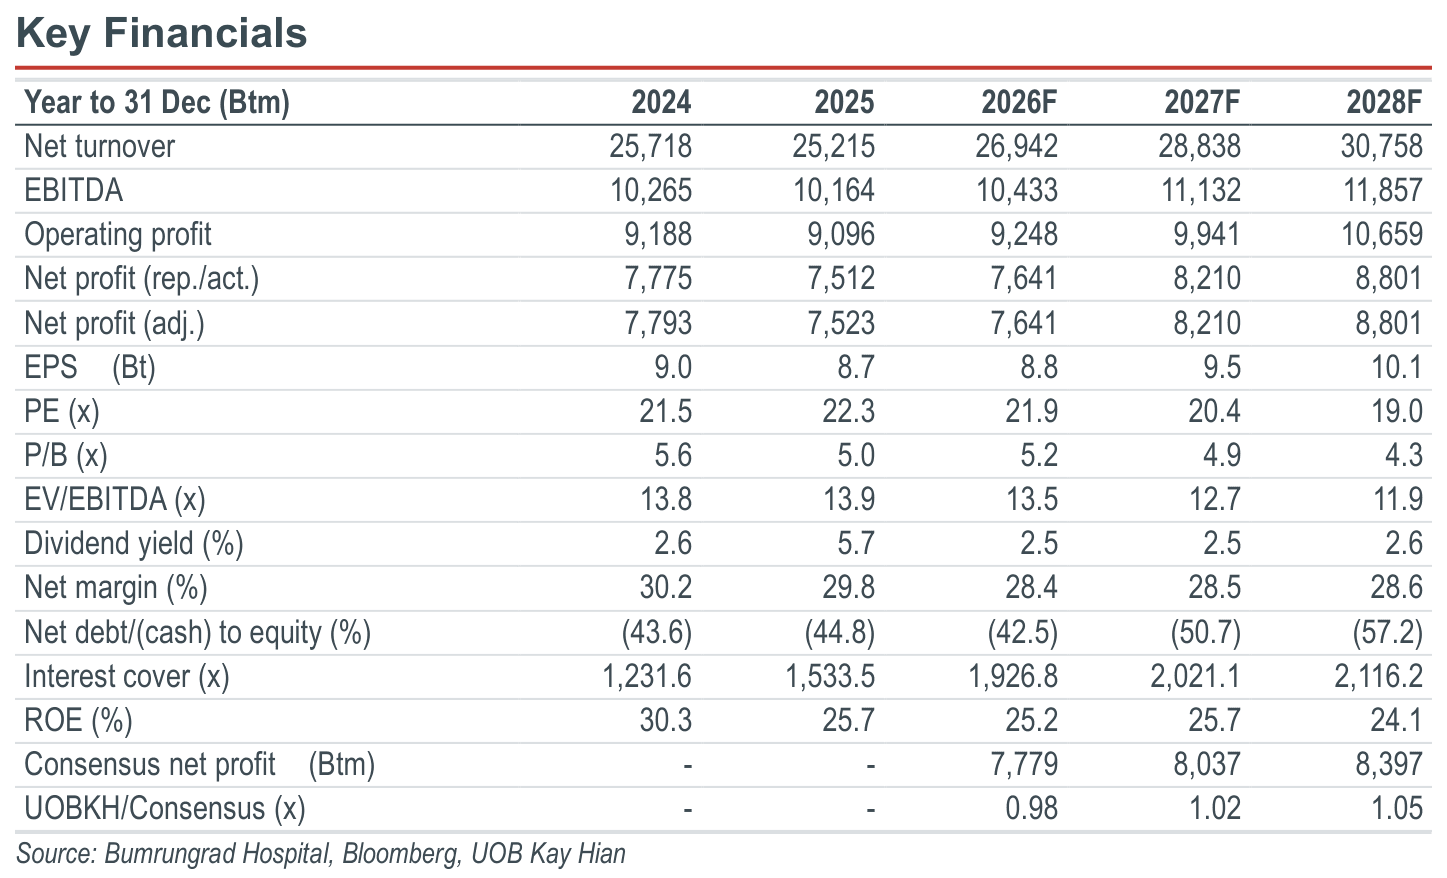
- Despite the flattish top-line guidance in 4Q26, we still expect BH to show yoy earnings growth driven by cost savings measures and tax benefits.
- We remain optimistic on BH and maintain it as one of our top picks as the Middle East patient inflow remains strong and the earnings outlook is positive in 4Q26. Maintain BUY with a target price of Bt240.00.
Analysis
- Positive tone from the analyst meeting. We attended Bumrungrad Hospital’s (BH) analyst meeting to review its 3Q26 results and the tone was positive.
- We still expect earnings growth in 4Q26 despite the flattish revenue guidance. Management guided for yoy flattish growth in 4Q26 top-line, as the long-staying Qatar patients have returned to their country in 3Q26. This group of Qatar patients has stayed since 3Q25 and could not return to their country, but after the Qatar embassy escorted their return, BH’s Qatar revenue dropped by 11.2% yoy in 3Q26. This has caused a high base effect for 4Q26 onwards. We see this as a typical normalisation of revenue rather than a systematic change in the demand of Qatar patients. If there is no further escalation in the Middle East situation, we still expect BH to show yoy earnings growth. The key drivers will be the strict cost saving measures and tax benefit from The Board of Investment of Thailand (BOI) of around Bt29m from the robotic pharmacy project in 4Q26. Hence, we remain positive on BH’s earnings outlook.
- Strong inflow of Middle East patients continues. Despite the return of the long-staying Qatar patients, the momentum of Middle East patient arrivals continues to be positive. In terms of volume, in 3Q26, BH saw a 32% qoq hike in Middle East inpatient admissions and a 67.7% qoq surge in Middle East outpatient visits. Even the volume of Qatar patients is also up qoq in 3Q26 from new visits and referrals. There are no conflicts with the embassy and BH still views Qatar as a growth market. BH still targets Middle East revenue to show yoy growth in 2027. In fact, the number of Middle East arrivals in Oct 26 continues to show yoy growth, which is a positive indicator for the healthcare industry. We also expect this strong inflow of Middle East arrivals to continue throughout 4Q26.
Highlights
- The meeting tone was positive, as management updated that it is seeing a continuous flow of Middle East patients coming to BH.
- Despite the flattish top-line guidance in 4Q26, we still expect BH to show yoy earnings growth driven by cost savings measures and tax benefits.
- We remain optimistic on BH and maintain it as one of our top picks as the Middle East patient inflow remains strong and the earnings outlook is positive in 4Q26. Maintain BUY with a target price of Bt240.00.
Analysis
- Positive tone from the analyst meeting. We attended Bumrungrad Hospital’s (BH) analyst meeting to review its 3Q26 results and the tone was positive.
- We still expect earnings growth in 4Q26 despite the flattish revenue guidance. Management guided for yoy flattish growth in 4Q26 top-line, as the long-staying Qatar patients have returned to their country in 3Q26. This group of Qatar patients has stayed since 3Q25 and could not return to their country, but after the Qatar embassy escorted their return, BH’s Qatar revenue dropped by 11.2% yoy in 3Q26. This has caused a high base effect for 4Q26 onwards. We see this as a typical normalisation of revenue rather than a systematic change in the demand of Qatar patients. If there is no further escalation in the Middle East situation, we still expect BH to show yoy earnings growth. The key drivers will be the strict cost saving measures and tax benefit from The Board of Investment of Thailand (BOI) of around Bt29m from the robotic pharmacy project in 4Q26. Hence, we remain positive on BH’s earnings outlook.
- Strong inflow of Middle East patients continues. Despite the return of the long-staying Qatar patients, the momentum of Middle East patient arrivals continues to be positive. In terms of volume, in 3Q26, BH saw a 32% qoq hike in Middle East inpatient admissions and a 67.7% qoq surge in Middle East outpatient visits. Even the volume of Qatar patients is also up qoq in 3Q26 from new visits and referrals. There are no conflicts with the embassy and BH still views Qatar as a growth market. BH still targets Middle East revenue to show yoy growth in 2027. In fact, the number of Middle East arrivals in Oct 26 continues to show yoy growth, which is a positive indicator for the healthcare industry. We also expect this strong inflow of Middle East arrivals to continue throughout 4Q26.
BUY (Maintained)
Current price:
Target price:
Upside:
Bt193.00
Bt240.00
+24.4%
Analyst
Analyst
Nonpawit Vathanadachakul
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

19 Oct 2026
Bumrungrad Hospital (BH TB): Robust Growth Expected In 3Q26

27 Oct 2026
Praram 9 Hospital (PR9 TB): Expect A Record High Net Profit In 3Q26

19 Oct 2026
Bangkok Dusit Medical Services (BDMS TB): Expect Strong 3Q26 Earnings, Supported By Thai Patients
Our latest research

20 Nov 2026
Asset World Corporation (AWC TB): Outlook Remains Robust Throughout The High Travel Season

19 Nov 2026
PTT (PTT TB): Geopolitical Tightness Now, Supply Glut Ahead – PTT Ramps Up Global Trading

19 Nov 2026