Company Coverage
Dohome (DOHOME TB) : 3Q26: Results In Line; 4Q26 Outlook Turns More Positive
BUY (Maintained)
Current price:
Target price:
Upside:
Bt3.50
Bt4.50
10.29%
Analyst
Highlights
DOHOME reported a 3Q26 net profit of Bt112m, up by 10% yoy but down by 63% qoq, in line with our expectations but 9% below consensus estimates.
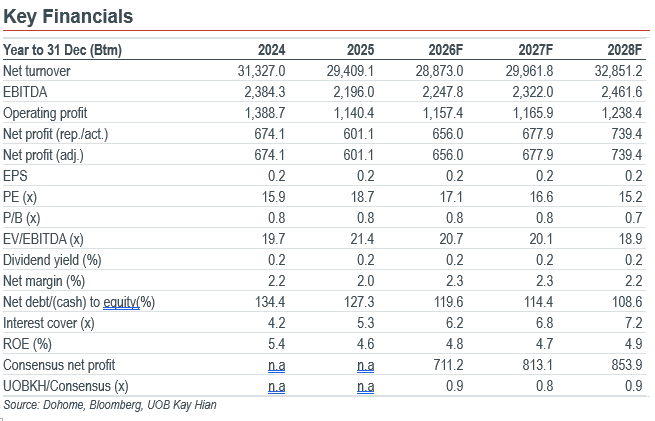
We are more positive on its 4Q26 outlook and preliminarily expect double-digit yoy earnings growth, supported by positive SSSG and gross margin improvement.
Maintain BUY with a target price of Bt4.50.
Analysis
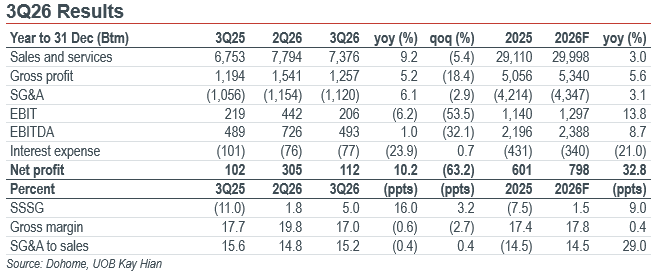
Results in line. Dohome (DOHOME) reported a 3Q26 net profit of Bt112m, up by 10% yoy but down by 63% qoq, in line with our expectations but 9% below consensus estimates. 9M26 earnings accounted for 84% of our full-year forecast (vs 9M25: 84%).
Key statistics. 3Q26 sales increased by 9.2% yoy, driven by 5.9% yoy increase in SSSG, particularly in the B2B segment, while the B2C segment saw a slight drop. Gross margin decreased 65bps yoy to 17.0% (3Q25: 17.7%, 2Q26: 19.8%), pressured by the lower steel gross margin and higher B2B sales contribution. SG&A-to-sales declined 22bps yoy, reflecting effective cost control amid rising diesel prices. Interest expenses also declined 24% yoy and was flat qoq, driven by debt repayment and lower policy rates.
Highlights
DOHOME reported a 3Q26 net profit of Bt112m, up by 10% yoy but down by 63% qoq, in line with our expectations but 9% below consensus estimates.
We are more positive on its 4Q26 outlook and preliminarily expect double-digit yoy earnings growth, supported by positive SSSG and gross margin improvement.
Maintain BUY with a target price of Bt4.50.
Analysis
Results in line. Dohome (DOHOME) reported a 3Q26 net profit of Bt112m, up by 10% yoy but down by 63% qoq, in line with our expectations but 9% below consensus estimates. 9M26 earnings accounted for 84% of our full-year forecast (vs 9M25: 84%).
Key statistics. 3Q26 sales increased by 9.2% yoy, driven by 5.9% yoy increase in SSSG, particularly in the B2B segment, while the B2C segment saw a slight drop. Gross margin decreased 65bps yoy to 17.0% (3Q25: 17.7%, 2Q26: 19.8%), pressured by the lower steel gross margin and higher B2B sales contribution. SG&A-to-sales declined 22bps yoy, reflecting effective cost control amid rising diesel prices. Interest expenses also declined 24% yoy and was flat qoq, driven by debt repayment and lower policy rates.
BUY (Maintained)
Current price:
Target price:
Upside:
Bt3.50
Bt4.50
10.29%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

10 Nov 2026
Central Pattana (CPN TB): 3Q26: Results In Line; Rental Business Drives Growth

2 Nov 2026
i-Tail Corporation (ITC TB) - 3Q26: Earnings In Line; Positive On Industry Growth

28 Oct 2026
SCG Packaging (SCGP TB): Focus On Selling Price Increases To Mitigate Cost Pressures
Our latest research
10 Nov 2026
Central Pattana (CPN TB): 3Q26: Results In Line; Rental Business Drives Growth

10 Nov 2026
Indorama Ventures (IVL TB) : 3Q26: Earnings Recovery To Gain Momentum In 2027

10 Nov 2026