Company Coverage
Indorama Ventures (IVL TB) : 3Q26: Earnings Recovery To Gain Momentum In 2027
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt22.30
Bt28.00
20.7%
Bt27.00
Analyst
Highlights
IVL reported 3Q26 net profit of Bt2.2b, turning around from a Bt818m loss in 3Q25 but down 64% qoq. Core profit was Bt2.4b, reversing a Bt386m loss in 3Q25 but down 73% yoy. 9M26 net profit was Bt5.3b, compared with a loss of Bt2.7b in 9M25.
We expect additional cost savings, a gradual recovery in fibres and EPL consolidation in 1Q27.
Maintain BUY with a target price of Bt28.00.
Analysis
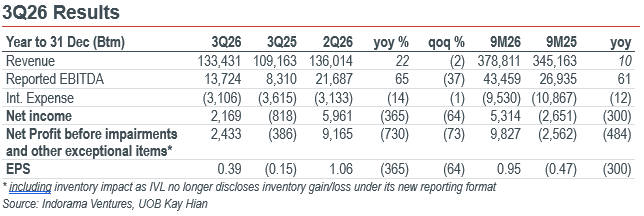
3Q26 earnings recovered yoy but slowed qoq. Indorama Ventures (IVL) reported 3Q26 net profit of Bt2.2b, turning around from a Bt818m loss in 3Q25 but down 64% qoq (no consensus forecast for 3Q26). According to IVL’s MD&A, core profit was Bt2.4b, reversing a Bt386m loss in 3Q25 but down 73% qoq. 9M26 net profit came in at Bt5.3b, compared with a loss of Bt2.7b in 9M25.
Key earnings driver in 3Q26. The lower qoq core profit came from seasonal factors and a weaker Integrated PET spread. Asia integrated PET spreads declined 37% qoq to US$176/t from US$279/t in 2Q26, due to higher energy costs in Europe, while the fibre business EBITDA was down by 52% qoq to Bt924m. However, the stronger yoy recovery was driven by better MEG/MTBE spreads, improved operating reliability and structural cost reductions. IVL’s interest expenses are still down 14% yoy and 1% qoq to Bt3.1b, supporting management's deleveraging strategy. We believe 3Q26 provides a reasonable reference point for 2027 earnings, supported by further cost savings, EPL consolidation and a potential recovery in fibres.
Highlights
IVL reported 3Q26 net profit of Bt2.2b, turning around from a Bt818m loss in 3Q25 but down 64% qoq. Core profit was Bt2.4b, reversing a Bt386m loss in 3Q25 but down 73% yoy. 9M26 net profit was Bt5.3b, compared with a loss of Bt2.7b in 9M25.
We expect additional cost savings, a gradual recovery in fibres and EPL consolidation in 1Q27.
Maintain BUY with a target price of Bt28.00.
Analysis
3Q26 earnings recovered yoy but slowed qoq. Indorama Ventures (IVL) reported 3Q26 net profit of Bt2.2b, turning around from a Bt818m loss in 3Q25 but down 64% qoq (no consensus forecast for 3Q26). According to IVL’s MD&A, core profit was Bt2.4b, reversing a Bt386m loss in 3Q25 but down 73% qoq. 9M26 net profit came in at Bt5.3b, compared with a loss of Bt2.7b in 9M25.
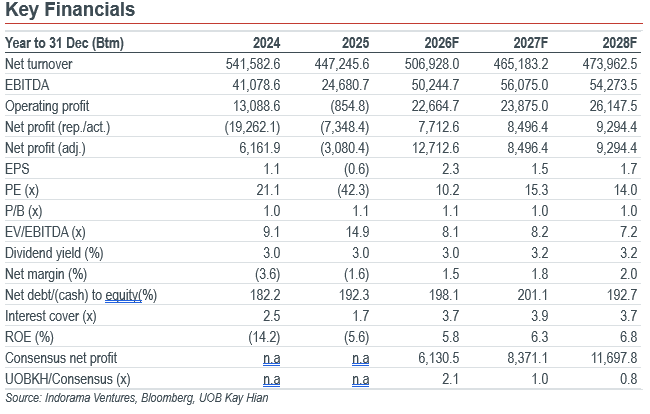
Key earnings driver in 3Q26. The lower qoq core profit came from seasonal factors and a weaker Integrated PET spread. Asia integrated PET spreads declined 37% qoq to US$176/t from US$279/t in 2Q26, due to higher energy costs in Europe, while the fibre business EBITDA was down by 52% qoq to Bt924m. However, the stronger yoy recovery was driven by better MEG/MTBE spreads, improved operating reliability and structural cost reductions. IVL’s interest expenses are still down 14% yoy and 1% qoq to Bt3.1b, supporting management's deleveraging strategy. We believe 3Q26 provides a reasonable reference point for 2027 earnings, supported by further cost savings, EPL consolidation and a potential recovery in fibres.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt22.30
Bt28.00
20.7%
Bt27.00
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

10 Nov 2026
IRPC (IRPC TB) : 3Q26: Upgrade To BUY Following A Share Price Correction

9 Nov 2026
CP Axtra (CPAXT TB): 3Q26: Earnings Trough; Store Closures to Boost Profit
10 Nov 2026
Dohome (DOHOME TB) : 3Q26: Results In Line; 4Q26 Outlook Turns More Positive
Our latest research

10 Nov 2026
Central Pattana (CPN TB): 3Q26: Results In Line; Rental Business Drives Growth
10 Nov 2026
IRPC (IRPC TB) : 3Q26: Upgrade To BUY Following A Share Price Correction
10 Nov 2026