Company Coverage
CP Axtra (CPAXT TB): 3Q26: Earnings Trough; Store Closures to Boost Profit
BUY (Upgraded)
Current price:
Target price:
Upside:
Bt14.30
Bt17.00
18.9%
Analyst
Highlights
Upgrade to BUY, with a higher target price of Bt17.00 (from Bt14.50).
CPAXT reported a 3Q26 net loss of Bt563m. Excluding one-off expenses, core profit came in at Bt1.65b, down 11% yoy but above our expectation by 7%.
Management guided that the closure of 673 loss-making stores could reduce retail revenue by 6%, but save Bt400m–500m in quarterly EBIT.
3Q26 marks an earnings trough, with a recovery in 4Q26 driven by the closure of non-performing stores and a low base in 4Q25.
Analysis
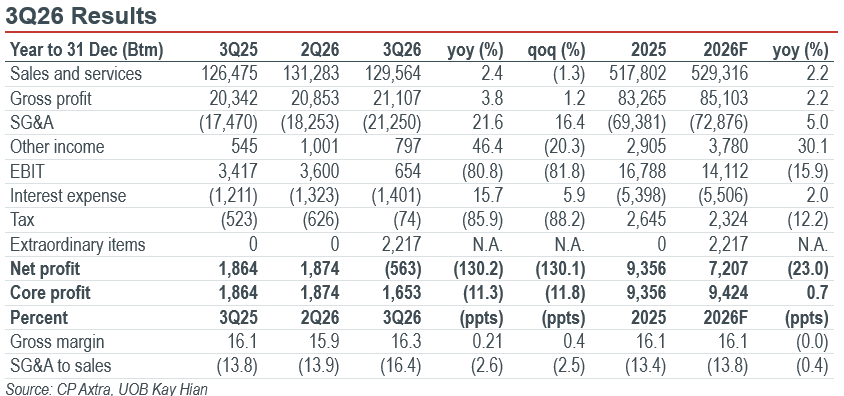
Results in line. CP Axtra (CPAXT) reported 3Q26 net loss of Bt563m. Excluding one-off expenses, core profit came in at Bt1.65b, down 11% yoy and 12% qoq. This exceeded our expectation by 7% due to higher-than-expected other income following an increase in data monetisation income. One-off items in 3Q26 before tax totalled Bt2,736m. These include: a) Bt100m loss from the closure of one Makro Cambodia store, b) Bt600m loss from the write-off of outdated assets of software and IT devices, c) Bt42m in acquisition-related expenses for The Food Purveyor (TFP), d) Bt100m from the restructuring of Lotus’ headquarters, and e) Bt1,894m loss from the closure of 673 Lotus’ Go Fresh stores, including asset write-offs, closure costs and employee expenses.
Highlights
Upgrade to BUY, with a higher target price of Bt17.00 (from Bt14.50).
CPAXT reported a 3Q26 net loss of Bt563m. Excluding one-off expenses, core profit came in at Bt1.65b, down 11% yoy but above our expectation by 7%.
Management guided that the closure of 673 loss-making stores could reduce retail revenue by 6%, but save Bt400m–500m in quarterly EBIT.
3Q26 marks an earnings trough, with a recovery in 4Q26 driven by the closure of non-performing stores and a low base in 4Q25.
Analysis
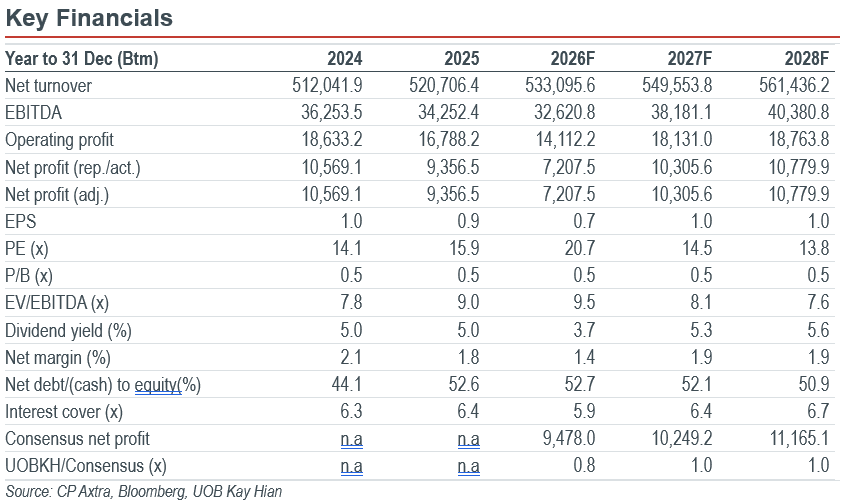
Results in line. CP Axtra (CPAXT) reported 3Q26 net loss of Bt563m. Excluding one-off expenses, core profit came in at Bt1.65b, down 11% yoy and 12% qoq. This exceeded our expectation by 7% due to higher-than-expected other income following an increase in data monetisation income. One-off items in 3Q26 before tax totalled Bt2,736m. These include: a) Bt100m loss from the closure of one Makro Cambodia store, b) Bt600m loss from the write-off of outdated assets of software and IT devices, c) Bt42m in acquisition-related expenses for The Food Purveyor (TFP), d) Bt100m from the restructuring of Lotus’ headquarters, and e) Bt1,894m loss from the closure of 673 Lotus’ Go Fresh stores, including asset write-offs, closure costs and employee expenses.
BUY (Upgraded)
Current price:
Target price:
Upside:
Bt14.30
Bt17.00
18.9%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

7 Oct 2026
CP Axtra (CPAXT TB): Weak 3Q26 Earnings But Expected To Bottom Out

7 Oct 2026
CP ALL (CPALL TB): 3Q26 Earnings Dragged By CP Axtra; Recovery Expected Ahead

25 Sept 2026
i-Tail Corporation (ITC TB): 3Q26 Results Preview: Sustained Strong Sales Growth Momentum
Our latest research

9 Nov 2026
KCE (Thailand) (KCE TB): Management Guides A Strong 4Q26-2027 Outlook; More Attractive Valuation Presents Trading Opportunities

9 Nov 2026
PTT Exploration & Production (PTTEP TB): LLB And Yadana Progress Supports PTTEP’s Long-term Growth Prospects

6 Nov 2026