Company Coverage
Bangchak Corporation (BCP TB) - 3Q26: Strong Core Operations, Weighed By Hedging Losses
BUY (Maintained)
Current price:
Target price:
Upside:
Bt43.50
Bt65.00
+49.4%
Analyst
Highlights
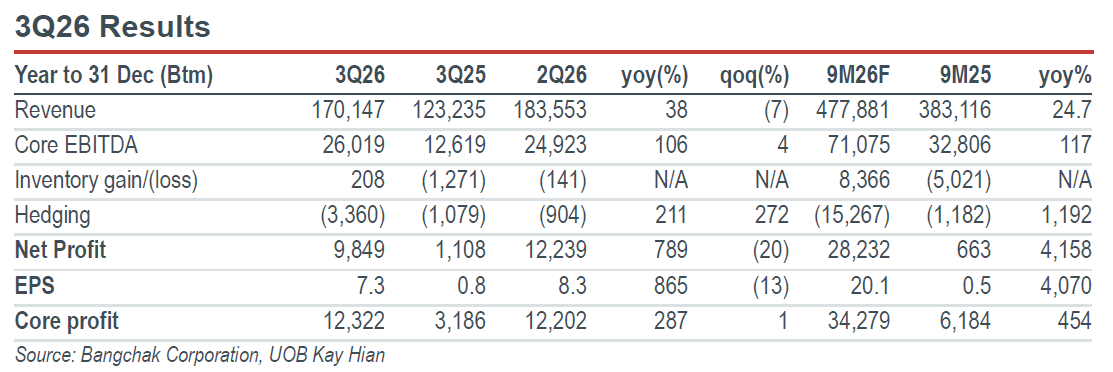
- BCP reported a 3Q26 net profit of Bt9.85b (+789% yoy, -20% qoq), while core profit rose 287% yoy and 1% qoq to Bt12.3b, in line with our forecasts.
- Basic GRM stayed elevated at US$17.36/bbl despite scheduled maintenance at Sriracha, while higher hedging losses weighed on reported earnings. SAF, biofuels and overseas marketing operations provided additional support.
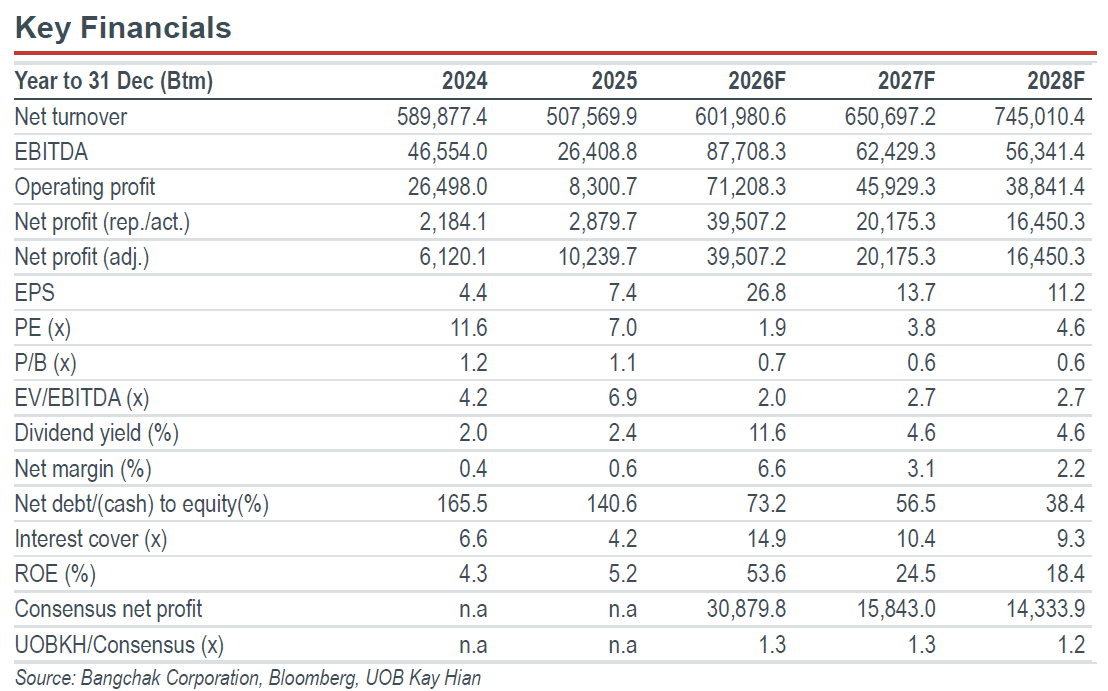
- We expect 2027 earnings to remain well above historical levels. Maintain BUY with a target price of Bt65.00.
Analysis
- Strong earnings as expected. Bangchak Corporation (BCP) reported 3Q26 net profit of Bt9.85b (-20% qoq, +789% yoy), with core profit (exclude impact from hedging gain/loss) of Bt12.3b (+287% yoy, +1% qoq ), in line with our forecast (see our results preview report on 26 Oct 26). 9M26 core profit reached Bt34.3b, accounting for 86% of our full-year forecast, highlighting a significant improvement in underlying profitability.
- Refining margins remained strong, but hedging losses weighed on profitability. Run rate fell to 262.5kbd (89% utilisation) from 272.6kbd in 2Q26 due to a 28-day slowdown at Sriracha refinery. Market gross refinery margin (GRM) remained strong at US$17.36/bbl, compared with US$18.41/bbl in 2Q26 and US$7.38/bbl in 3Q25. However, oil hedging losses increased to US$4.18/bbl from US$1.09/bbl in 2Q26, reducing total GRM to US$13.72/bbl. The refining business recorded an inventory gain of Bt437m, including net realisable value adjustments.
Highlights
- BCP reported a 3Q26 net profit of Bt9.85b (+789% yoy, -20% qoq), while core profit rose 287% yoy and 1% qoq to Bt12.3b, in line with our forecasts.
- Basic GRM stayed elevated at US$17.36/bbl despite scheduled maintenance at Sriracha, while higher hedging losses weighed on reported earnings. SAF, biofuels and overseas marketing operations provided additional support.
- We expect 2027 earnings to remain well above historical levels. Maintain BUY with a target price of Bt65.00.
Analysis
- Strong earnings as expected. Bangchak Corporation (BCP) reported 3Q26 net profit of Bt9.85b (-20% qoq, +789% yoy), with core profit (exclude impact from hedging gain/loss) of Bt12.3b (+287% yoy, +1% qoq ), in line with our forecast (see our results preview report on 26 Oct 26). 9M26 core profit reached Bt34.3b, accounting for 86% of our full-year forecast, highlighting a significant improvement in underlying profitability.
- Refining margins remained strong, but hedging losses weighed on profitability. Run rate fell to 262.5kbd (89% utilisation) from 272.6kbd in 2Q26 due to a 28-day slowdown at Sriracha refinery. Market gross refinery margin (GRM) remained strong at US$17.36/bbl, compared with US$18.41/bbl in 2Q26 and US$7.38/bbl in 3Q25. However, oil hedging losses increased to US$4.18/bbl from US$1.09/bbl in 2Q26, reducing total GRM to US$13.72/bbl. The refining business recorded an inventory gain of Bt437m, including net realisable value adjustments.
BUY (Maintained)
Current price:
Target price:
Upside:
Bt43.50
Bt65.00
+49.4%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

26 Oct 2026
Bangchak Corporation (BCP TB): Expect Another Solid Quarter

2 Nov 2026
i-Tail Corporation (ITC TB) - 3Q26: Earnings In Line; Positive On Industry Growth

2 Nov 2026
PTT Exploration & Production (PTTEP TB) - 3Q26: Net Profit Below Expectations
Our latest research

9 Nov 2026
CP Axtra (CPAXT TB): 3Q26: Earnings Trough; Store Closures to Boost Profit

9 Nov 2026
KCE (Thailand) (KCE TB): Management Guides A Strong 4Q26-2027 Outlook; More Attractive Valuation Presents Trading Opportunities

9 Nov 2026