Company Coverage
CP Axtra (CPAXT TB): Weak 3Q26 Earnings But Expected To Bottom Out
HOLD (Maintained)
Current price:
Target price:
Upside:
Bt14.20
Bt14.50
+2.11%
Analyst
Highlights
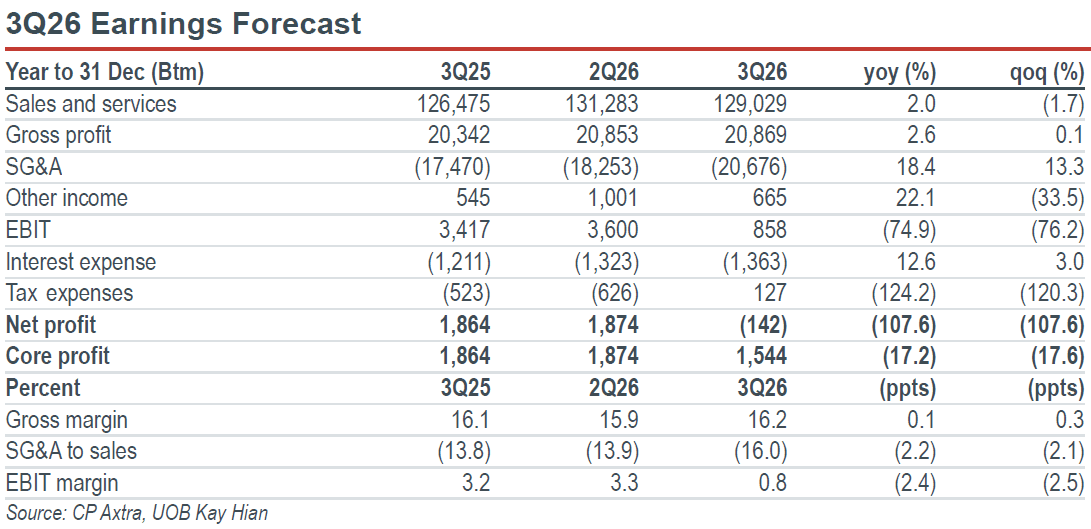
- 3Q26 earnings are likely to be weak, with a net loss of Bt142m. Excluding the one-time loss from the closure of non-performing stores, core profit is projected to drop 17% yoy to Bt1.5b.
- We expect 4Q26 earnings to improve from the closure of non-performing stores, softer impact from the Thai Help Thai Plus campaign and low base in 4Q25.
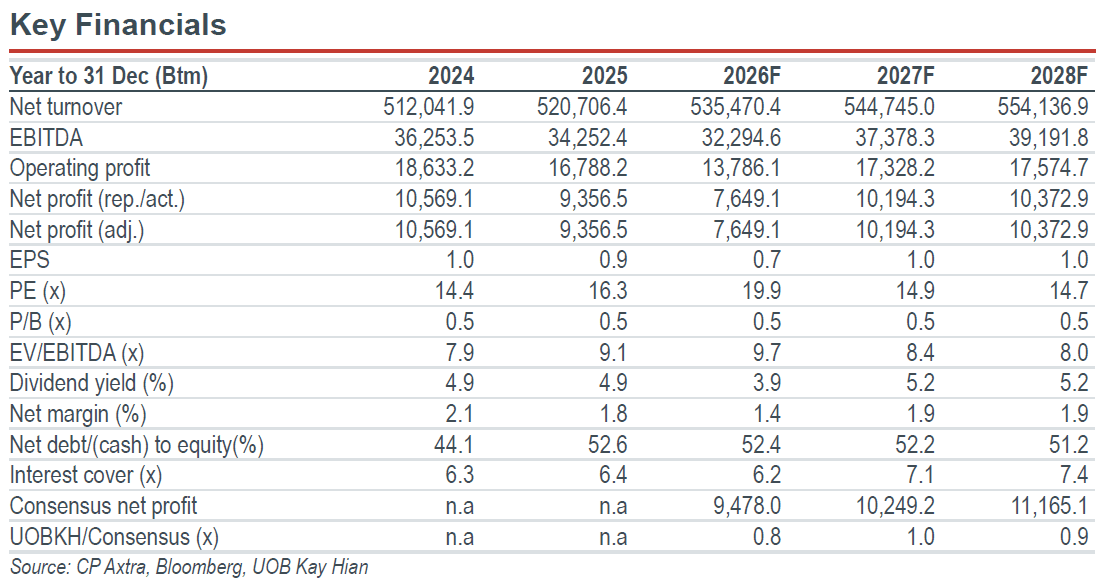
- Maintain HOLD with a target price of Bt14.50. We roll over our target price based on a 2027F PE of 15x.
Analysis
Weak earnings expected in 3Q26. We estimate that CP Axtra (CPAXT) will report a net loss of Bt142m. Excluding a one-time loss from the closure of non-performing stores, core profit is expected at Bt1.5b, down 17% yoy and 18% qoq. 3Q26 earnings could be driven by: a) revenue growth of 2% yoy, supported by the wholesale business; and b) a 10bp improvement in gross margin to 16.2%, supported by better price management and shrinkage control. However, earnings will be pressured by: a) higher SG&A expenses from one-time loss related to the closure of the Makro Siem Reap store and Lotus’s small-format, pre-opening expenses for The Happitat; and b) slightly higher interest expenses from debt raised to acquire The Food Purveyor (TFP). Nevertheless, the tax benefit from the reported loss should provide some support to earnings.
Highlights
- 3Q26 earnings are likely to be weak, with a net loss of Bt142m. Excluding the one-time loss from the closure of non-performing stores, core profit is projected to drop 17% yoy to Bt1.5b.
- We expect 4Q26 earnings to improve from the closure of non-performing stores, softer impact from the Thai Help Thai Plus campaign and low base in 4Q25.
- Maintain HOLD with a target price of Bt14.50. We roll over our target price based on a 2027F PE of 15x.
Analysis
Weak earnings expected in 3Q26. We estimate that CP Axtra (CPAXT) will report a net loss of Bt142m. Excluding a one-time loss from the closure of non-performing stores, core profit is expected at Bt1.5b, down 17% yoy and 18% qoq. 3Q26 earnings could be driven by: a) revenue growth of 2% yoy, supported by the wholesale business; and b) a 10bp improvement in gross margin to 16.2%, supported by better price management and shrinkage control. However, earnings will be pressured by: a) higher SG&A expenses from one-time loss related to the closure of the Makro Siem Reap store and Lotus’s small-format, pre-opening expenses for The Happitat; and b) slightly higher interest expenses from debt raised to acquire The Food Purveyor (TFP). Nevertheless, the tax benefit from the reported loss should provide some support to earnings.
HOLD (Maintained)
Current price:
Target price:
Upside:
Bt14.20
Bt14.50
+2.11%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


