Company Coverage
True Corporation (TRUE TB) - Earnings Remain Positive For Seventh Consecutive Quarter While Deleveraging Continues
BUY (Maintained)
Current price:
Target price:
Upside:
Bt12.80
Bt16.50
+28.9%
Analyst
Analyst
Sirithat Prasertwuti
Sirithat@uobkh.co.thHighlights
- TRUE reported a 3Q26 net profit of Bt6.64b (+322% yoy, +1% qoq), below expectations by 4%, due to a slightly lower gross margin than expected.
- The tone was neutral, as there is no significant change in terms of guidance. Core service sales and EBITDA growth remain on track.
- Flood impact on 4Q26 operations is limited, as only 1m households were affected. 4Q26 is expected to be the strongest quarter.
- Maintain BUY with a target price of Bt16.50.
Analysis
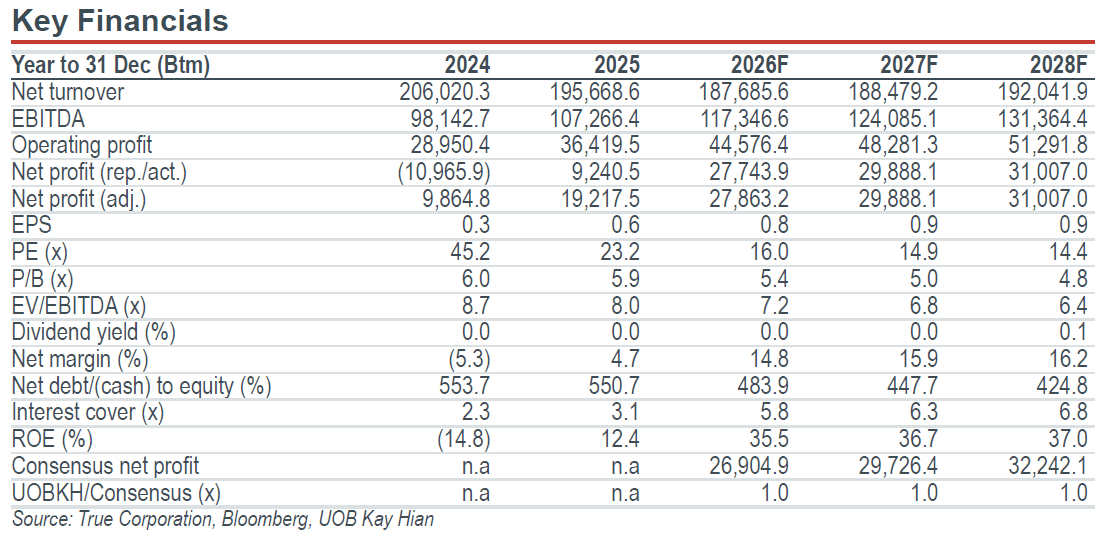
- 3Q26 earnings remained healthy for the seventh consecutive quarter, driven by healthy core operations and lower finance costs. True Corporation (TRUE) reported a 3Q26 net profit of Bt6.64b (+322% yoy, +1% qoq), below our and consensus forecasts by 4% due to a slightly lower gross margin than expected during low season. Excluding a one-time write-off expense, core net profit came in higher at Bt6.96b (+51% yoy, +3% qoq), driven by a resilient mobile and broadband business and lower finance costs qoq. Overall, TRUE’s earnings remained positive for a seventh consecutive quarter and total subscriber additions continued to grow for the fourth consecutive quarter. The slower pace of net additions in 3Q26 reflects normalisation as last quarter’s prepaid net additions were partly inflated by a National Broadcasting and Telecommunication Commission rule allowing a Bt3 charge to extend certain inactive subscribers' validity by another 30 days and Thai Help Thai Plus scheme, which boosted active users.
- 3Q26 mobile and broadband operations remain resilient, while EBITDA growth remains on track at 7-9%. Core service revenue remained healthy both yoy and qoq at Bt41.6b (+0.9% yoy, +0.6% qoq), broadly in line with our forecast, marking the first qoq revenue recovery in 2026. Mobile and broadband revenue continued to grow in 3Q26, supported by higher ARPU qoq and positive net subscriber additions. Handset sales also improved significantly qoq, driven by the iPhone launch in Sep 26. EBITDA continued to rise to Bt29.04b (+6.3% yoy, +0.8% qoq), benefitting from spectrum-related cost savings and operational efficiencies (EBITDA expanded 9% yoy in 9M26, in line with 2026 growth guidance of 7-9%).
- Tone was neutral: Management maintains its 2026 core service sales growth forecast of 1-2%, while flood impact on 4Q26 operations is limited. Overall, the tone at the meeting was neutral, as there are no significant changes in terms of guidance. Management maintains its 2026 core services sales growth forecast of 1-2% yoy in 2026 (vs +0.3% in 9M26), implying that 4Q26 sales should significantly improve from 3Q26. 4Q typically benefits from festive-season spending. Management said the flood affected 3Q26 results, but the impact on 4Q26 earnings is limited as only 1m households were affected.
Highlights
- TRUE reported a 3Q26 net profit of Bt6.64b (+322% yoy, +1% qoq), below expectations by 4%, due to a slightly lower gross margin than expected.
- The tone was neutral, as there is no significant change in terms of guidance. Core service sales and EBITDA growth remain on track.
- Flood impact on 4Q26 operations is limited, as only 1m households were affected. 4Q26 is expected to be the strongest quarter.
- Maintain BUY with a target price of Bt16.50.
Analysis
- 3Q26 earnings remained healthy for the seventh consecutive quarter, driven by healthy core operations and lower finance costs. True Corporation (TRUE) reported a 3Q26 net profit of Bt6.64b (+322% yoy, +1% qoq), below our and consensus forecasts by 4% due to a slightly lower gross margin than expected during low season. Excluding a one-time write-off expense, core net profit came in higher at Bt6.96b (+51% yoy, +3% qoq), driven by a resilient mobile and broadband business and lower finance costs qoq. Overall, TRUE’s earnings remained positive for a seventh consecutive quarter and total subscriber additions continued to grow for the fourth consecutive quarter. The slower pace of net additions in 3Q26 reflects normalisation as last quarter’s prepaid net additions were partly inflated by a National Broadcasting and Telecommunication Commission rule allowing a Bt3 charge to extend certain inactive subscribers' validity by another 30 days and Thai Help Thai Plus scheme, which boosted active users.
- 3Q26 mobile and broadband operations remain resilient, while EBITDA growth remains on track at 7-9%. Core service revenue remained healthy both yoy and qoq at Bt41.6b (+0.9% yoy, +0.6% qoq), broadly in line with our forecast, marking the first qoq revenue recovery in 2026. Mobile and broadband revenue continued to grow in 3Q26, supported by higher ARPU qoq and positive net subscriber additions. Handset sales also improved significantly qoq, driven by the iPhone launch in Sep 26. EBITDA continued to rise to Bt29.04b (+6.3% yoy, +0.8% qoq), benefitting from spectrum-related cost savings and operational efficiencies (EBITDA expanded 9% yoy in 9M26, in line with 2026 growth guidance of 7-9%).
- Tone was neutral: Management maintains its 2026 core service sales growth forecast of 1-2%, while flood impact on 4Q26 operations is limited. Overall, the tone at the meeting was neutral, as there are no significant changes in terms of guidance. Management maintains its 2026 core services sales growth forecast of 1-2% yoy in 2026 (vs +0.3% in 9M26), implying that 4Q26 sales should significantly improve from 3Q26. 4Q typically benefits from festive-season spending. Management said the flood affected 3Q26 results, but the impact on 4Q26 earnings is limited as only 1m households were affected.
BUY (Maintained)
Current price:
Target price:
Upside:
Bt12.80
Bt16.50
+28.9%
Analyst
Analyst
Sirithat Prasertwuti
Sirithat@uobkh.co.thIMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


