Company Coverage
Thai Union Group (TU TB) - 3Q26: Core Profit Beat Expectations; Core Operation To Improve Amid Higher Costs
BUY (Maintained)
Current price:
Target price:
Upside:
Bt12.70
Bt14.50
14.17%
Analyst
Highlights
- TU reported 3Q26 core profit of Bt1,457m (+20.5% yoy, +6.8% qoq), slightly exceeding our and market estimates, driven by better-than-expected gross profit margin and a lower-than-expected SG&A-to-sales ratio.
- Although we expect 4Q26 earnings to decline qoq due to the low season and increased raw material cost pressure, we expect earnings to grow yoy, supported by resilient gross margins and enhanced sales volume.
- Maintain BUY. Target price: Bt14.50.
Analysis
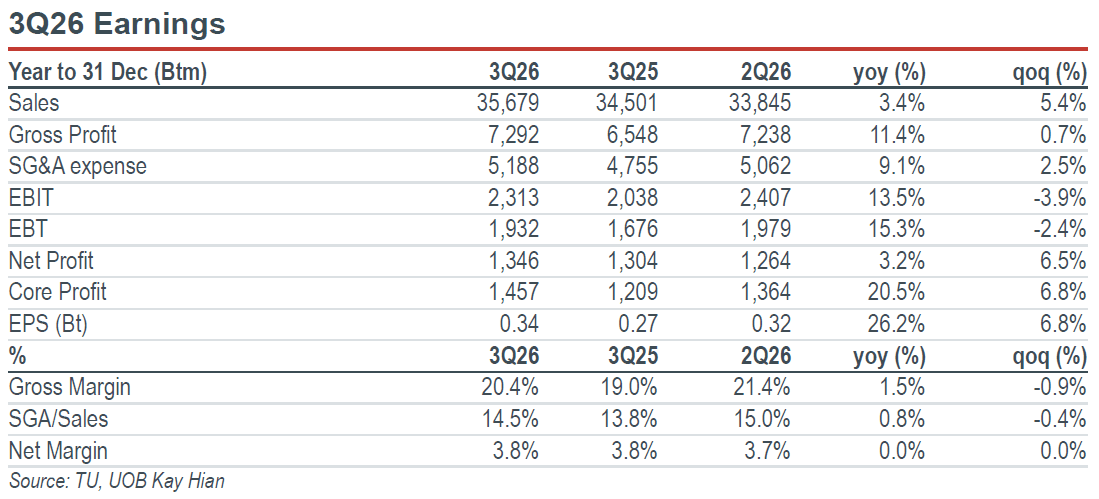
- Earnings beat. Thai Union Group (TU) reported 3Q26 net profit of Bt1,346m (+3.2% yoy, +6.5% qoq). Excluding one-off items, core profit came in at Bt1,457m (+20.5% yoy, +6.8% qoq), slightly exceeding our and market estimates, on the back of better-than-expected gross profit margin and a lower-than-expected SG&A-to-sales ratio.
- Top-line recovered yoy and qoq. TU reported 3Q26 revenue of Bt35.7b (+3.4% yoy, +5.4% qoq), thanks to stronger sales across ambient, pet food, and value-added products. Ambient sales reached Bt17.9b (+3.9% yoy, +6.3% qoq), while frozen seafood sales declined to Bt10.0b (-4.0% yoy, -0.8% qoq). Pet food sales grew to Bt5.1b (+10.4% yoy, +13.7% qoq), while value-added sales increased to Bt2.7b (+19.5% yoy, +9.4% qoq).
Highlights
- TU reported 3Q26 core profit of Bt1,457m (+20.5% yoy, +6.8% qoq), slightly exceeding our and market estimates, driven by better-than-expected gross profit margin and a lower-than-expected SG&A-to-sales ratio.
- Although we expect 4Q26 earnings to decline qoq due to the low season and increased raw material cost pressure, we expect earnings to grow yoy, supported by resilient gross margins and enhanced sales volume.
- Maintain BUY. Target price: Bt14.50.
Analysis
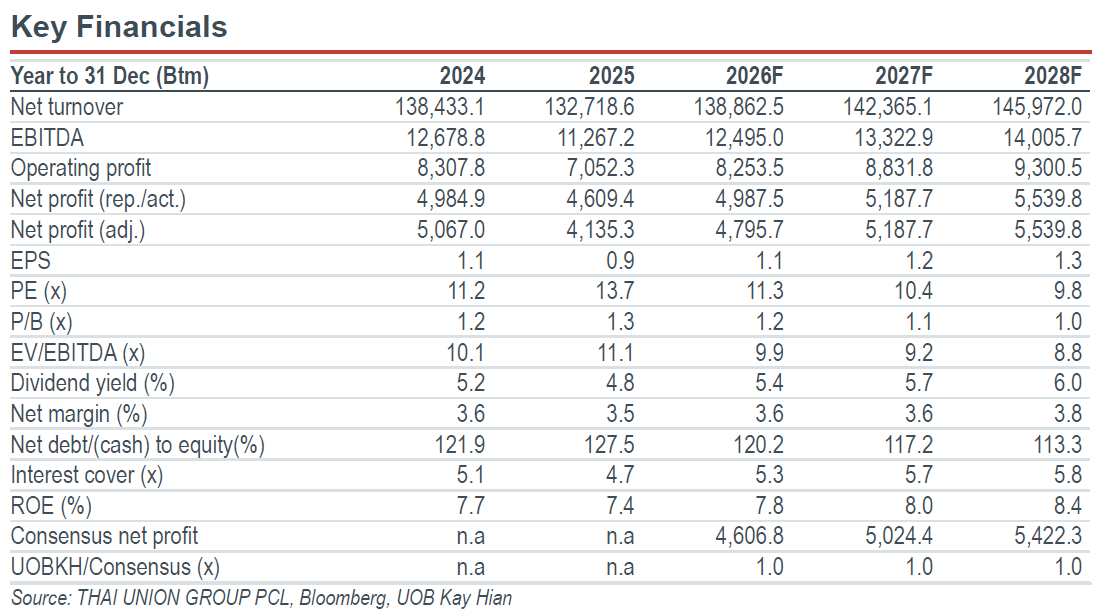
- Earnings beat. Thai Union Group (TU) reported 3Q26 net profit of Bt1,346m (+3.2% yoy, +6.5% qoq). Excluding one-off items, core profit came in at Bt1,457m (+20.5% yoy, +6.8% qoq), slightly exceeding our and market estimates, on the back of better-than-expected gross profit margin and a lower-than-expected SG&A-to-sales ratio.
- Top-line recovered yoy and qoq. TU reported 3Q26 revenue of Bt35.7b (+3.4% yoy, +5.4% qoq), thanks to stronger sales across ambient, pet food, and value-added products. Ambient sales reached Bt17.9b (+3.9% yoy, +6.3% qoq), while frozen seafood sales declined to Bt10.0b (-4.0% yoy, -0.8% qoq). Pet food sales grew to Bt5.1b (+10.4% yoy, +13.7% qoq), while value-added sales increased to Bt2.7b (+19.5% yoy, +9.4% qoq).
BUY (Maintained)
Current price:
Target price:
Upside:
Bt12.70
Bt14.50
14.17%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


