

Company Coverage
Central Plaza Hotel (CENTEL TB): Expect Robust 3Q26 Earnings, Supported By Strong RevPar Growth
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt46.50
Bt58.00
+24.7%
Bt50.00
Analyst
Analyst
Nonpawit Vathanadachakul
Highlights
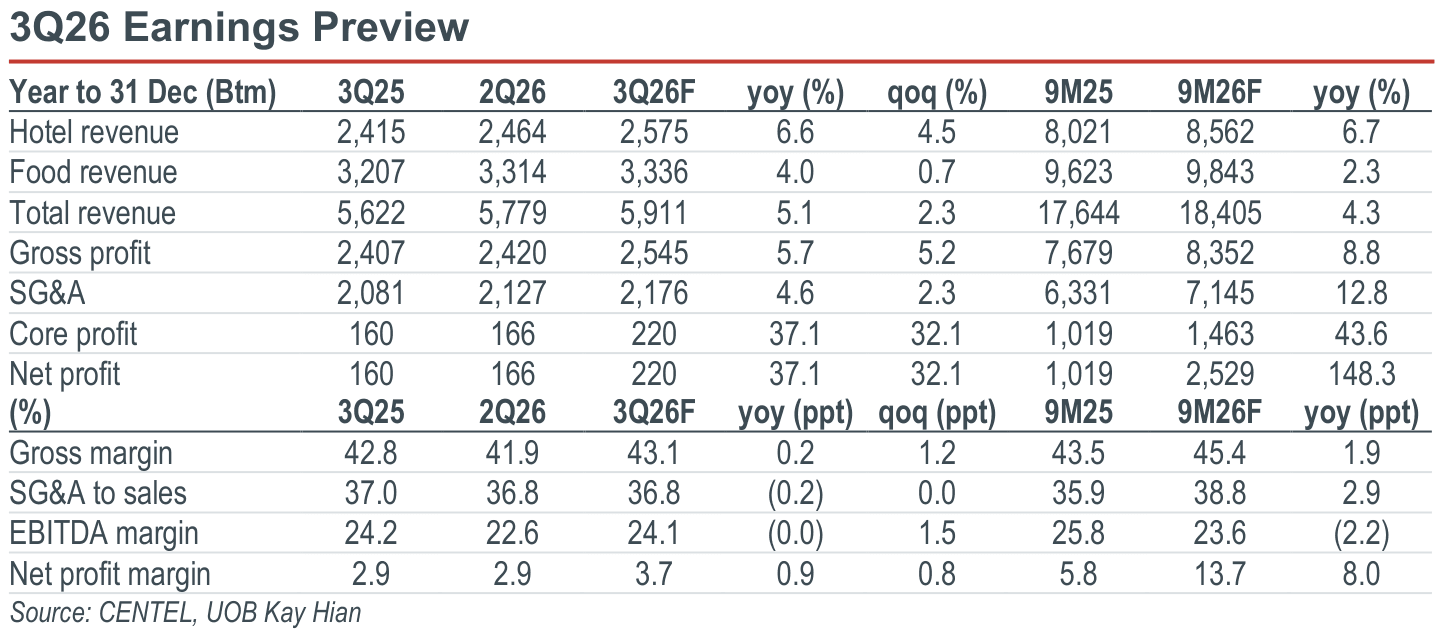
- We expect CENTEL to report a robust net profit of Bt220m (+37.1% yoy, +32.1% qoq) for 3Q26, with strong yoy RevPar growth being the key driver.
- Food business performance is resilient despite the pressure, and we expect gross margins to improve yoy in 3Q26 from several cost saving measures.
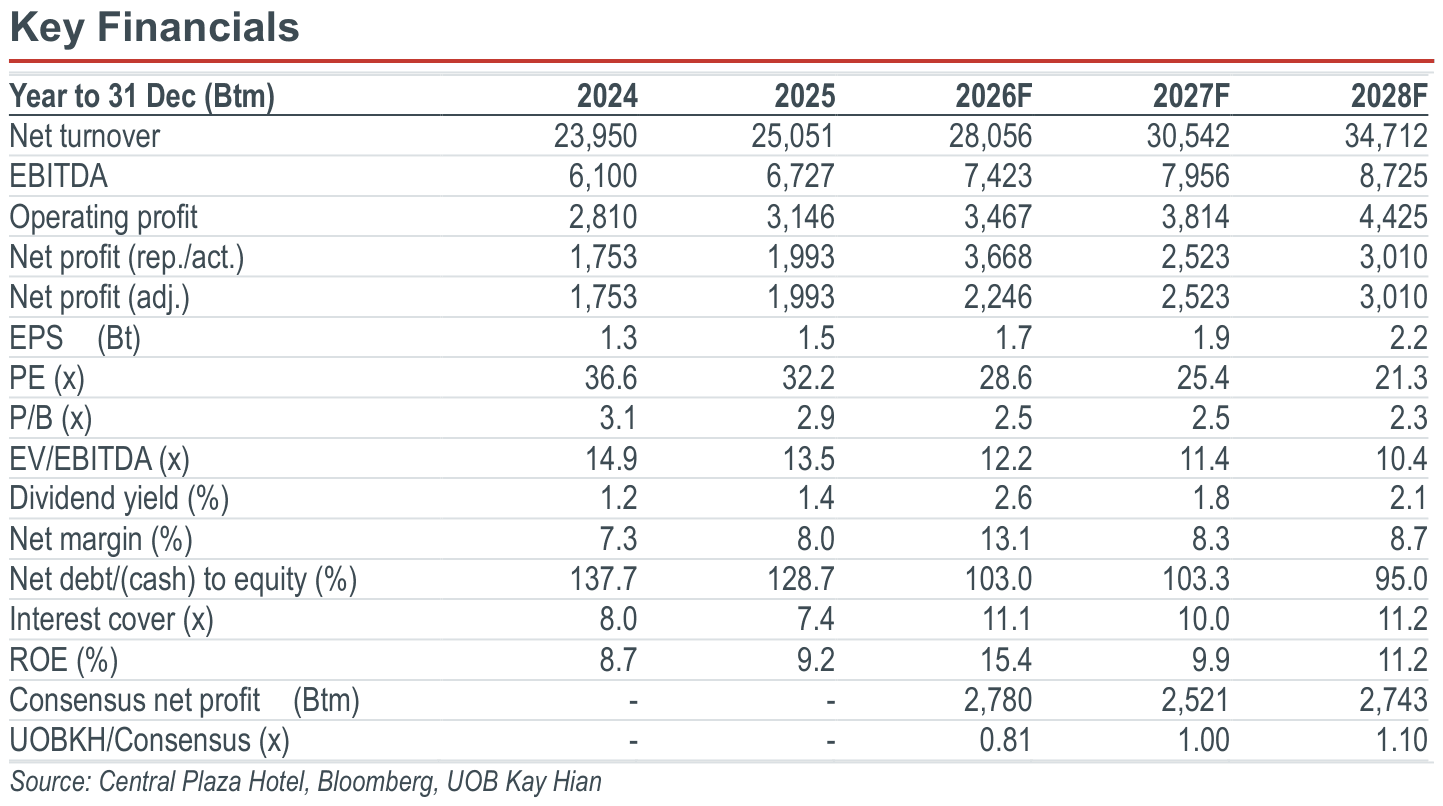
- Earnings outlook remains brilliant as the hotel bookings are strong and interest expense should continue to decline in 4Q26. CENTEL remains our top pick. Maintain BUY with a target price of Bt58.00 (previously Bt50.00).
Analysis
- Robust earnings growth expected in 3Q26. We expect Central Plaza Hotel (CENTEL) to report a net profit of Bt220m (+37.1% yoy, +32.1% qoq) for 3Q26. Top-line should be at Bt5.9b (+5.1% yoy, +2.3% qoq), supported by strong performance from both the hotel and food businesses. The earnings growth is expected to be mainly driven by continuously strong performance at the Maldives, which should show a robust 37% yoy growth in RevPar. Another strong contributor is the upcountry hotels which should show a robust 16% yoy growth in RevPar, with Pattaya, Samui, and Phuket as the main contributors. As a result, the portfolio RevPar should show very strong growth yoy at 11%. Meanwhile, the food business should also show decent performance, and we expect food gross margins to expand yoy, attributable to strict cost control measures and new high-margin product launches. As a result, we expect EBITDA margins to remain flat yoy.
Highlights
- We expect CENTEL to report a robust net profit of Bt220m (+37.1% yoy, +32.1% qoq) for 3Q26, with strong yoy RevPar growth being the key driver.
- Food business performance is resilient despite the pressure, and we expect gross margins to improve yoy in 3Q26 from several cost saving measures.
- Earnings outlook remains brilliant as the hotel bookings are strong and interest expense should continue to decline in 4Q26. CENTEL remains our top pick. Maintain BUY with a target price of Bt58.00 (previously Bt50.00).
Analysis
- Robust earnings growth expected in 3Q26. We expect Central Plaza Hotel (CENTEL) to report a net profit of Bt220m (+37.1% yoy, +32.1% qoq) for 3Q26. Top-line should be at Bt5.9b (+5.1% yoy, +2.3% qoq), supported by strong performance from both the hotel and food businesses. The earnings growth is expected to be mainly driven by continuously strong performance at the Maldives, which should show a robust 37% yoy growth in RevPar. Another strong contributor is the upcountry hotels which should show a robust 16% yoy growth in RevPar, with Pattaya, Samui, and Phuket as the main contributors. As a result, the portfolio RevPar should show very strong growth yoy at 11%. Meanwhile, the food business should also show decent performance, and we expect food gross margins to expand yoy, attributable to strict cost control measures and new high-margin product launches. As a result, we expect EBITDA margins to remain flat yoy.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt46.50
Bt58.00
+24.7%
Bt50.00
Analyst
Analyst
Nonpawit Vathanadachakul
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


