Company Coverage
Bangkok Dusit Medical Services (BDMS TB): Expect Strong 3Q26 Earnings, Supported By Thai Patients
BUY (Maintained)
Current price:
Target price:
Upside:
Bt19.10
Bt27.00
+41.4%
Analyst
Analyst
Nonpawit Vathanadachakul
Highlights
- BDMS is expected to report a strong net profit at Bt4.66b in 3Q26 (+7.8% yoy, +43.4% qoq).
- We expect to see strong yoy revenue growth from both Thai and foreign patients, supported by the epidemic and new promotions.
- We remain optimistic on BDMS’ earnings outlook in 4Q26 as the inflow of Middle East patients remains strong and the number of cases from the epidemic remains high. Maintain BUY with a target price of Bt27.00.
Analysis
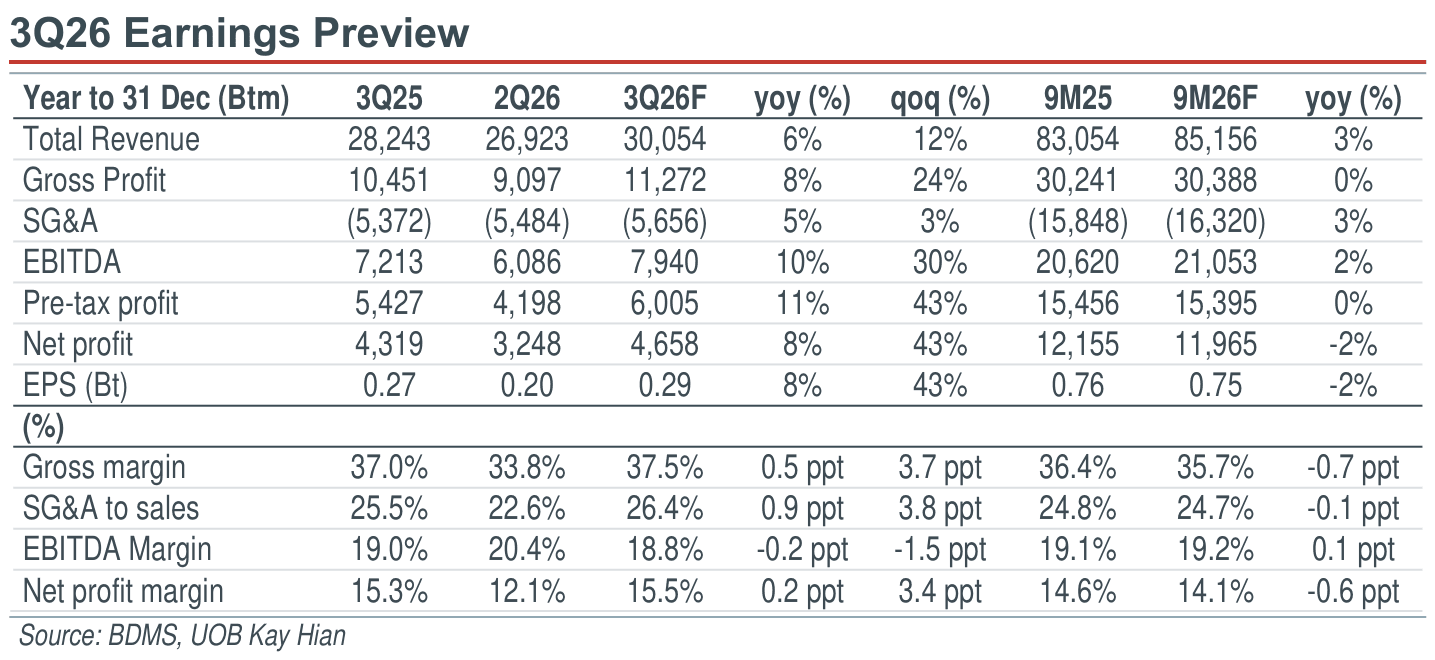
- Expect strong yoy earnings growth in 3Q26. Bangkok Dusit Medical Services (BDMS) is expected to report a robust net profit of Bt4.66b in 3Q26 (+7.8% yoy, +43.4% qoq). Top-line should come in at Bt30.0b (+6.4% yoy, +11.6% qoq), with the main contributor expected to be Thai patients. We expect Thai patient revenue to show a strong growth of +6% yoy in 3Q26, reflecting the positive impact from epidemic and BDMS’ active promotion strategy. Foreign patient revenue is expected to show high single-digit growth yoy, with patients from Myanmar, Bangladesh, the US and the UK being key contributors. BDMS should start to achieve economies of scale in 3Q26 as the top-line growth is strong enough. We should also see an improvement in gross margin due to the improving inflow of Middle East patients. Hence, we expect BDMS’ EBITDA margins to expand yoy.
Highlights
- BDMS is expected to report a strong net profit at Bt4.66b in 3Q26 (+7.8% yoy, +43.4% qoq).
- We expect to see strong yoy revenue growth from both Thai and foreign patients, supported by the epidemic and new promotions.
- We remain optimistic on BDMS’ earnings outlook in 4Q26 as the inflow of Middle East patients remains strong and the number of cases from the epidemic remains high. Maintain BUY with a target price of Bt27.00.
Analysis
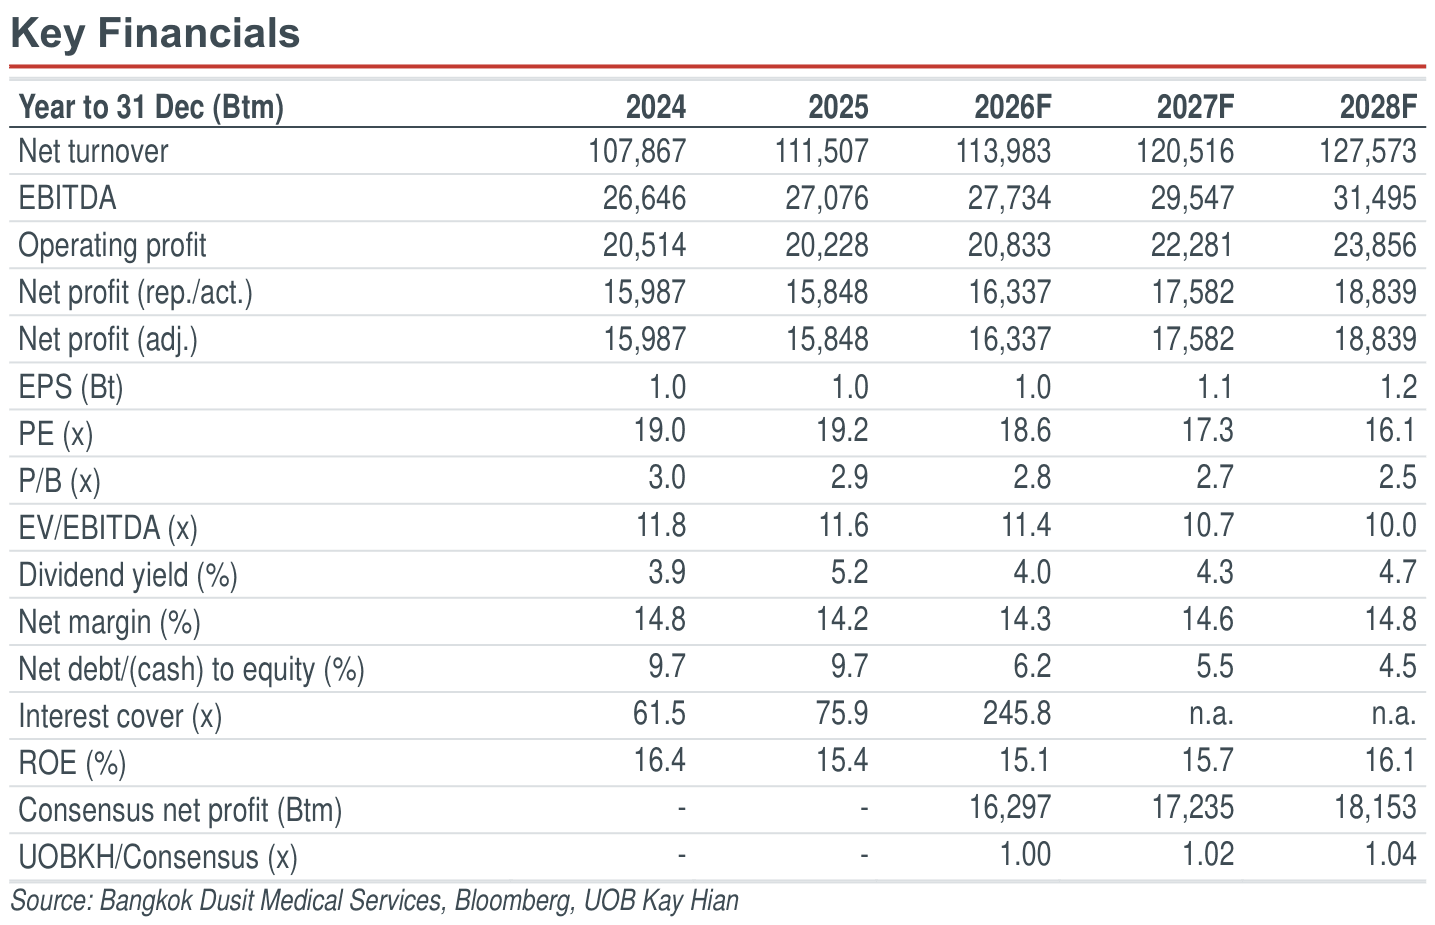
- Expect strong yoy earnings growth in 3Q26. Bangkok Dusit Medical Services (BDMS) is expected to report a robust net profit of Bt4.66b in 3Q26 (+7.8% yoy, +43.4% qoq). Top-line should come in at Bt30.0b (+6.4% yoy, +11.6% qoq), with the main contributor expected to be Thai patients. We expect Thai patient revenue to show a strong growth of +6% yoy in 3Q26, reflecting the positive impact from epidemic and BDMS’ active promotion strategy. Foreign patient revenue is expected to show high single-digit growth yoy, with patients from Myanmar, Bangladesh, the US and the UK being key contributors. BDMS should start to achieve economies of scale in 3Q26 as the top-line growth is strong enough. We should also see an improvement in gross margin due to the improving inflow of Middle East patients. Hence, we expect BDMS’ EBITDA margins to expand yoy.
BUY (Maintained)
Current price:
Target price:
Upside:
Bt19.10
Bt27.00
+41.4%
Analyst
Analyst
Nonpawit Vathanadachakul
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


