

Company Coverage
Minor International (MINT TB): Soft Core Growth Expected In 3Q26 Due To Margin Weakness
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt20.50
Bt19.50
-4.9%
Bt24.00
Analyst
Analyst
Nonpawit Vathanadachakul
Highlights
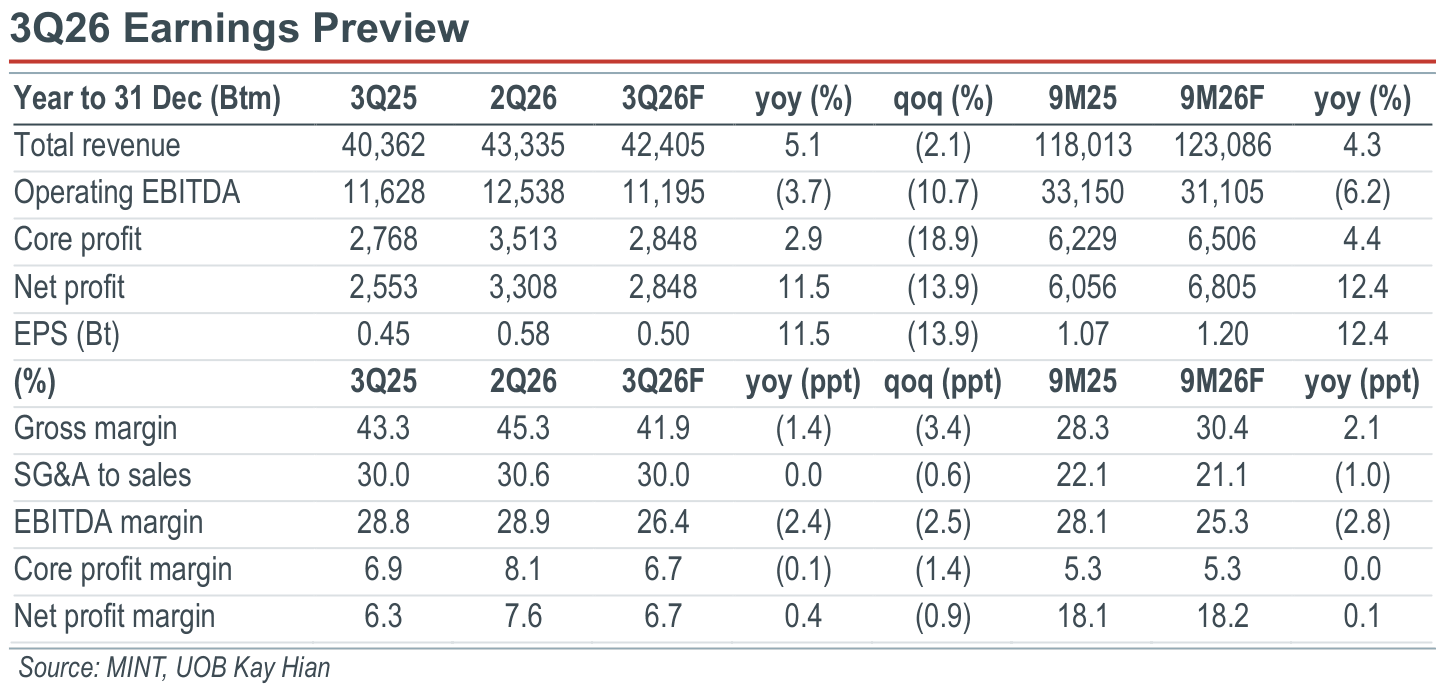
- MINT is expected to report a weak core profit of Bt2.85b in 3Q26 (+2.9% yoy, -18.9% qoq), mainly pressured by several costs.
- We will closely monitor the progress of its asset rotation plan which is a backup plan to the postponed REIT launch.
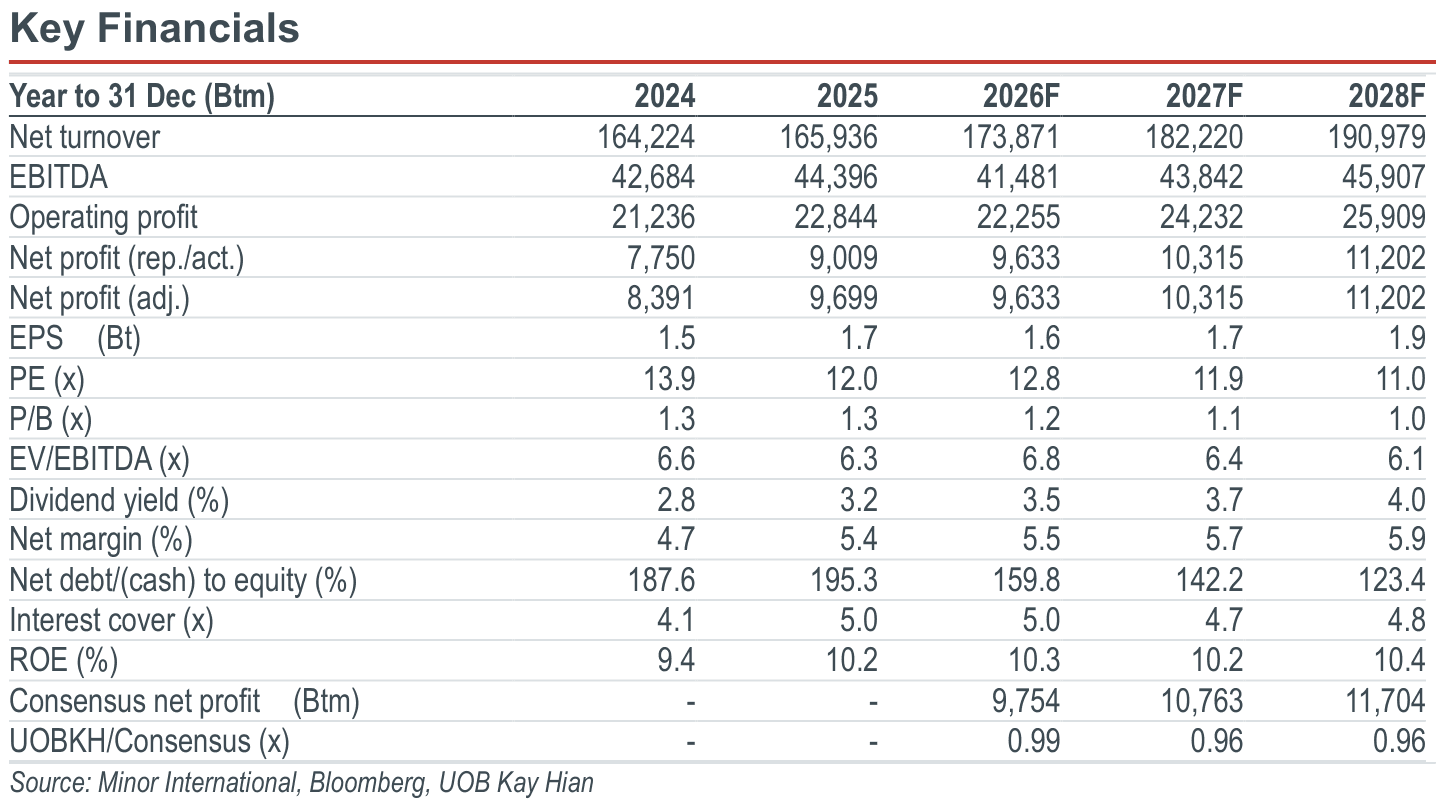
- We remain cautious on MINT as the interest expense remains high and the forward bookings are still not very promising in 4Q26. Maintain HOLD with a target price of Bt19.50 (previously Bt24.00).
Analysis
- We expect a soft yoy core profit growth in 3Q26. Minor International (MINT) is forecast to report a core profit of Bt2.85b in 3Q26 (+2.9% yoy, -18.9% qoq). There are no notable extra items, thus its net profit should be at the same level at Bt2.85b (+11.5% yoy, -13.9% qoq). Top-line should come in at Bt42.4b (+5.1% yoy, -2.1% qoq). The overall RevPar from MINT’s hotels is expected to show a strong yoy growth of 8%. RevPar in Europe grew 7% yoy in euros and RevPar in Thailand rose 16% yoy, driven by the increased room rate after the renovation. Interest expense in 3Q26 should increase yoy and also slightly qoq from the new syndicated loan. We project that gross margins will significantly decline yoy as MINT will be facing cost pressure from hotel business due to indirect impact of surging energy costs. Costs such as labour, leases, packaging and plastics are the key pressures.
Highlights
- MINT is expected to report a weak core profit of Bt2.85b in 3Q26 (+2.9% yoy, -18.9% qoq), mainly pressured by several costs.
- We will closely monitor the progress of its asset rotation plan which is a backup plan to the postponed REIT launch.
- We remain cautious on MINT as the interest expense remains high and the forward bookings are still not very promising in 4Q26. Maintain HOLD with a target price of Bt19.50 (previously Bt24.00).
Analysis
- We expect a soft yoy core profit growth in 3Q26. Minor International (MINT) is forecast to report a core profit of Bt2.85b in 3Q26 (+2.9% yoy, -18.9% qoq). There are no notable extra items, thus its net profit should be at the same level at Bt2.85b (+11.5% yoy, -13.9% qoq). Top-line should come in at Bt42.4b (+5.1% yoy, -2.1% qoq). The overall RevPar from MINT’s hotels is expected to show a strong yoy growth of 8%. RevPar in Europe grew 7% yoy in euros and RevPar in Thailand rose 16% yoy, driven by the increased room rate after the renovation. Interest expense in 3Q26 should increase yoy and also slightly qoq from the new syndicated loan. We project that gross margins will significantly decline yoy as MINT will be facing cost pressure from hotel business due to indirect impact of surging energy costs. Costs such as labour, leases, packaging and plastics are the key pressures.
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt20.50
Bt19.50
-4.9%
Bt24.00
Analyst
Analyst
Nonpawit Vathanadachakul
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


