Company Coverage
Advance Info Services (ADVANC TB): 3Q26 Earnings Down Slightly qoq As Expected But Beat Forecasts On Strong Smartphone Sales, Particularly Samsung Models
BUY (Maintained)
Current price:
Target price:
Upside:
Bt340.00
Bt415.00
+20.3%
Analyst
Analyst
Sirithat Prasertwuti
Sirithat@uobkayhian.co.thHighlights
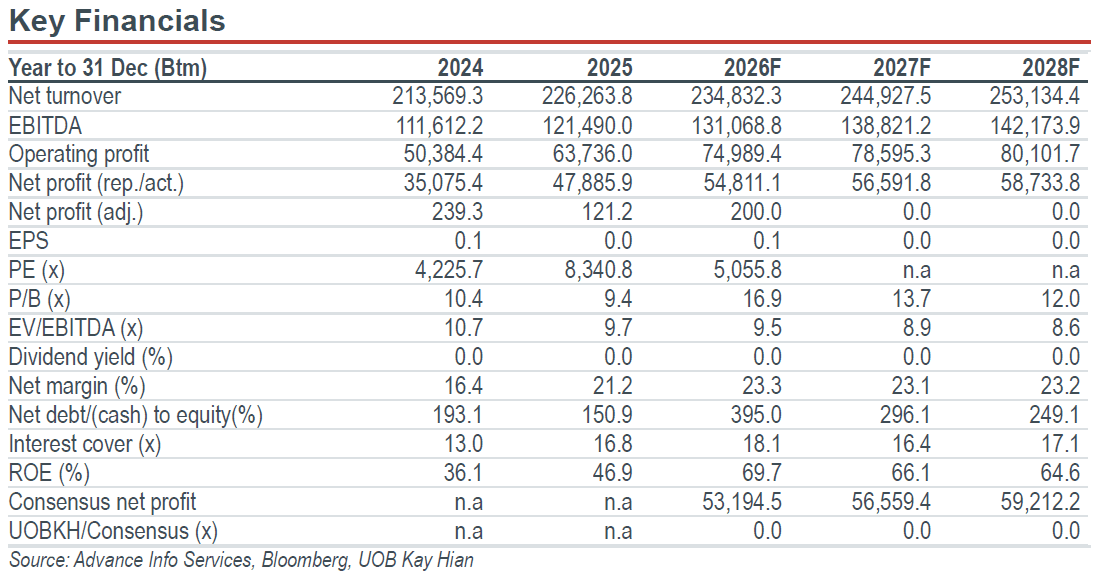
- ADVANC reported a 3Q26 net profit of Bt13.5b (+12% yoy, -2% qoq), slightly above our and Bloomberg consensus by 1.2% and 2.8%. Strong handset sales drove the 3Q26 beat, offsetting softer core service revenue.
- The tone at the meeting was positive. Core service sales growth is expected to meet the upper-bound of its 2026 guidance, while EBITDA growth is likely to beat guidance.
- Maintain BUY with a target price of Bt415.00. Any share price decline would offer a higher dividend yield and an attractive entry point.
Analysis
- Earnings declined slightly qoq as expected but beat forecasts on strong smartphone sales, particularly Samsung models. Advance Info Services (ADVANC) reported a 3Q26 net profit of Bt13.5b (+12% yoy, -2% qoq), slightly above our and Bloomberg consensus by 1.2% and 2.8%, respectively due to management’s conservative guidance. Total sales came in at Bt58.06b (+6.8% yoy, +2.8% qoq), above our estimate and Bloomberg consensus by 1.0% and 1.7%, respectively. The key surprise behind the sales and earnings beats was strong handset sales of Bt11.6b (+29.4% yoy, +16.1% qoq). Demand remained strong despite higher device prices, supported by expansion across both offline and online channels. Apple unit sales grew 7% qoq, while Samsung rose 30% qoq, particularly budget models such as the A07. Meanwhile, Chinese brands declined 20% ahead of new Vivo and Oppo launches in 4Q26. On the other hand, core service revenue softened to Bt44.9b (+3.0% yoy, -1.3% qoq), reflecting slower net additions and lower ARPU qoq following the end of the English Premier League (EPL).
- Slightly positive meeting tone: Core service sales growth to meet guidance, EBITDA to beat guidance, strong handset sales continuing in 4Q26. The tone at the meeting was positive on three fronts: a) core service revenue growth should reach the upper end of the 3-5% guidance range (vs 5.2% yoy growth in 9M26), b) EBITDA growth is expected to slightly exceed the 2-4% guidance range (vs 6.8% yoy growth in 9M26); and c) despite stronger-than-expected handset unit sales in 3Q26, handset sales should remain strong during the high season in 4Q26, supported by continued growth in Samsung unit sales and demand for the iPhone 18/Duo. In addition, accessories sales grew 30% qoq, in line with smartphone sales, while insurance sales (AIS Care+) also posted strong growth in 3Q26. Management said that ADVANC has gained smartphone unit market share through store modernisation and expanded distribution.
Highlights
- ADVANC reported a 3Q26 net profit of Bt13.5b (+12% yoy, -2% qoq), slightly above our and Bloomberg consensus by 1.2% and 2.8%. Strong handset sales drove the 3Q26 beat, offsetting softer core service revenue.
- The tone at the meeting was positive. Core service sales growth is expected to meet the upper-bound of its 2026 guidance, while EBITDA growth is likely to beat guidance.
- Maintain BUY with a target price of Bt415.00. Any share price decline would offer a higher dividend yield and an attractive entry point.
Analysis
- Earnings declined slightly qoq as expected but beat forecasts on strong smartphone sales, particularly Samsung models. Advance Info Services (ADVANC) reported a 3Q26 net profit of Bt13.5b (+12% yoy, -2% qoq), slightly above our and Bloomberg consensus by 1.2% and 2.8%, respectively due to management’s conservative guidance. Total sales came in at Bt58.06b (+6.8% yoy, +2.8% qoq), above our estimate and Bloomberg consensus by 1.0% and 1.7%, respectively. The key surprise behind the sales and earnings beats was strong handset sales of Bt11.6b (+29.4% yoy, +16.1% qoq). Demand remained strong despite higher device prices, supported by expansion across both offline and online channels. Apple unit sales grew 7% qoq, while Samsung rose 30% qoq, particularly budget models such as the A07. Meanwhile, Chinese brands declined 20% ahead of new Vivo and Oppo launches in 4Q26. On the other hand, core service revenue softened to Bt44.9b (+3.0% yoy, -1.3% qoq), reflecting slower net additions and lower ARPU qoq following the end of the English Premier League (EPL).
- Slightly positive meeting tone: Core service sales growth to meet guidance, EBITDA to beat guidance, strong handset sales continuing in 4Q26. The tone at the meeting was positive on three fronts: a) core service revenue growth should reach the upper end of the 3-5% guidance range (vs 5.2% yoy growth in 9M26), b) EBITDA growth is expected to slightly exceed the 2-4% guidance range (vs 6.8% yoy growth in 9M26); and c) despite stronger-than-expected handset unit sales in 3Q26, handset sales should remain strong during the high season in 4Q26, supported by continued growth in Samsung unit sales and demand for the iPhone 18/Duo. In addition, accessories sales grew 30% qoq, in line with smartphone sales, while insurance sales (AIS Care+) also posted strong growth in 3Q26. Management said that ADVANC has gained smartphone unit market share through store modernisation and expanded distribution.
BUY (Maintained)
Current price:
Target price:
Upside:
Bt340.00
Bt415.00
+20.3%
Analyst
Analyst
Sirithat Prasertwuti
Sirithat@uobkayhian.co.thIMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


