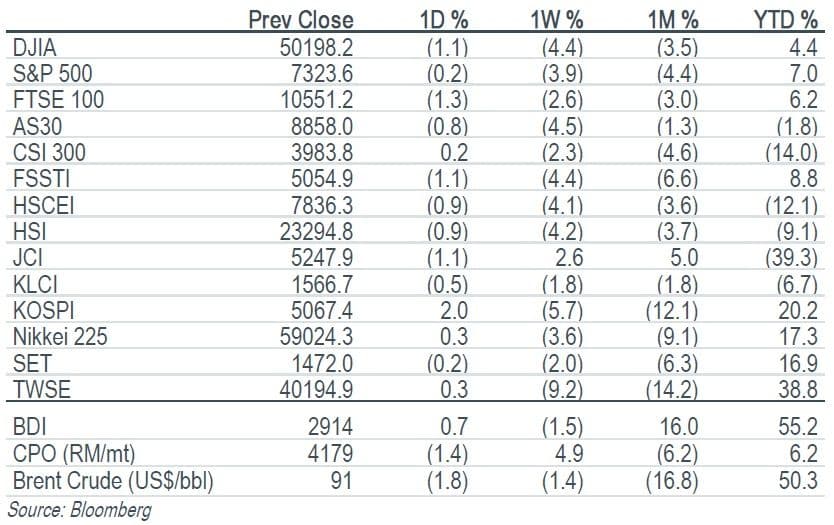
Key Indices
Top Stories
Strategy | 3Q26 Result Wrap-up
- The SET Index’s 3Q26 earnings are in line with expectation, with 2026-27F forecasts largely unchanged. However, earnings revisions varied across sectors, with downward revisions in electronics from raw material shortages, property from pressured gross margin, and banking. These downward revisions were offset by an upward revision in the utilities sector. We maintain a neutral stance, with our 2026 SET target unchanged at 1,818 points under the earnings yield gap approach. Top picks are AWC, BH, BJC, CREDIT, GLOBAL, HANA, and KBANK.
Company Update | Berli Jucker (BJC TB/BUY/Bt20.30/Target: Bt24.50)
- We attended BJC’s analyst meeting on 18 November and came away with a more bullish view. Management expects the business restructuring to generate Bt1.3b in cost savings. If the company achieves its cost-saving target as guided, 2027 earnings could be 11% above our forecast, implying a Bt2.60 upside to our target price. Maintain BUY with a target price of Bt24.50, based on 2027F PE of 17x.
Company Update | Bumrungrad Hospital (BH TB/BUY/Bt193.00/Target: Bt240.00)
- BH delivered a positive analyst meeting, with Middle Eastern patient inflows remaining strong despite the normalisation of Qatar revenue. Although 4Q26 revenue growth is guided to be flattish yoy, earnings should continue growing, supported by cost controls and BOI tax benefits. BIH Phuket remains on track for a Sep 27 opening, while Bangladesh expansion and potential entry into Iraq offer new growth opportunities. We maintain BUY with a target price of Bt240.00, supported by strong patient demand and cost discipline.
Company Update | PTT (PTT TB/BUY/Bt38.25/Target: Bt48.00)
- PTT is strengthening its role as a key pillar of Thailand's energy security while expanding its global LNG trading business, targeting an increase in its LNG trading portfolio from the current 4.1mtpa to 15mtpa by 2035. PTT Group has more than Bt81.8b in outstanding government-related receivables, representing significant working capital tied up while it awaits reimbursement. We forecast a 2026 dividend of Bt3.00/share, based on a 60% dividend payout ratio. Maintain BUY; target price: Bt48.00.
What’s Inside
Company Update | Bangkok Dusit Medical Services (BDMS TB/BUY/Bt20.95/Target: Bt27.00)
- BDMS delivered a positive analyst meeting, with revenue growth gaining momentum from 3% yoy in Oct 26 to 5% in 1H Nov 26, driven by both Thai and foreign patients. Strong demand from US, European and Myanmar patients offset weakness in Middle Eastern patients. Management targets flattish yoy EBITDA margins of 24% in 4Q26, supported by economies of scale. Investments in biotech and AI offer long-term growth opportunities. We maintain BUY with a target price of Bt27.00.
Company Update | BANPU (BANPU TB/HOLD/Bt13.65/Target: Bt15.00)
- Coal prices are expected to face increasing supply-side pressure in 2027. However, Henry Hub prices should remain supported by seasonal demand and rising demand from Asia. We maintain a positive view on BANPU’s acquisition of additional US gas assets, which should enhance operational synergies and support long-term growth. Maintain HOLD. Target price: Bt15.00.
Company Update | Srisawad Corporation (SAWAD TB/BUY/Bt22.00/Target: Bt35.00)
- We came away from SAWAD’s analyst meeting with a neutral view. Management guided that the portfolio quality should be healthy in 4Q26 as debt collection remains on track. Management guided that the loan portfolio in 4Q26 should grow at a similar rate to 3Q26 due to seasonality. Therefore, we maintain our loan growth forecast of 4.4% yoy in 2026 and expect the company to miss its 2026 loan growth target. Maintain BUY with a target price of Bt35.00.
Top Stories
Strategy | 3Q26 Result Wrap-up
- The SET Index’s 3Q26 earnings are in line with expectation, with 2026-27F forecasts largely unchanged. However, earnings revisions varied across sectors, with downward revisions in electronics from raw material shortages, property from pressured gross margin, and banking. These downward revisions were offset by an upward revision in the utilities sector. We maintain a neutral stance, with our 2026 SET target unchanged at 1,818 points under the earnings yield gap approach. Top picks are AWC, BH, BJC, CREDIT, GLOBAL, HANA, and KBANK.
Company Update | Berli Jucker (BJC TB/BUY/Bt20.30/Target: Bt24.50)
- We attended BJC’s analyst meeting on 18 November and came away with a more bullish view. Management expects the business restructuring to generate Bt1.3b in cost savings. If the company achieves its cost-saving target as guided, 2027 earnings could be 11% above our forecast, implying a Bt2.60 upside to our target price. Maintain BUY with a target price of Bt24.50, based on 2027F PE of 17x.
Company Update | Bumrungrad Hospital (BH TB/BUY/Bt193.00/Target: Bt240.00)
- BH delivered a positive analyst meeting, with Middle Eastern patient inflows remaining strong despite the normalisation of Qatar revenue. Although 4Q26 revenue growth is guided to be flattish yoy, earnings should continue growing, supported by cost controls and BOI tax benefits. BIH Phuket remains on track for a Sep 27 opening, while Bangladesh expansion and potential entry into Iraq offer new growth opportunities. We maintain BUY with a target price of Bt240.00, supported by strong patient demand and cost discipline.
Company Update | PTT (PTT TB/BUY/Bt38.25/Target: Bt48.00)
- PTT is strengthening its role as a key pillar of Thailand's energy security while expanding its global LNG trading business, targeting an increase in its LNG trading portfolio from the current 4.1mtpa to 15mtpa by 2035. PTT Group has more than Bt81.8b in outstanding government-related receivables, representing significant working capital tied up while it awaits reimbursement. We forecast a 2026 dividend of Bt3.00/share, based on a 60% dividend payout ratio. Maintain BUY; target price: Bt48.00.
What’s Inside
Company Update | Bangkok Dusit Medical Services (BDMS TB/BUY/Bt20.95/Target: Bt27.00)
- BDMS delivered a positive analyst meeting, with revenue growth gaining momentum from 3% yoy in Oct 26 to 5% in 1H Nov 26, driven by both Thai and foreign patients. Strong demand from US, European and Myanmar patients offset weakness in Middle Eastern patients. Management targets flattish yoy EBITDA margins of 24% in 4Q26, supported by economies of scale. Investments in biotech and AI offer long-term growth opportunities. We maintain BUY with a target price of Bt27.00.
Company Update | BANPU (BANPU TB/HOLD/Bt13.65/Target: Bt15.00)
- Coal prices are expected to face increasing supply-side pressure in 2027. However, Henry Hub prices should remain supported by seasonal demand and rising demand from Asia. We maintain a positive view on BANPU’s acquisition of additional US gas assets, which should enhance operational synergies and support long-term growth. Maintain HOLD. Target price: Bt15.00.
Company Update | Srisawad Corporation (SAWAD TB/BUY/Bt22.00/Target: Bt35.00)
- We came away from SAWAD’s analyst meeting with a neutral view. Management guided that the portfolio quality should be healthy in 4Q26 as debt collection remains on track. Management guided that the loan portfolio in 4Q26 should grow at a similar rate to 3Q26 due to seasonality. Therefore, we maintain our loan growth forecast of 4.4% yoy in 2026 and expect the company to miss its 2026 loan growth target. Maintain BUY with a target price of Bt35.00.
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


