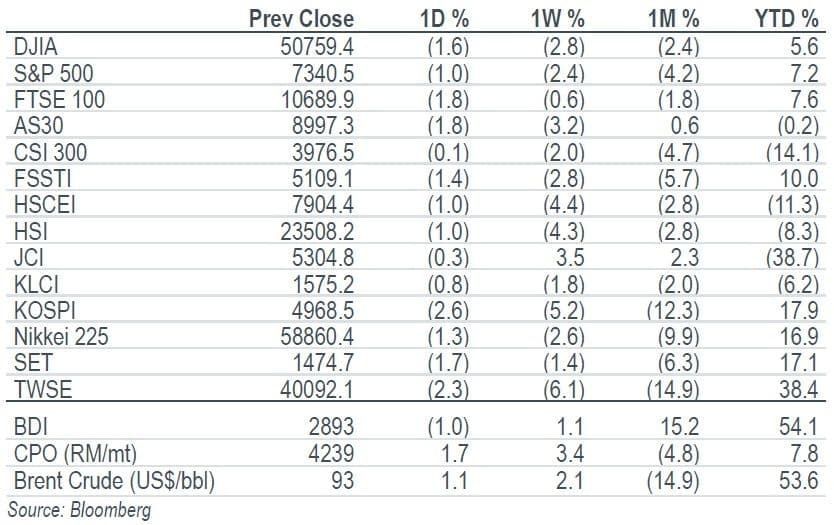
Key Indices

Top Stories
Strategy | AI Export Curbs: Near-Term Noise, Long-Term Opportunity
- We expect limited earnings impact from US AI chip restrictions, with potential delays rather than cancellations of data centre investments. Utilities should see minimal impact, while industrial estates may face slower land transfers and construction projects should remain largely unaffected. Electronics stocks may face short-term sentiment pressure. We view recent share price weakness as an opportunity to accumulate GULF, WHA, STECON, DELTA and HANA.
Company Update | HANA (Thailand) (HANA TB/BUY/Bt43.50/Target: Bt56.00)
- HANA reported a 3Q26 net profit of Bt693m (+4,588% yoy, +112% qoq), beating expectation by roughly 100%. HANA’s AI exposure reached 6% of 3Q26 total revenue. It has signed a third contract for a solid-state cooling project and a substantial new customer for IC, which is expected to start in 3Q27. With a high IC utilisation rate at 72% and PCBA utilisation nearly at full capacity, management guides for aggressive capex in 2027. Maintain BUY. Target price: Bt56.00.
Company Update | Minor International (MINT TB/HOLD/Bt22.00/Target: Bt21.00)
- The tone during MINT’s analyst meeting was neutral, with the hotel and food businesses expected to see positive momentum in 4Q26. Management is prioritising margin protection through cost control and operational efficiency. However, high interest expenses remain a key earnings headwind, exacerbated by rising European rates and elevated debt following perpetual bond conversions. The delayed REIT launch and gradual asset rotation limit near-term deleveraging benefits. We expect 2026 profit growth to fall short of guidance. Maintain HOLD. Target price: Bt21.00.
Company Update | PTT Global Chemical (PTTGC TB/HOLD/Bt39.20/Target: Bt45.00)
- PTTGC remains confident about achieving the targeted synergies value from the JVCo and expects the transaction to be completed by 2H27. In 2027, the key earnings driver will be higher combined production capacity. However, declining olefins spreads amid the persistent oversupply remain a key risk. This is consistent with our earlier view, given our more cautious outlook on the petrochemical sector. We maintain our view that the petrochemical sector will remain weak on continued oversupply. Maintain HOLD. Target price: Bt45.00.
What’s Inside
Company Update | Bangkok Commercial Asset Management (BAM TB/HOLD/Bt6.30/Target: Bt7.20)
- We came away from BAM’s analyst meeting with a slightly positive view. The CEO guided for a big jump in bottom line in 4Q26, to be reported at around Bt1.2b-1.4b. BAM recently received board approval to establish a new JV AMC with KTAH. Management expects to obtain BOT approval in 1Q27 and complete its first NPL acquisition by 2Q27. Management expects the new JV to contribute Bt50m-75m in net profit in 2027. Maintain HOLD with a target price of Bt7.20.
Company Update | Krungthai Card (KTC TB/BUY/Bt36.00/Target: Bt50.00)
- We came away from KTC’s analyst meeting with a slightly positive view. Management announced its 2027 financial targets, which are similar to those of 2026, except for credit card spending, which is targeted to grow 8-10% in 2027 (vs 5% in 2026). KTC guided that credit costs should be around 5% in 2027. We should see lower credit costs and an NPL ratio following the removal of KTB Leasing from KTC's consolidated balance sheet. Maintain BUY; target price: Bt50.00.
Company Update | Thanachart Capital (TCAP TB/HOLD/Bt78.75/Target: Bt90.00)
- We came away from TCAP’s analyst meeting with a neutral view. The CEO remains conservative amid slow economic growth and is preparing for various uncertainties. TCAP evaluated the impact of flooding in Bangkok and its vicinity in late-Sep 26 and guided that the impact should be small. There should be limited downside, supported by the share buyback programme. TCAP had repurchased 2.7m shares (or 2.6% of the total shares). Maintain HOLD with a target price of Bt90.00.
Top Stories
Strategy | AI Export Curbs: Near-Term Noise, Long-Term Opportunity
- We expect limited earnings impact from US AI chip restrictions, with potential delays rather than cancellations of data centre investments. Utilities should see minimal impact, while industrial estates may face slower land transfers and construction projects should remain largely unaffected. Electronics stocks may face short-term sentiment pressure. We view recent share price weakness as an opportunity to accumulate GULF, WHA, STECON, DELTA and HANA.
Company Update | HANA (Thailand) (HANA TB/BUY/Bt43.50/Target: Bt56.00)
- HANA reported a 3Q26 net profit of Bt693m (+4,588% yoy, +112% qoq), beating expectation by roughly 100%. HANA’s AI exposure reached 6% of 3Q26 total revenue. It has signed a third contract for a solid-state cooling project and a substantial new customer for IC, which is expected to start in 3Q27. With a high IC utilisation rate at 72% and PCBA utilisation nearly at full capacity, management guides for aggressive capex in 2027. Maintain BUY. Target price: Bt56.00.
Company Update | Minor International (MINT TB/HOLD/Bt22.00/Target: Bt21.00)
- The tone during MINT’s analyst meeting was neutral, with the hotel and food businesses expected to see positive momentum in 4Q26. Management is prioritising margin protection through cost control and operational efficiency. However, high interest expenses remain a key earnings headwind, exacerbated by rising European rates and elevated debt following perpetual bond conversions. The delayed REIT launch and gradual asset rotation limit near-term deleveraging benefits. We expect 2026 profit growth to fall short of guidance. Maintain HOLD. Target price: Bt21.00.
Company Update | PTT Global Chemical (PTTGC TB/HOLD/Bt39.20/Target: Bt45.00)
- PTTGC remains confident about achieving the targeted synergies value from the JVCo and expects the transaction to be completed by 2H27. In 2027, the key earnings driver will be higher combined production capacity. However, declining olefins spreads amid the persistent oversupply remain a key risk. This is consistent with our earlier view, given our more cautious outlook on the petrochemical sector. We maintain our view that the petrochemical sector will remain weak on continued oversupply. Maintain HOLD. Target price: Bt45.00.
What’s Inside
Company Update | Bangkok Commercial Asset Management (BAM TB/HOLD/Bt6.30/Target: Bt7.20)
- We came away from BAM’s analyst meeting with a slightly positive view. The CEO guided for a big jump in bottom line in 4Q26, to be reported at around Bt1.2b-1.4b. BAM recently received board approval to establish a new JV AMC with KTAH. Management expects to obtain BOT approval in 1Q27 and complete its first NPL acquisition by 2Q27. Management expects the new JV to contribute Bt50m-75m in net profit in 2027. Maintain HOLD with a target price of Bt7.20.
Company Update | Krungthai Card (KTC TB/BUY/Bt36.00/Target: Bt50.00)
- We came away from KTC’s analyst meeting with a slightly positive view. Management announced its 2027 financial targets, which are similar to those of 2026, except for credit card spending, which is targeted to grow 8-10% in 2027 (vs 5% in 2026). KTC guided that credit costs should be around 5% in 2027. We should see lower credit costs and an NPL ratio following the removal of KTB Leasing from KTC's consolidated balance sheet. Maintain BUY; target price: Bt50.00.
Company Update | Thanachart Capital (TCAP TB/HOLD/Bt78.75/Target: Bt90.00)
- We came away from TCAP’s analyst meeting with a neutral view. The CEO remains conservative amid slow economic growth and is preparing for various uncertainties. TCAP evaluated the impact of flooding in Bangkok and its vicinity in late-Sep 26 and guided that the impact should be small. There should be limited downside, supported by the share buyback programme. TCAP had repurchased 2.7m shares (or 2.6% of the total shares). Maintain HOLD with a target price of Bt90.00.
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


