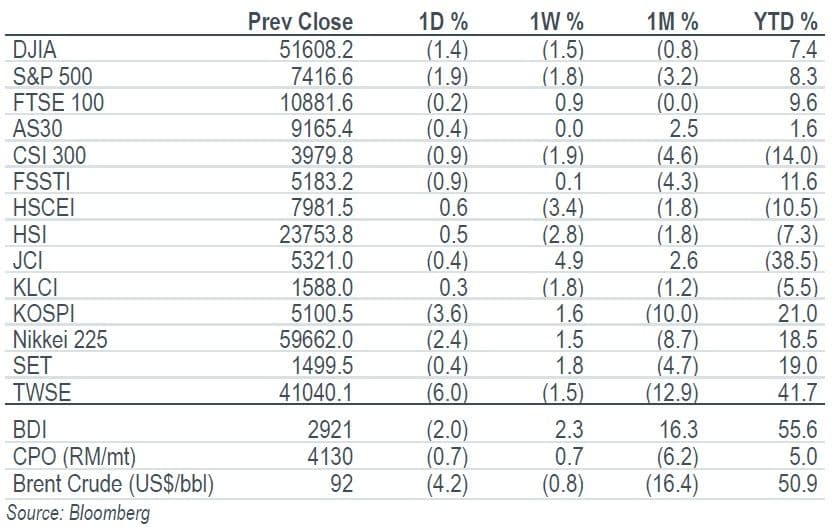
Key Indices
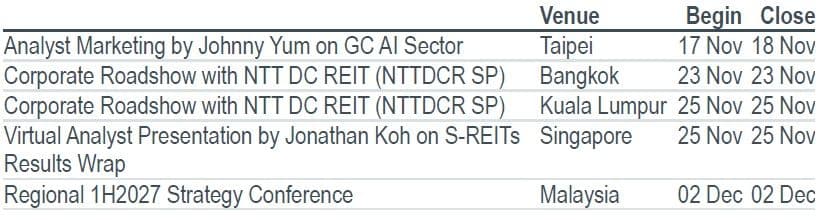
Top Stories
Company Results | Amata Corporation (AMATA TB/BUY/Bt27.10/Target: Bt38.00)
- AMATA reported 3Q26 net profit of Bt1.28b (+12% yoy, -19% qoq), beating consensus by 47%. Revenue declined 15% yoy to Bt3.6b due to lower land transfers. Gross margin improved to 53.5%, supported by higher ASPs and a favourable land transfer mix. Earnings also benefitted from a Bt112m gain on investment disposal. AMATA exchanged its Bien Hoa commercial complex for 18 hectares of industrial land. Maintain BUY with an unchanged target price of Bt38.00.
Company Results | Srisawad Corporation (SAWAD TB/BUY/Bt22.30/Target: Bt35.00)
- SAWAD reported 3Q26 earnings of Bt1.43b, up 8% yoy and 2% qoq. The results were in line with consensus estimates but beat our forecasts by 9% due to the lower-than expected opex. In 9M26, the loan portfolio grew only 3% yoy. SAWAD’s provision expenses increased 39% yoy and 38% qoq in 3Q26 in order to support the expansion of the title loan portfolio. NPL ratio stablised qoq at 4.0% in 3Q26. Maintain BUY with a target price of Bt35.00.
Company Update | Central Pattana (CPN TB/BUY/Bt61.75/Target: Bt80.00)
- CPN’s announcement of additional investment in Central Embassy is slightly positive. The total project value of Central Embassy is Bt83b, and will be financed through 70% debt and 30% equity. We estimate this could bring 0.4% upside to CPN’s earnings in 2028 and 0.6% in 2029. Maintain BUY with a target price of Bt80.00.
Company Update | OSOTSPA (OSP TB/BUY/Bt18.75/Target: Bt22.00)
- OSP reported a 3Q26 core profit of Bt875m (+24.9% yoy, -20.5% qoq). International energy drink and personal care sales continued to show a positive momentum, while gross profit margin remained resilient. We expect 4Q26 earnings to increase yoy but remain broadly flat qoq, supported by seasonal strength in personal care sales and a recovery in international markets, which should partially offset the impact of higher raw material costs. Maintain BUY with a target price of Bt22.00.
What’s Inside
Company Results | Bangkok Chain Hospital (BCH TB/BUY/Bt11.00/Target: Bt13.00)
- BCH reported core profit of Bt409m (+28.2% yoy, +19.2% qoq), beating expectations on stronger patient volumes and improved margins. The SSO’s 3-4% capitation rate increase from Jan 27 should support 2027 earnings. Flooding had minimal impact, while newly acquired KIH Ubon has turned profitable. We expect solid 4Q26 earnings, supported by a low base in 4Q25, higher SSO reimbursement and continued improvement at KIH Ubon. Maintain BUY with a target price of Bt13.00.
Company Results | CH. Karnchang (CK TB/BUY/Bt17.80/Target: Bt28.00)
- CK reported 3Q26 net profit of Bt1.29b (-26% yoy, +61% qoq), in line with expectations. Construction revenue grew 6% yoy and 2% qoq to Bt11.6b, while overall gross margin declined to 7.68% due to higher construction costs. Share of profit from associates improved 54% qoq to Bt720m. CK also recognised a Bt300m gain from the disposal of BEM shares. We maintain BUY with an unchanged target price of Bt28.00.
Company Results | Electricity Generating Company (EGCO TB/HOLD/Bt132.50/Target: Bt135.00)
- EGCO reported 3Q26 net profit of Bt5.99b, supported by a Bt1.67b gain from asset disposals. Core profit rebounded to Bt1.62b (+92% yoy), driven by stronger contributions from Paju and other power assets. However, 9M26 core profit declined 39% yoy. We expect earnings to stabilise in 4Q26, with potential upside from asset acquisitions in 2027. Maintain HOLD with a target price of Bt135.00.
Company Results | Supalai (SPALI TB/BUY/Bt15.50/Target: Bt16.25)
- SPALI reported 3Q26 net profit of Bt833m, in line with consensus but below our forecast, pressured by weaker property transfers and persistent margin pressure. 9M26 earnings accounted for 60% of our previous full-year forecast. We cut our 2026-27 earnings estimate by 9.9% and 8.6%, respectively, reflecting softer margins and delayed transfers. Nevertheless, we maintain BUY with a lower target price of Bt16.25, (from Bt17.50), supported by strong fundamentals, a healthy balance sheet, Australian operations, and an attractive 8.4% dividend yield.
Company Update | Muangthai Capital (MTC TB/BUY/Bt30.50/Target: Bt50.00)
- We came away from MTC’s meeting with a neutral view. The CEO guided that loan growth should be around 7% yoy in 2026 and expects the loan portfolio to grow around 8% yoy in 2027. MTC expects the company to achieve its 2026 credit cost target of 260bp. Meanwhile, the CEO guided that the 2027 credit cost should be around 260bp due to the slow economic recovery outlook. Maintain BUY with an unchanged target price of Bt50.00.
Company Update | Tidlor Holdings (TIDLOR TB/BUY/Bt16.90/Target: Bt25.00)
- We attended TIDLOR’s 3Q26 analyst meeting on 9 Nov 26 and came away with a neutral view with no changes in key financial targets. Management expects loan growth momentum in Oct-Nov 26 to remain stable qoq and annual loan growth of 5-10% over the next 1-2 years. Management expects credit costs to increase qoq in 4Q26, potentially reaching around 2.5%, reflecting prudent provisioning. We maintain BUY with an unchanged target price of Bt25.00.
Company Update | The Erawan Group (ERW TB/BUY/Bt3.68/Target: Bt4.80)
- ERW hosted a positive analyst meeting, targeting high single-digit RevPar growth in 2027, driven by ADR improvement after the Grand Hyatt renovation. For 4Q26, room revenue is expected to grow 6% yoy, supported by high-season demand, recovering Chinese arrivals and long-haul tourists. The 2026 revenue growth target remains at 6% yoy. Lower financing costs should further support earnings. We maintain BUY with a target price of Bt4.80, with declining interest expenses as key catalysts.
Top Stories
Company Results | Amata Corporation (AMATA TB/BUY/Bt27.10/Target: Bt38.00)
- AMATA reported 3Q26 net profit of Bt1.28b (+12% yoy, -19% qoq), beating consensus by 47%. Revenue declined 15% yoy to Bt3.6b due to lower land transfers. Gross margin improved to 53.5%, supported by higher ASPs and a favourable land transfer mix. Earnings also benefitted from a Bt112m gain on investment disposal. AMATA exchanged its Bien Hoa commercial complex for 18 hectares of industrial land. Maintain BUY with an unchanged target price of Bt38.00.
Company Results | Srisawad Corporation (SAWAD TB/BUY/Bt22.30/Target: Bt35.00)
- SAWAD reported 3Q26 earnings of Bt1.43b, up 8% yoy and 2% qoq. The results were in line with consensus estimates but beat our forecasts by 9% due to the lower-than expected opex. In 9M26, the loan portfolio grew only 3% yoy. SAWAD’s provision expenses increased 39% yoy and 38% qoq in 3Q26 in order to support the expansion of the title loan portfolio. NPL ratio stablised qoq at 4.0% in 3Q26. Maintain BUY with a target price of Bt35.00.
Company Update | Central Pattana (CPN TB/BUY/Bt61.75/Target: Bt80.00)
- CPN’s announcement of additional investment in Central Embassy is slightly positive. The total project value of Central Embassy is Bt83b, and will be financed through 70% debt and 30% equity. We estimate this could bring 0.4% upside to CPN’s earnings in 2028 and 0.6% in 2029. Maintain BUY with a target price of Bt80.00.
Company Update | OSOTSPA (OSP TB/BUY/Bt18.75/Target: Bt22.00)
- OSP reported a 3Q26 core profit of Bt875m (+24.9% yoy, -20.5% qoq). International energy drink and personal care sales continued to show a positive momentum, while gross profit margin remained resilient. We expect 4Q26 earnings to increase yoy but remain broadly flat qoq, supported by seasonal strength in personal care sales and a recovery in international markets, which should partially offset the impact of higher raw material costs. Maintain BUY with a target price of Bt22.00.
What’s Inside
Company Results | Bangkok Chain Hospital (BCH TB/BUY/Bt11.00/Target: Bt13.00)
- BCH reported core profit of Bt409m (+28.2% yoy, +19.2% qoq), beating expectations on stronger patient volumes and improved margins. The SSO’s 3-4% capitation rate increase from Jan 27 should support 2027 earnings. Flooding had minimal impact, while newly acquired KIH Ubon has turned profitable. We expect solid 4Q26 earnings, supported by a low base in 4Q25, higher SSO reimbursement and continued improvement at KIH Ubon. Maintain BUY with a target price of Bt13.00.
Company Results | CH. Karnchang (CK TB/BUY/Bt17.80/Target: Bt28.00)
- CK reported 3Q26 net profit of Bt1.29b (-26% yoy, +61% qoq), in line with expectations. Construction revenue grew 6% yoy and 2% qoq to Bt11.6b, while overall gross margin declined to 7.68% due to higher construction costs. Share of profit from associates improved 54% qoq to Bt720m. CK also recognised a Bt300m gain from the disposal of BEM shares. We maintain BUY with an unchanged target price of Bt28.00.
Company Results | Electricity Generating Company (EGCO TB/HOLD/Bt132.50/Target: Bt135.00)
- EGCO reported 3Q26 net profit of Bt5.99b, supported by a Bt1.67b gain from asset disposals. Core profit rebounded to Bt1.62b (+92% yoy), driven by stronger contributions from Paju and other power assets. However, 9M26 core profit declined 39% yoy. We expect earnings to stabilise in 4Q26, with potential upside from asset acquisitions in 2027. Maintain HOLD with a target price of Bt135.00.
Company Results | Supalai (SPALI TB/BUY/Bt15.50/Target: Bt16.25)
- SPALI reported 3Q26 net profit of Bt833m, in line with consensus but below our forecast, pressured by weaker property transfers and persistent margin pressure. 9M26 earnings accounted for 60% of our previous full-year forecast. We cut our 2026-27 earnings estimate by 9.9% and 8.6%, respectively, reflecting softer margins and delayed transfers. Nevertheless, we maintain BUY with a lower target price of Bt16.25, (from Bt17.50), supported by strong fundamentals, a healthy balance sheet, Australian operations, and an attractive 8.4% dividend yield.
Company Update | Muangthai Capital (MTC TB/BUY/Bt30.50/Target: Bt50.00)
- We came away from MTC’s meeting with a neutral view. The CEO guided that loan growth should be around 7% yoy in 2026 and expects the loan portfolio to grow around 8% yoy in 2027. MTC expects the company to achieve its 2026 credit cost target of 260bp. Meanwhile, the CEO guided that the 2027 credit cost should be around 260bp due to the slow economic recovery outlook. Maintain BUY with an unchanged target price of Bt50.00.
Company Update | Tidlor Holdings (TIDLOR TB/BUY/Bt16.90/Target: Bt25.00)
- We attended TIDLOR’s 3Q26 analyst meeting on 9 Nov 26 and came away with a neutral view with no changes in key financial targets. Management expects loan growth momentum in Oct-Nov 26 to remain stable qoq and annual loan growth of 5-10% over the next 1-2 years. Management expects credit costs to increase qoq in 4Q26, potentially reaching around 2.5%, reflecting prudent provisioning. We maintain BUY with an unchanged target price of Bt25.00.
Company Update | The Erawan Group (ERW TB/BUY/Bt3.68/Target: Bt4.80)
- ERW hosted a positive analyst meeting, targeting high single-digit RevPar growth in 2027, driven by ADR improvement after the Grand Hyatt renovation. For 4Q26, room revenue is expected to grow 6% yoy, supported by high-season demand, recovering Chinese arrivals and long-haul tourists. The 2026 revenue growth target remains at 6% yoy. Lower financing costs should further support earnings. We maintain BUY with a target price of Bt4.80, with declining interest expenses as key catalysts.
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


