Company Coverage
PTT (PTT TB) - 3Q26 Results Preview: Earnings To Fall qoq On Seasonal Weakness
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt38.50
Bt48.00
+23.87%
Bt45.00
Analyst
Analyst
Highlights
- We expect 3Q26 net profit to decline qoq due to seasonal factors, including lower gas demand and reduced sales volumes from the gas separation plant business following the maintenance shutdown of one gas separation plant.
- The Genesis project continues to progress, albeit slightly behind the original schedule. PTT expects to finalise the project's details within 4Q26.
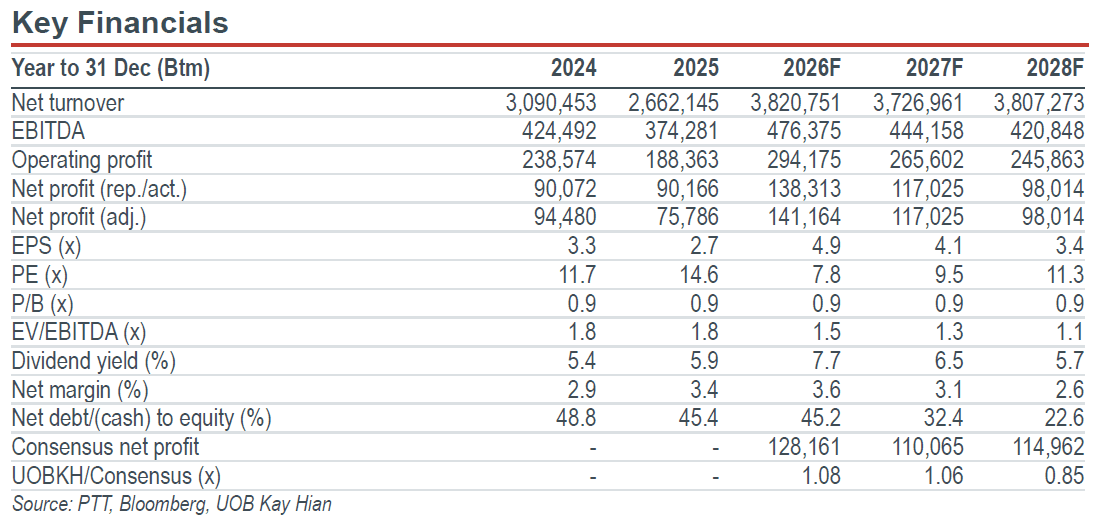
- We forecast a 2026 dividend of Bt3.00/share. Maintain BUY, with a target price of Bt48.00 (previously Bt45.00).
Analysis
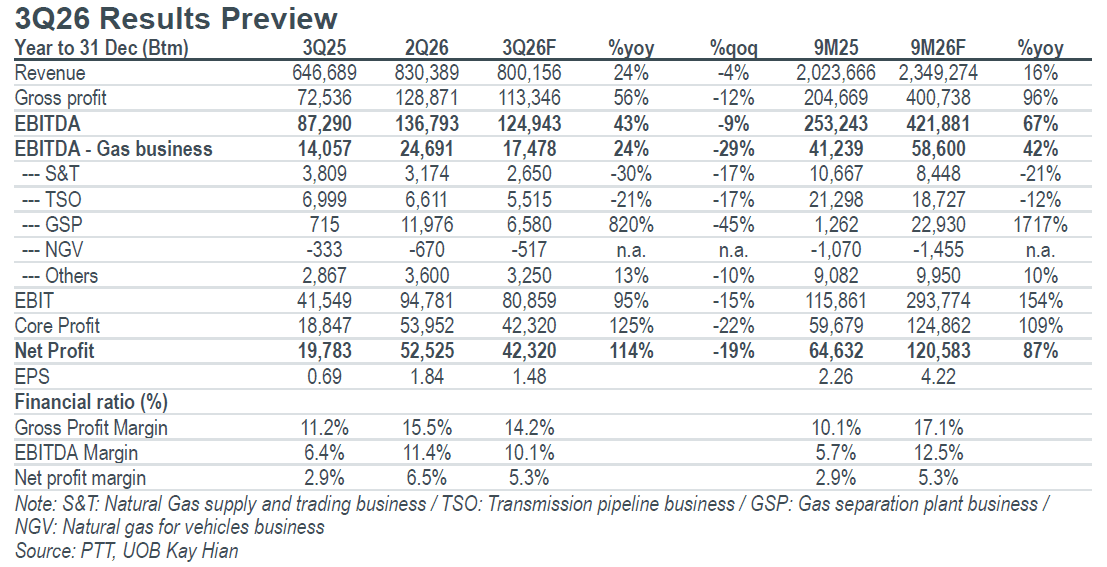
- 3Q26 net profit expected to decline qoq. We expect PTT to report 3Q26 net profit of Bt42.32b, down 19% qoq but up 114% yoy. The qoq decline is primarily attributable to seasonal weakness in gas demand from the power generation sector and lower sales volumes of gas separation products following the maintenance shutdown of gas separation plant no. 6. However, higher equity contributions from subsidiaries and affiliates, particularly Thai Oil (TOP), PTT Oil and Retail (OR), and IRPC, should help cushion the downside to 3Q26 earnings.
- Gas business EBITDA to decline on seasonal weakness. We estimate gas business EBITDA at Bt17.48b, down 29% qoq but up 24% yoy, driven by: a) Natural Gas Supply and Trading (S&T), whose gas sales volume is expected to reach 3,844 million standard cubic feet per day (MMSCFD), down 8.91% qoq but up 2.59% yoy, reflecting lower gas demand. A slight qoq increase in gas costs is also expected to weigh on S&T’s EBITDA, which we forecast at Bt2.65b, down 17% qoq.
Highlights
- We expect 3Q26 net profit to decline qoq due to seasonal factors, including lower gas demand and reduced sales volumes from the gas separation plant business following the maintenance shutdown of one gas separation plant.
- The Genesis project continues to progress, albeit slightly behind the original schedule. PTT expects to finalise the project's details within 4Q26.
- We forecast a 2026 dividend of Bt3.00/share. Maintain BUY, with a target price of Bt48.00 (previously Bt45.00).
Analysis
- 3Q26 net profit expected to decline qoq. We expect PTT to report 3Q26 net profit of Bt42.32b, down 19% qoq but up 114% yoy. The qoq decline is primarily attributable to seasonal weakness in gas demand from the power generation sector and lower sales volumes of gas separation products following the maintenance shutdown of gas separation plant no. 6. However, higher equity contributions from subsidiaries and affiliates, particularly Thai Oil (TOP), PTT Oil and Retail (OR), and IRPC, should help cushion the downside to 3Q26 earnings.
- Gas business EBITDA to decline on seasonal weakness. We estimate gas business EBITDA at Bt17.48b, down 29% qoq but up 24% yoy, driven by: a) Natural Gas Supply and Trading (S&T), whose gas sales volume is expected to reach 3,844 million standard cubic feet per day (MMSCFD), down 8.91% qoq but up 2.59% yoy, reflecting lower gas demand. A slight qoq increase in gas costs is also expected to weigh on S&T’s EBITDA, which we forecast at Bt2.65b, down 17% qoq.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt38.50
Bt48.00
+23.87%
Bt45.00
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

8 Oct 2026
PTT Exploration & Production (PTTEP TB): 3Q26 Net Profit To Decline qoq On Lower Sales And Oil Hedging Loss

29 Oct 2026
Siam Cement (SCC TB): 3Q26: Earnings Miss Expectations As Chemical Business Records Losses

21 Oct 2026
Osotspa (OSP TB): 3Q26 Results Preview: Margins Expected To Remain Resilient
Our latest research

9 Nov 2026
CP Axtra (CPAXT TB): 3Q26: Earnings Trough; Store Closures to Boost Profit

9 Nov 2026
KCE (Thailand) (KCE TB): Management Guides A Strong 4Q26-2027 Outlook; More Attractive Valuation Presents Trading Opportunities
9 Nov 2026