Company Coverage
Central Pattana (CPN TB): Acquisition Of Additional Stake In Central Embassy
BUY (Maintained)
Current price:
Target price:
Upside:
Bt61.75
Bt80.00
29.55%
Analyst
Highlights
- CPN’s announcement of its additional investment in Central Embassy is slightly positive.
- The total project value of Central Embassy is Bt83b, and will be financed through 70% debt and 30% equity.
- We estimate upside to CPN's earnings of 0.4% in 2028 and 0.6% in 2029.
- Maintain BUY with a target price of Bt80.00.
Analysis
- Transaction is slightly positive. We see CPN’s announcement of additional investment in the Central Embassy project as slightly positive.
- Transaction details. The first transaction involves CE Holding, a JV between CPN (49%) and Central Group (51%), acquiring a 49% stake in Central and Hongkong Land (CHKL) from Hongkong Land (HKL). Following the transaction, CE Holding will own 100% of CHKL and the Central Embassy 2 (CE2) project. The second transaction involves CHKL entering into a 30-year lease for the Central Embassy shopping mall portion of Central Embassy 1 (CE1), with the lease agreement transaction expected to be executed in 2Q27. Following both transactions, CPN's effective stake in CE1 will increase from 0% to 49%, while its effective stake in CE2 will increase from 25% to 49%.
- Project value and funding. The total project value of Central Embassy, comprising CE1 (the shopping mall under the lease, excluding Park Hyatt) and CE2, is estimated at Bt83b, financed through 70% debt and 30% equity. The project IRR is estimated at around 9%, while the equity IRR is expected to reach double-digits.
- Valuation. a) CE1: The company did not disclose the lease agreement value. However, based on our preliminary assessment, we estimate the lease value at around Bt27.8b, assuming a value equivalent to 1.5x the project's initial investment cost. The premium reflects CE1's proven success as an established brownfield project, lower execution risk, and project IRR comparable to previous M&A transactions; b) CE2: CE Holding acquired the stake at a price equivalent to HKL's historical investment, which we estimate at approximately Bt10b.
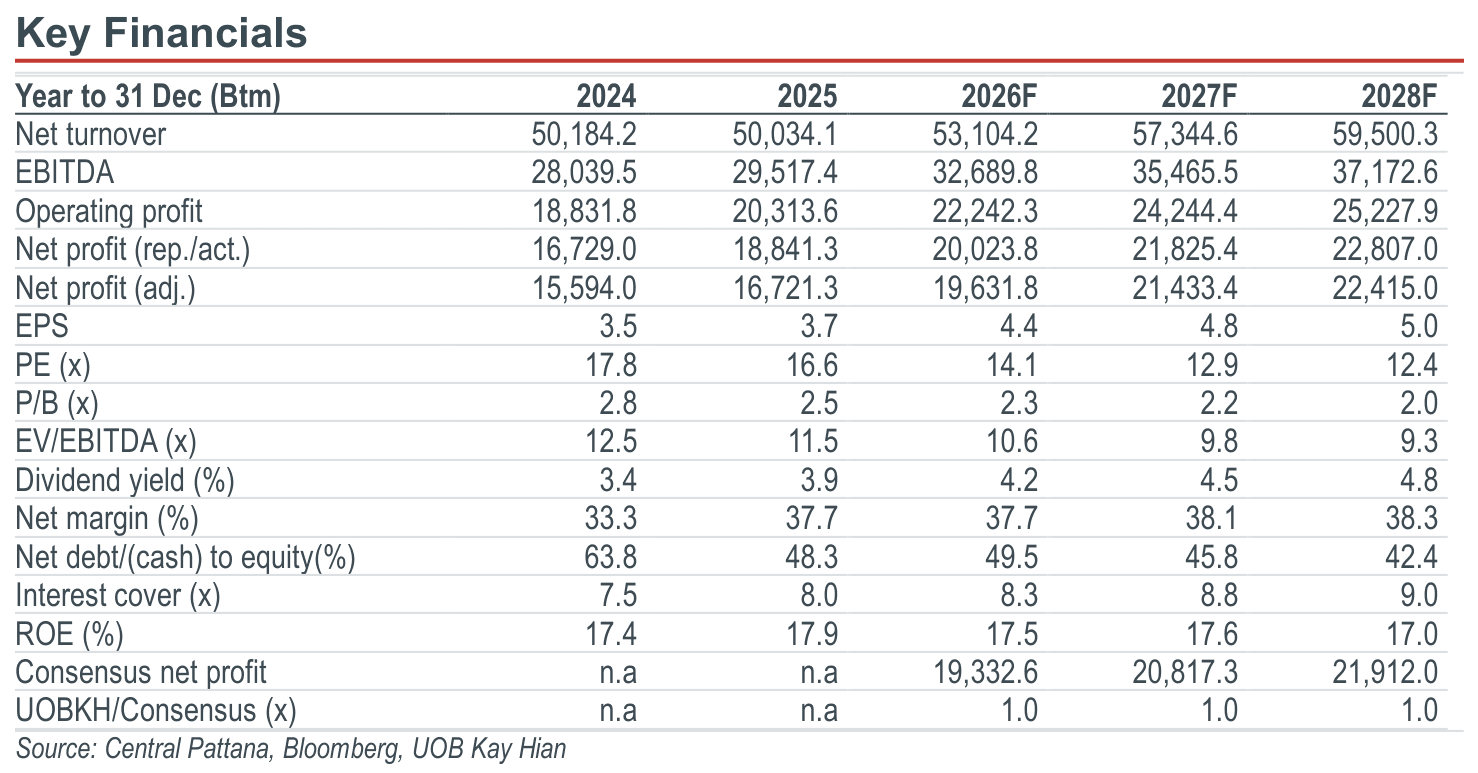
- Slightly positive to earnings. CPN will continue to recognise its investment in CE Holding under the equity method, with no impact on its IBD/E ratio. We estimate upside to CPN's earnings of 0.4% in 2028 and 0.6% in 2029, based on the following assumptions: a) project value of Bt27.8b for CE1 and Bt55.2b for CE2, approximately 3x the land value, and b) CE1 revenue growth of 10% and EBIT margin of 45%.
Highlights
- CPN’s announcement of its additional investment in Central Embassy is slightly positive.
- The total project value of Central Embassy is Bt83b, and will be financed through 70% debt and 30% equity.
- We estimate upside to CPN's earnings of 0.4% in 2028 and 0.6% in 2029.
- Maintain BUY with a target price of Bt80.00.
Analysis
- Transaction is slightly positive. We see CPN’s announcement of additional investment in the Central Embassy project as slightly positive.
- Transaction details. The first transaction involves CE Holding, a JV between CPN (49%) and Central Group (51%), acquiring a 49% stake in Central and Hongkong Land (CHKL) from Hongkong Land (HKL). Following the transaction, CE Holding will own 100% of CHKL and the Central Embassy 2 (CE2) project. The second transaction involves CHKL entering into a 30-year lease for the Central Embassy shopping mall portion of Central Embassy 1 (CE1), with the lease agreement transaction expected to be executed in 2Q27. Following both transactions, CPN's effective stake in CE1 will increase from 0% to 49%, while its effective stake in CE2 will increase from 25% to 49%.
- Project value and funding. The total project value of Central Embassy, comprising CE1 (the shopping mall under the lease, excluding Park Hyatt) and CE2, is estimated at Bt83b, financed through 70% debt and 30% equity. The project IRR is estimated at around 9%, while the equity IRR is expected to reach double-digits.
- Valuation. a) CE1: The company did not disclose the lease agreement value. However, based on our preliminary assessment, we estimate the lease value at around Bt27.8b, assuming a value equivalent to 1.5x the project's initial investment cost. The premium reflects CE1's proven success as an established brownfield project, lower execution risk, and project IRR comparable to previous M&A transactions; b) CE2: CE Holding acquired the stake at a price equivalent to HKL's historical investment, which we estimate at approximately Bt10b.
- Slightly positive to earnings. CPN will continue to recognise its investment in CE Holding under the equity method, with no impact on its IBD/E ratio. We estimate upside to CPN's earnings of 0.4% in 2028 and 0.6% in 2029, based on the following assumptions: a) project value of Bt27.8b for CE1 and Bt55.2b for CE2, approximately 3x the land value, and b) CE1 revenue growth of 10% and EBIT margin of 45%.
BUY (Maintained)
Current price:
Target price:
Upside:
Bt61.75
Bt80.00
29.55%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

19 Nov 2026
Berli Jucker (BJC TB): Strongly Positive Takeaways from Analyst Meeting

16 Nov 2026
Ratch Group (RATCH TB): 3Q26: Earnings Rebound; Growth Story Intact

21 Oct 2026
Thai Oil (TOP TB): Strong Market GIM To Drive Robust 3Q26 Earnings
Our latest research

20 Nov 2026
Asset World Corporation (AWC TB): Outlook Remains Robust Throughout The High Travel Season

19 Nov 2026
PTT (PTT TB): Geopolitical Tightness Now, Supply Glut Ahead – PTT Ramps Up Global Trading
19 Nov 2026