Company Coverage
Asset World Corporation (AWC TB): Expect Outstanding Earnings In 3Q26
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt3.24
Bt3.90
+20.4%
Bt3.70
Analyst
Analyst
Nonpawit Vathanadachakul
Highlights
- AWC is expected to report a robust 3Q26 core profit of Bt448m (up from Bt265m in 3Q25 and Bt177m in 2Q26).
- RevPar growth in 3Q26 is expected to be strong across all hotel segments, boosted by traffic from large events and Chinese arrival recovery.
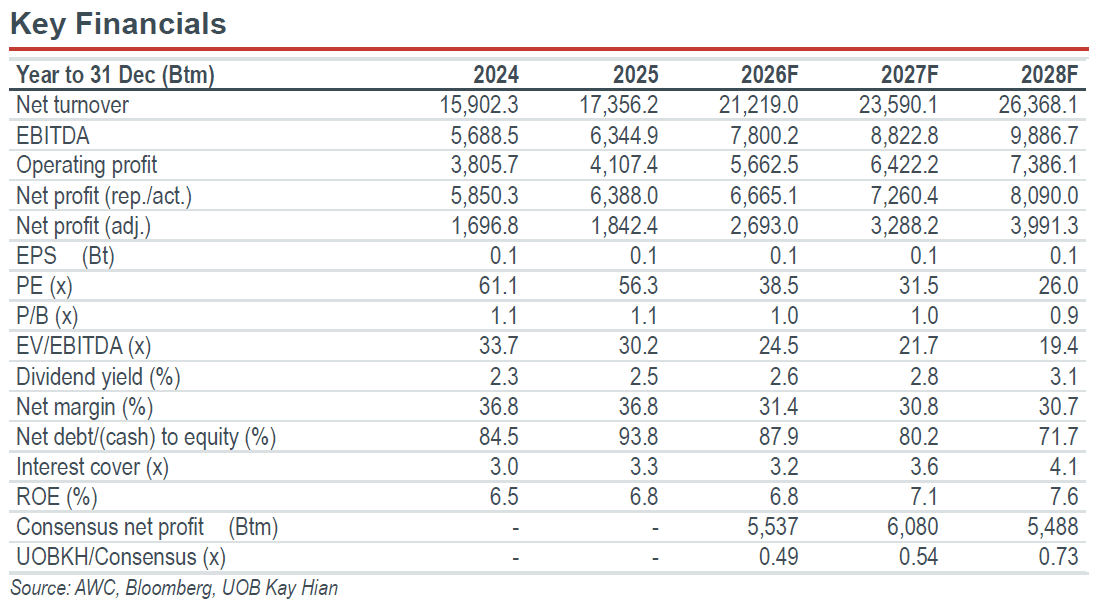
- We expect to see the strong hotel performance to continue into 4Q26 as there are large events being held in Bangkok and Pattaya. AWC remains our top pick, maintain BUY with a target price of Bt3.90 (previously Bt3.70).
Analysis
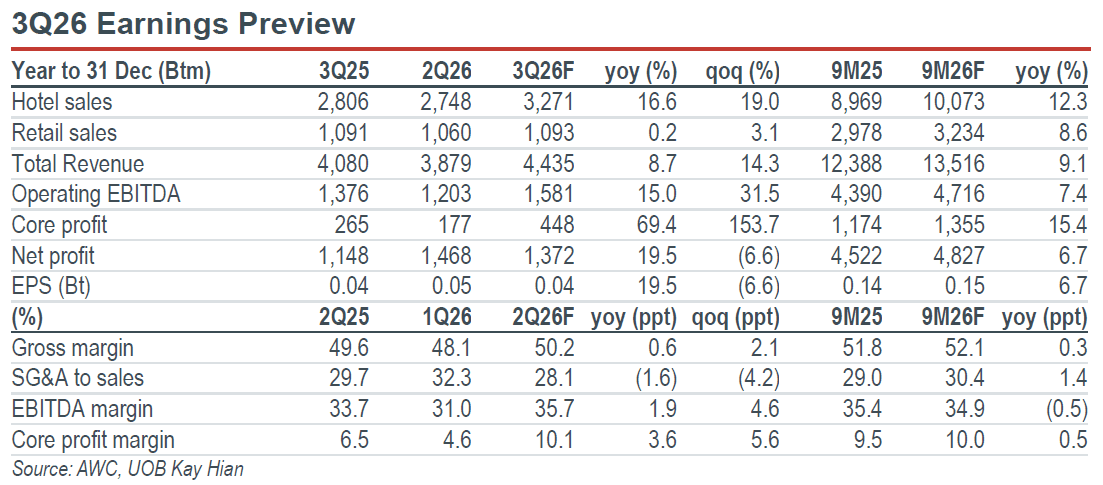
- Expect outstanding core earnings growth in 3Q26. Asset World Corporation (AWC) is expected to report a robust 3Q26 core profit of Bt448m (up from Bt265m in 3Q25 and Bt177m in 2Q26). Total revenue should be at Bt4.44b (+8.7% yoy, +14.3% qoq) with the hotel segment's revenue expected to show strong growth of 16.6% yoy. This is attributable to the overall RevPar, which is expected to surge by 25% yoy, supported by all hotel segments, contributed by the recovery of Chinese arrivals. The RevPar growth yoy for MICE hotels, Bangkok City, luxury resorts, and non-Bangkok hotels is expected to go up massively by 23%, 17%, 21%, and 35% respectively. This is expected to be a result of the increase in Chinese visitors’ revenue of 46% yoy in 3Q26. Interest expense should drop yoy but go up qoq due to increasing loan amounts. The EBITDA margins should expand yoy, supported by margin expansion of both hotel and retail businesses..
Highlights
- AWC is expected to report a robust 3Q26 core profit of Bt448m (up from Bt265m in 3Q25 and Bt177m in 2Q26).
- RevPar growth in 3Q26 is expected to be strong across all hotel segments, boosted by traffic from large events and Chinese arrival recovery.
- We expect to see the strong hotel performance to continue into 4Q26 as there are large events being held in Bangkok and Pattaya. AWC remains our top pick, maintain BUY with a target price of Bt3.90 (previously Bt3.70).
Analysis
- Expect outstanding core earnings growth in 3Q26. Asset World Corporation (AWC) is expected to report a robust 3Q26 core profit of Bt448m (up from Bt265m in 3Q25 and Bt177m in 2Q26). Total revenue should be at Bt4.44b (+8.7% yoy, +14.3% qoq) with the hotel segment's revenue expected to show strong growth of 16.6% yoy. This is attributable to the overall RevPar, which is expected to surge by 25% yoy, supported by all hotel segments, contributed by the recovery of Chinese arrivals. The RevPar growth yoy for MICE hotels, Bangkok City, luxury resorts, and non-Bangkok hotels is expected to go up massively by 23%, 17%, 21%, and 35% respectively. This is expected to be a result of the increase in Chinese visitors’ revenue of 46% yoy in 3Q26. Interest expense should drop yoy but go up qoq due to increasing loan amounts. The EBITDA margins should expand yoy, supported by margin expansion of both hotel and retail businesses..
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt3.24
Bt3.90
+20.4%
Bt3.70
Analyst
Analyst
Nonpawit Vathanadachakul
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

30 Oct 2026
Central Plaza Hotel (CENTEL TB): Expect Robust 3Q26 Earnings, Supported By Strong RevPar Growth

26 Oct 2026
The Erawan Group (ERW TB): 3Q26 Results Preview: Expect Outstanding Earnings

27 Oct 2026
Praram 9 Hospital (PR9 TB): Expect A Record High Net Profit In 3Q26
Our latest research

9 Nov 2026
CP Axtra (CPAXT TB): 3Q26: Earnings Trough; Store Closures to Boost Profit

9 Nov 2026
KCE (Thailand) (KCE TB): Management Guides A Strong 4Q26-2027 Outlook; More Attractive Valuation Presents Trading Opportunities

9 Nov 2026