Analyst
Wendy Chen
wendy.chen@uobkh.comAnalyst
Wang Qi, CFA
qi.wang@uobkh.comAnalyst
In collaboration with UOBKH Institutional Research
Key US Market Indices
Index | Price | Past 2-Week Return | YTD Price Return |
S&P 500 | 7,580 | -1.4% | 10.7% |
Dow Jones Industrial Average | 51,770 | -0.4% | 7.7% |
Nasdaq Composite | 25,437 | -3.8% | 9.4% |
Source: UOB Kay Hian and iFinD, as of October 30, 2026.
- Fed: hawkish rhetoric, patient hands. The October FOMC kept rates steady, aligning with our expectations given the US midterm elections being just one week away. A Dec rate hike remains our base case, currently priced at a ~72% probability by FedWatch. On the Fed balance sheet, Chair Warsh reassured markets that the dedicated QT (quantitative tightening) task force will report back only in 1Q2027, and any changes are "unlikely to materially affect the current policy cycle". Notably, the market's focus is shifting to AI financing. Warsh acknowledged tighter credit spreads and funding conditions in tech since the September hike, adding the nuance that it is not the sector's inherent rate sensitivity, but its changing financing structure that matters. His AI task force will hold a public hearing on Nov 16 to further discuss AI productivity and related macro implications.
- US equities faced a sharp pullback over the past two weeks, led by the tech-heavy Nasdaq Composite (-3.8%), together with lower S&P 500 (-1.4%) and Dow Jones (-0.4%). As a result, YTD returns on US indexes moderated to 9.4%, 10.7%, and 7.7% respectively. This divergence underscores a brutal rotation out of high-beta AI momentum names, as the market digests the dual pressures of the AI credit concerns and an aggressive deleveraging cycle into the end of October.
- Our “October Awakening" is happening. Our prior warnings of a macro-driven volatility spike in Sep-Oct have come true. The VIX (volatility index) has intraday punched through 20 four times in a single month, mirroring the seasonal pattern we flagged ahead of the midterms. Goldman Sachs data reveals that hedge funds cut tech exposure at the fastest pace on record in October, with net leverage plunging to a 1-year low of 43%. We see the market trapped in the same self-reinforcing loop from July this year, with heightened volatility pushing margin-call liquidation and impacting the direction of CTA/passive flows, all amid seasonal headwinds in US markets.
- Looking past the current turbulence, the upcoming midterms could offer a pivot point, as history points to a “relief rally” once the political overhang is removed. We see both Democrats and Republicans share strategic and even personal interests in advancing US AI leadership against competition (watch our latest CIO series for more details). We advise investors to brace through the final stretch of the midterm gauntlet and stay invested, with the possibility of a year-end rally still in play.
- Best performing sectors: Health Care (XLV) +5.2%, Utilities (XLU) +5.0%, and Real Estate (XLRE) +3.6%.
- Potential movers and shakers:
Positive | Microsoft (MSFT), Eli Lilly (LLY), AbbVie (ABBV), P&G (PG), Netflix (NFLX), Disney (DIS), SK Hynix (SKHY) |
Neutral | Amazon (AMZN), JPMorgan (JPM), Verizon (VZ) |
Negative | Alphabet (GOOGL) |
- Must Watch Events: US Midterm Elections (Nov 3), October Non-farm payrolls (Nov 6), October CPI (Nov 10), October PPI (Nov 13), October PCE (Nov 25). Earnings: AAPL (Nov 2), AMD (Nov 3), LITE (Nov 5), OXY (Nov 9), NVDA (Nov 17), WMT (Nov 19). Details below.
Date | Macro Data | Sector / Company Events |
Nov 2 | US Oct ISM Manufacturing PMI | Earnings: AAPL, PLTR, EL, TEM |
Nov 3 | US Midterm Elections, US Job Openings | Earnings: AMD, ANET, SHOP, BKNG, PFE |
Nov 4 | US Oct ISM Services PMI | Earnings: QCOM, APP, COHR, UBER, ARM, MCD |
Nov 5 | US Initial Jobless Claims | Earnings: LITE, NET |
Nov 6 | US Oct Nonfarm Payrolls, US Oct Unemployment Rate | Earnings: MRNA |
Nov 9 |
| Earnings: OXY, TTWO |
Nov 10 | US Oct CPI | Earnings: CRWV, SE |
Nov 11 |
| Earnings: CSCO |
Nov 12 |
| Earnings: NBIS, AMAT, CBRS |
Nov 13 | US Oct PPI |
|
Nov 16 | US Retail Sales |
|
Nov 17 |
| Earnings: NVDA, HD, DIS |
Nov 18 |
| Morgan Stanley Asia Pacific Summit 2026 Earnings: TGT, TJX |
Nov 19 | Oct FOMC Minutes | Earnings: WMT |
Nov 20 | US Consumer Sentiment Final |
|
Nov 25 | US Oct PCE, US Q3 GDP (2nd Estimate) |
|
Nov 27 | US Black Friday |
|
Best 3 S&P Sectors (Past 2 Weeks)
Ticker | Sector ETF | Past 2-Week Return | YTD Return | Stock Drivers Past 2-Weeks |
XLV.P | Health Care | 5.2% | 20.9% | Eli Lilly And Company (LLY.N) +14.3%, Johnson & Johnson (JNJ.N) +7.6%, Abbvie Inc. (ABBV.N) +4.3% |
XLU.P | Utilities | 5.0% | 3.9% | Nextera Energy, Inc. (NEE.N) +7.1%, Duke Energy Corporation (DUK.N) +6.8%, The Southern Company (SO.N) +5% |
XLRE.P | Real Estate | 3.6% | 9.6% | Public Storage (PSA.N) +9.8%, Simon Property Group, Inc. (SPG.N) +7.5%, Crown Castle Inc. (CCI.N) +9.4% |
Source: UOB Kay Hian and iFinD, as of October 30, 2026.
- Health Care came on top with broad-based pharmaceutical strength, rallying 5.2% over the past two weeks and extending its YTD return to 20.9%. This was spearheaded by Eli Lilly (LLY), which surged 14.3% with another beat-and-raise 3Q2026 earnings announcement, buoyed by sustained momentum in its GLP-1 franchise. Johnson & Johnson (JNJ) added 7.6% and AbbVie (ABBV) gained 4.3%, reflecting strong investor appetite for high-quality, defensive mega-caps with visible pipeline catalysts. As macro volatility persists before the midterms, XLV's dual role as a possible defensive and structural growth compounder remains compelling. We maintain both JNJ and LLY as our Core Recommendation.
- Utilities staged a sharp relief rally as yield fears subside and AI power demand persists. XLU rebounded sharply by 5.0% over the last two weeks, erasing its previous period's steep decline and pushing its YTD return back into positive territory at 3.9%. The recovery was partly driven by a temporary stabilization of long-term Treasury yields, restoring the relative appeal of Utilities as a high-dividend "bond proxy". NextEra Energy (NEE) led the charge with a 7.1% gain, while regulated peers Duke Energy (DUK) and The Southern Company (SO) also posted robust advances of 6.8% and 5.0%, respectively.
- Real Estate (XLRE) advanced 3.6% over the past two weeks, building on a solid 9.6% YTD gain, as the sector benefited from a broader relief due to the Fed’s rate pause in October. The rally was notably diversified across sub-sectors. Crown Castle (CCI) surged 9.4%, highlighting renewed investor enthusiasm for towers/infrastructure for 5G expansion and AI data center connectivity. Public Storage (PSA) jumped 9.8%, reflecting resilient domestic mobility and storage demand. Retail mall leader Simon Property Group (SPG) added 7.5%, underscoring the enduring strength of prime experiential retail assets despite broader consumer spending anxieties. Despite the relief rally, the sector remains sensitive to the Fed's rate decision and terminal rate trajectory, and we stay on the sideline.
Worst 3 S&P Sectors (Past 2 Weeks)
Ticker | Sector ETF | Past 2-Week Return | YTD Return | Stock Drivers Past 2-Weeks |
XLI.P | Industrials | 0.4% | 8.8% | Caterpillar Inc. (CAT.N) -14%, The Boeing Company (BA.N) -10.4%, Ge Vernova Inc. (GEV.N) -5.5% |
XLK.P | Information Technology | -3.5% | 25.1% | Servicenow, Inc. (NOW.N) -27.7%, Arista Networks, Inc. (ANET.N) -7.7%, Corning Incorporated (GLW.N) -7.1% |
XLC.P | Communication Services | -9.3% | -14.4% | At&T Inc. (T.N) -7.7%, The Walt Disney Company (DIS.N) +1.2%, Verizon Communications Inc. (VZ.N) +1.3% |
Source: UOB Kay Hian and iFinD, as of October 30, 2026.
- Industrials flatlined amid global cyclical fears. XLI managed a marginal 0.4% gain over the past two weeks, effectively stalling its momentum and resulting in a modest 8.8% YTD advance. The weakness was driven by a broad retreat in cyclical and capital goods names. Caterpillar (CAT) slumped 14.0% as investors priced in a potential slowdown in global construction and manufacturing amid sticky inflation and elevated diesel prices. Boeing (BA) dropped 10.4%, as it continued to face headwinds from lingering supply chain constraints and regulatory scrutiny. Meanwhile, GE Vernova (GEV) retreated 5.5%, experiencing a healthy tactical pullback as investors locked in profits following its massive year-to-date run in the power infrastructure space. We maintain GEV as our Core Recommendation.
- Information Technology (XLK) declined 3.5% over the past two weeks, marking a notable reversal from the previous period, though it still holds a robust 25.1% gain YTD. The pullback illustrates the "sorting mechanism" we highlighted in our previous outlook, where the market ruthlessly differentiates between AI winners and losers. ServiceNow (NOW) plummeted 27.7%, reflecting severe market anxiety that agentic AI could disrupt and displace traditional enterprise SaaS workflows. Networking and optical names also saw profit-taking, with Arista Networks (ANET) and Corning (GLW) retreating 7.7% and 7.1% respectively, as investors questioned the near-term pace of hyperscaler capex amid macro headwinds and growing free-cash-flow pressures.
- Communication Services (XLC) suffered a sharp 9.3% sell-off, pushing the sector deeper into negative territory at -14.4% YTD. The decline was heavily concentrated in traditional telecommunications, with AT&T (T) tumbling 7.7% as investors priced in mounting competitive pressure from SpaceX's Starlink, whose direct-to-cell and fixed wireless offerings are steadily eroding the incumbent carriers' subscriber growth and pricing power. Defensive and media names with resilient cash flows managed to edge higher: Walt Disney (DIS) gained 1.2%, supported by its streaming price hikes and franchise strength, while Verizon (VZ) added 1.3%, acting as a defensive haven. This divergence highlights the market's ongoing preference for high-quality, pricing-power businesses over legacy carriers facing structural disruption from satellite-based connectivity.
Stocks: Potential Movers and Shakers
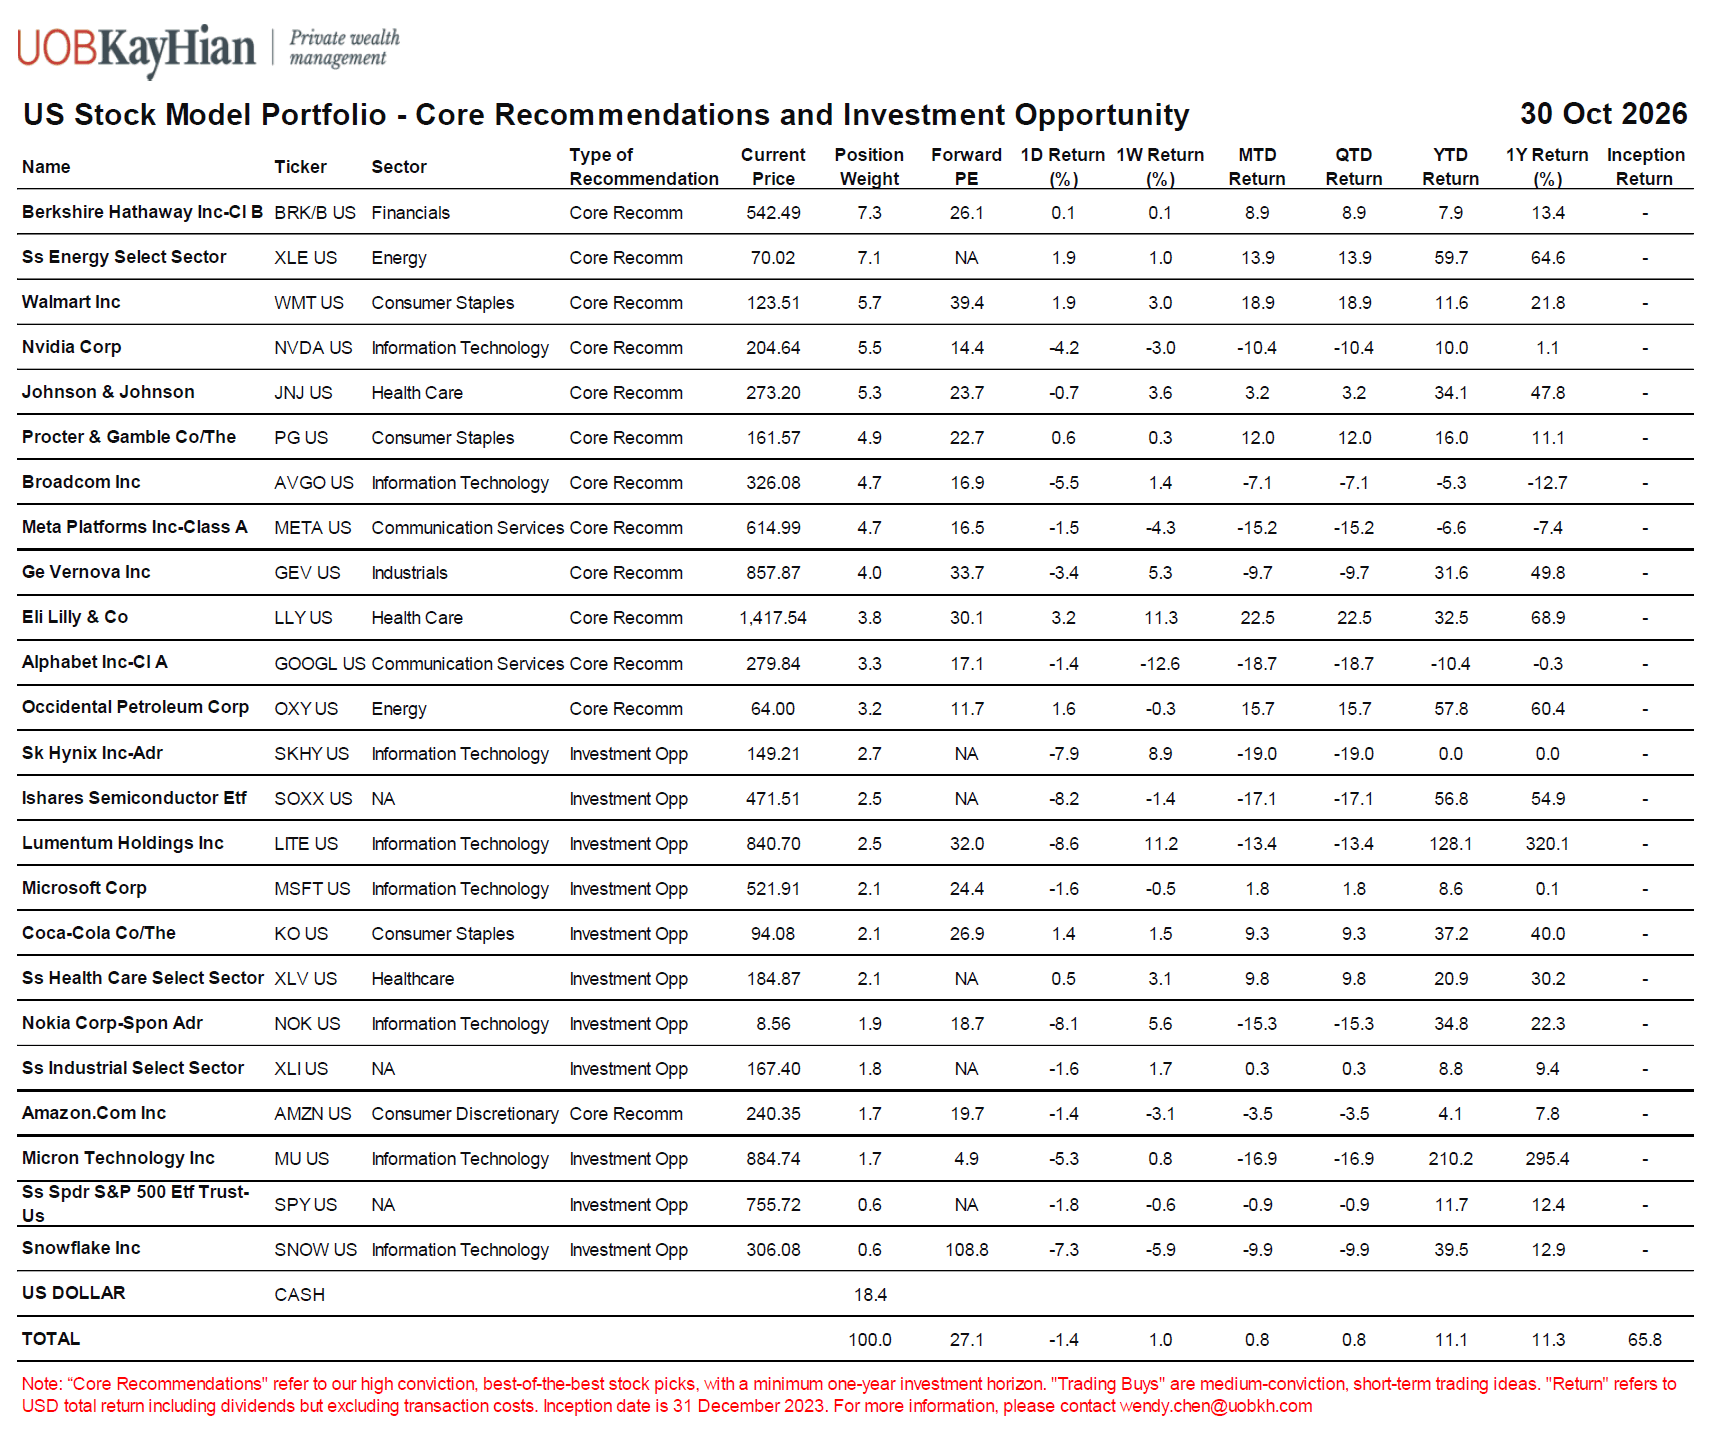
Please note that not all stocks mentioned below are recommended by PWM Research / CIO Office. Please refer to the Appendix for our US Stock Model Portfolio and official recommendations. Equity investing involves significant risk. Investor discretion is advised.
Stock | Sector | PWM Research Recommendation | Type of News | Our Read on the News |
Microsoft (MSFT) | Information Technology | Core Recommendation | Earnings | Positive |
- Microsoft beat quarterly results, with Azure revenue growth accelerating to 48% yoy and Office 365 revenue +18% yoy, both ahead of expectations. Copilot daily active users (DAUs) grew 50% qoq, indicating broadening enterprise AI adoption. Our channel checks indicate several large enterprises are expanding Copilot seat purchases, amid early stages of deploying AI application.
- Microsoft expects FCF to remain positive through FY2027 (June), making it the only hyperscaler expected to do so. Microsoft's positive FCF reflects its disciplined approach to AI spending, including greater use of off-balance sheet leasing arrangements. However, we expect a higher mix of owned infrastructure investments over time, particularly into 2027. Microsoft’s latest earnings have largely reinforced our investment thesis that the company remains enduring enterprise AI leader (Garrick Li).
Stock | Sector | PWM Research Recommendation | Type of News | Our Read on the News |
SK Hynix (SKHY) | Information Technology | Investment Opportunity | Earnings | Positive |
- SK Hynix reported another strong quarter, with revenue beating consensus by 7% and operating profit beating by 9%. Management expects memory demand to outpace supply through 2030, reinforcing our view of the Memory Supercycle.
- Management also reiterated its commitment to share buybacks, and the Board approved a new 20 trillion won share repurchase. With ~4x forward PE, the aggressive share buyback and dividend are expected to bring down its 2028 valuation to 2-3 times earnings, which is close to its financial crisis level and looks increasingly compelling (Garrick Li).
Stock | Sector | PWM Research Recommendation | Type of News | Our Read on the News |
Amazon (AMZN) | Consumer Discretionary | Core Recommendation | Earnings | Neutral |
- Amazon shares declined after delivering a small miss on both revenue and cloud growth. 3Q revenue grew 12% yoy, missing consensus by ~1% as online retail only grew by 2%. Operating income grew 61% yoy, while operating margin reached a record 13.9% , driven largely by a richer mix from AWS (63% of total operating income). AWS revenue increased 39.3% yoy, compared with buyside expectations of 40%+, while operating margin remained a bright spot, coming in at 38.7%, ahead of the 37.0% consensus.
- While the results seem unexciting, they do not change our long-term investment thesis. Management continues to expect AWS growth to remain above 40% yoy in both 2027 and 2028 and highlighted that spending on Amazon Bedrock increased 7x yoy. This suggests that enterprises remain in the very early stages of deploying AI inference at scale, and inference already accounts for well over half of AWS's AI-related revenue and continues to grow rapidly.
- Free cash flow -USD 42 bn, worse than expected. We believe the key question is not the current level of FCF, but how quickly Amazon can convert its AI investments into revenue. Oracle recently guided for FCF to turn positive in 2H2028. Given Amazon's cost advantages and AWS's 38% operating margin, we believe Amazon could also achieve positive FCF by 2028. (Garrick Li)
Stock | Sector | PWM Research Recommendation | Type of News | Our Read on the News |
Alphabet (GOOGL) | Information Technology | Investment Opportunity | Earnings | Negative |
- Google missed 3Q revenue expectations by 6%, as advertising growth (Search + YouTube) slowed to 12% yoy and came in below expectations. However, Google Cloud surged 103%, ahead of buyside expectations of ~100%, driven by continuing strong AI demand (TPU, data and cybersecurity).
- As highlighted recently, Search is facing a structural shift in user behavior. Our channel checks suggest portions of advertising budgets are increasingly shifting from Google toward Meta. However, we believe Google can defend its position through its own AI offerings, similar to the rollout of AI Mode. Over time, we see AI agents becoming a new monetization and advertising growth opportunity rather than a simple disruption risk.
- We expect Google's TPU deployment to continue expanding capacity and supporting cloud growth in 2027. Notably, Google disclosed that Apple is now using TPUs to train AI models (Garrick Li).
Stock | Sector | PWM Research Recommendation | Type of News | Our Read on the News |
Eli Lilly & Co. (LLY) | Health Care | Core Recommendation | Earnings | Positive |
- Strong 3Q2026 beat and guidance raise. Revenue of USD 24.4bn beat consensus of USD 22.6bn, adjusted EPS of USD 7.48 came ahead of expectation of USD 6.26, led by Mounjaro (USD 10.72bn revenue) and Zepbound (USD 5.35bn revenue). FY2026 revenue guidance was raised by USD 5bn to USD 91bn to USD 92bn. EPS guidance was trimmed slightly on acquisition charges.
- Volume growth outpacing price erosion. Volumes rose 53%, offsetting a 15% decline in realised prices. Growth was supported by over 500,000 new Medicare patients and a 93% yoy jump in international Mounjaro sales to USD 5.7b.
- Foundayo (oral GLP-1) ramp still early. Foundayo sales of USD 184m missed estimates by about USD 30m, which management attributed to 2Q launch stocking. Underlying US demand more than tripled, and its new to brand prescription share doubled to about 40%.
- Constructive long-term outlook. We remain positive on LLY as strong injectable demand outweighs pricing pressure. Foundayo’s international rollout and Retatrutide’s 2027 filing should drive the next leg of growth (Tang Kai Jie).
Stock | Sector | PWM Research Recommendation | Type of News | Our Read on the News |
AbbVie Inc. (ABBV) | Health Care | No Recommendation | Earnings | Positive |
- Solid 3Q2026 beat and guidance raise. Revenue of USD 17.40bn and adjusted EPS of USD 3.82 topped estimates. FY2026 adjusted EPS guidance was raised to USD 13.95 to USD 13.99 from USD 13.76 to USD 13.96, despite a USD 0.69 YTD hit from acquired IPR&D and milestone expenses.
- Immunology and neuroscience driving growth. Skyrizi sales rose 22.7% yoy to USD 5.78bn, while Rinvoq delivered USD 2.71bn, in line with expectations. Together they continue to offset Humira erosion. Neuroscience revenue grew 19% to USD 3.39bn, led by Botox Therapeutic and Vraylar.
- Singapore biologics capacity expansion. AbbVie’s USD 223mn expansion of its Tuas site, its only manufacturing facility in Asia, is expected to begin operations in 2026. It adds 24,000L of biologics drug substance capacity to support current products and emerging immunology and oncology assets.
- Constructive long-term outlook. Wall Street is constructive on ABBV as Skyrizi and Rinvoq momentum sustains growth beyond Humira. Pipeline assets such as lutikizumab and obesity candidate ABBV-295, alongside expanded biologics capacity, support longer-term upside into the 2030s. (Tang Kai Jie)
Stock | Sector | PWM Research Recommendation | Type of News | Our Read on the News |
JPMorgan Chase | Financials | No Recommendation | Earnings | Neutral |
- JPMorgan Chase (JPM) reported 3Q2026 diluted EPS of USD 5.57, up 10% yoy and below market consensus of USD 5.92. It incurred USD 498mn of after-tax investment securities losses and missed consensus forecast for the first time in nearly three years. Excluding the losses, return on tangible common equity was 20%.
- Slowdown in dealmaking and bond market trading. Commercial & Investment Bank revenue moderated USD 2.1bn or 9% qoq in 3Q2026. Investment banking fees declined 9% qoq and fixed income markets revenue was down 11% qoq. However, Consumer & Community Banking revenue rose 9% yoy, supported by strong customer acquisition and card activity. Asset & Wealth Management also increased 14% yoy, with USD 263bn in client asset net inflows and assets under management reaching USD 5.2tr.
- Balance-sheet growth remained healthy. Average loans and deposits rose 10% and 8% yoy, respectively. Credit costs totalled USD 2.7b, including USD 2.2bn in net charge-offs and a USD 539mn reserve build. Capital remained solid with CET-1 ratio of 13.9%. JPMorgan distributed USD 4.4bn in common dividends and repurchased USD 664mn of common stock on a net basis.
- JPM is currently trading at a P/B of 2.55x, which is supported by its projected ROE of 18.7% for 2026. Key risks remain macro and geopolitical uncertainties, although we admire the strength of JPM’s fortress balance sheet. (Jonathan Koh)
Stock | Sector | PWM Research Recommendation | Type of News | Our Read on the News |
Procter & Gamble | Consumer Staples | Core Recommendation | Earnings | Positive |
- 1QFY2027 revenue and core EPS beat consensus by 2% and 6% respectively. Procter & Gamble reported 1QFY2027 net sales of USD 23.3bn, up 4% yoy on organic sales, beating consensus by 2%. Operating income was USD 5.9bn, up 1% yoy, with operating margin falling 0.7ppt yoy to 25.5%, core operating margin down 0.8ppt yoy to 25.9%, excluding non-core restructuring charges. Net income was USD 4.7bn, flat yoy, with net margin falling 0.9ppt yoy to 20.3%. Core EPS was USD 2.00, up 1% yoy, beating consensus by 6%. All five segments posted organic growth in 1QFY2027. By category, Beauty/Grooming/Health Care/Fabric & Home Care/Baby, Feminine & Family Care recorded organic sales growth of +5%/+5%/+3%/+5%/+3% yoy, respectively, in 1QFY2027.
- FY2027 organic sales and core EPS guidance maintained despite a larger cost headwind. Management maintained FY2027 organic sales growth of 1% to 3% and core EPS growth of 0% to 3%, and raised all-in sales growth guidance to 2% to 4% to include the Thorne acquisition.
- Key takeaways from earnings call: Middle East conflict costs are expected to intensify from 2QFY2027. The FY2027 commodity headwind was raised by USD 400m to USD 1.4bn, assuming oil at USD 100/barrel, with only partial flow-through in 1QFY2027. Management will offset this through record productivity and pricing with innovation, without jeopardising top-line momentum. Looking ahead, 1HFY2027 organic sales growth is expected at around 3%, implying a slowdown in 2QFY2027 as rising fuel prices pressure consumers.
- US and China recovery gaining momentum. In the US, over 70% of P&G’s top retail partners are now holding or growing share, up from around 50% in 2HFY2026, and management targets above 80% by end-2026. Greater China organic sales rose 8%, led by SK-II (+12%) and Pampers (close to +50%), though the latter was boosted by a competitor’s product issue.
- Expect sideways trading in the short to mid-term as the stock has already rallied close to the consensus target price. Post-earnings to date, PG’s share price has risen 3%, while the consensus target price has been revised up 8% to USD 173.32. Its 1-year forward PE currently stands at 22.7x, above the S&P 500’s current 18.3x and its 10-year historical average of 22.5x. We expect the stock to trade between USD 155 and USD 173 for some time, as investors may rotate away from consumer staples into more attractively valued sectors. (Ejann Hiew)
Stock | Sector | PWM Research Recommendation | Type of News | Our Read on the News |
Netflix Inc (NFLX) | Communication Services | No Recommendation | Earnings | Positive |
- Revenue growth and margin expansion support earnings outlook. Netflix reported 3Q2026 revenue growth of 12% year-on-year to USD 12.9bn, in line with its forecast. Operating margin increased to 34.6%, exceeding expectations primarily due to expense timing. For 2026, management expects revenue of USD 51.1bn, up 13%, and a 31.5% operating margin. Continued investment in differentiated series, films and live events should support engagement and long-term growth.
- Advertising improvements face rollout delays. Netflix announced enhanced advertising targeting and measurement capabilities, helping brands assess campaign effectiveness and reach relevant audiences. However, it lowered its 2026 advertising revenue forecast to approximately USD 2.7bn due to slower-than-expected rollout of some capabilities. Advertising remains a growth opportunity, although the revision highlights that near-term monetisation expectations may be affected.
- International content performance supports engagement and retention. Netflix reported that non-English content now accounts for more than a third of viewing. In India, 3Q viewing hours increased 24% year-on-year, while revenue grew approximately 18% on a currency-neutral basis and paid net additions reached a quarterly record. Strong local programming should support international growth, while churn improved globally and in the US.
- Positive on long-term earnings growth despite advertising delays. Improving profitability, healthy retention and successful international content support its Netflix’s earnings outlook. Advertising expansion provides further growth opportunities, although the reduced forecast highlights execution risks. Continued content investment and cost discipline should support long-term growth, while the timing of advertising improvements warrants monitoring. (Shaina Kamlesh Mahtani)
Stock | Sector | PWM Research Recommendation | Type of News | Our Read on the News |
Walt Disney (DIS) | Communication Services | No Recommendation | Sales / Products | Positive |
- Super Bowl LXI deepens sports and franchise integration. ESPN and Lucasfilm announced a Star Wars Funday Football alternate telecast for Super Bowl LXI, streaming live on Disney+. The animated broadcast will be available across more than 155 markets through live and on-demand viewing. Combining major sports with a popular franchise could attract families and younger viewers, strengthening Disney+’s offering and audience engagement.
- Channel 4 partnership expands Disney+ content offering. Disney and Channel 4 announced a partnership that will bring Channel 4’s linear channel and selected on-demand programming to Disney+ in the UK and Ireland from early 2027. Selected shows will also be available on Disney+ alongside their Channel 4 release. The partnership broadens Disney+’s local content offering and should support engagement and subscriber value.
- Strong football audiences reinforce ESPN’s sports appeal. ESPN reported that Monday Night Football averaged 19m viewers through seven weeks, up 26% year-on-year. The Cowboys–Eagles game attracted 18.8m viewers across its broadcast and streaming outlets, matching the strongest Week 7 audience of the ESPN era. Strong viewing should support advertiser demand and reinforce the value of Disney’s sports offering, although sports-rights costs remain a consideration.
- Positive on Disney’s long-term earnings outlook. Stronger sports audiences, broader local programming and integration of established franchises should support engagement and monetisation. The Channel 4 partnership strengthens Disney+’s content offering, while ESPN’s audience momentum supports its commercial appeal. These developments provide opportunities for longer-term earnings growth, although sports-rights costs, content spending and execution remain key considerations. (Shaina Kamlesh Mahtani)
Stock | Sector | PWM Research Recommendation | Type of News | Our Read on the News |
Verizon Comms Inc (VZ) | Communication Services | No Recommendation | Earnings | Neutral |
- Earnings and cash-flow growth support higher guidance. Verizon reported on 26 October that 3Q2026 revenue rose 1.5% year-on-year to USD 34.3bn, while adjusted EPS increased 8.3% to USD 1.31. Free cash flow grew 12.1% to USD 7.8bn, alongside 406,000 postpaid phone net additions. Management raised its full-year adjusted EPS growth forecast to 7–7.5% and expects free cash-flow growth approaching 12%, reflecting improving customer momentum and operating efficiency.
- Debt tender offers support balance-sheet management. Verizon announced on 29 October offers to repurchase five series of outstanding bonds for an aggregate purchase price of up to USD 500m. The offers are scheduled to expire on 4 November, with settlement expected on 9 November. If completed, the repurchases would reduce outstanding debt, although the impact will depend on participation and the amount accepted.
- Enhanced prepaid plans support customer acquisition and retention. Verizon’s Straight Talk announced upgraded unlimited plans, adding 5G Ultra Wideband access, larger hotspot allowances and expanded international benefits without increasing monthly base prices. Eligible customers also receive USD 10 monthly savings on bundled home internet. Better value should strengthen its appeal to customers, although additional benefits could limit margin improvement.
- Neutral as growth opportunities are balanced by ongoing pressures. Verizon’s stronger customer additions and cash generation should support earnings, while enhanced prepaid plans could help sustain demand. However, modest revenue growth, competition and network spending requirements temper the outlook, making cost discipline and profitable customer retention important to sustained improvement. (Shaina Kamlesh Mahtani)
Type of News | Explanation |
Channel Checks | Industry-wide or supply chain news with implications to a particular sector or company |
Corporate Action | Dividends, special dividends, stock splits, share buybacks, equity / bond financing, M&As, spin-offs and restructuring etc. |
Earnings | Quarterly earnings for US-listed companies. Semi-annual earnings for Hong Kong-listed companies |
Insider Dealing | Company insiders’ buying / selling of stocks and derivatives of the company |
Investor Action | Leading investor buying / selling including activist investor actions |
Investor Roadshow | Deal and non-deal roadshows, reverse roadshows (analyst days), and company meetings at investment conferences |
Legal / Regulatory | Lawsuits, legislature/regulation changes, other regulatory events |
Macro / Industry Data | Regular economic or industry data related to the sector or stock |
Sales / Products | Sales or product related news, such as monthly sales or new product launches |
Public Event | Public speeches and appearances by companies in the media or industry conferences |
Appendix A – US Stock Model Portfolio
Key US Market Indices
Index | Price | Past 2-Week Return | YTD Price Return |
S&P 500 | 7,580 | -1.4% | 10.7% |
Dow Jones Industrial Average | 51,770 | -0.4% | 7.7% |
Nasdaq Composite | 25,437 | -3.8% | 9.4% |
Source: UOB Kay Hian and iFinD, as of October 30, 2026.
- Fed: hawkish rhetoric, patient hands. The October FOMC kept rates steady, aligning with our expectations given the US midterm elections being just one week away. A Dec rate hike remains our base case, currently priced at a ~72% probability by FedWatch. On the Fed balance sheet, Chair Warsh reassured markets that the dedicated QT (quantitative tightening) task force will report back only in 1Q2027, and any changes are "unlikely to materially affect the current policy cycle". Notably, the market's focus is shifting to AI financing. Warsh acknowledged tighter credit spreads and funding conditions in tech since the September hike, adding the nuance that it is not the sector's inherent rate sensitivity, but its changing financing structure that matters. His AI task force will hold a public hearing on Nov 16 to further discuss AI productivity and related macro implications.
- US equities faced a sharp pullback over the past two weeks, led by the tech-heavy Nasdaq Composite (-3.8%), together with lower S&P 500 (-1.4%) and Dow Jones (-0.4%). As a result, YTD returns on US indexes moderated to 9.4%, 10.7%, and 7.7% respectively. This divergence underscores a brutal rotation out of high-beta AI momentum names, as the market digests the dual pressures of the AI credit concerns and an aggressive deleveraging cycle into the end of October.
- Our “October Awakening" is happening. Our prior warnings of a macro-driven volatility spike in Sep-Oct have come true. The VIX (volatility index) has intraday punched through 20 four times in a single month, mirroring the seasonal pattern we flagged ahead of the midterms. Goldman Sachs data reveals that hedge funds cut tech exposure at the fastest pace on record in October, with net leverage plunging to a 1-year low of 43%. We see the market trapped in the same self-reinforcing loop from July this year, with heightened volatility pushing margin-call liquidation and impacting the direction of CTA/passive flows, all amid seasonal headwinds in US markets.
- Looking past the current turbulence, the upcoming midterms could offer a pivot point, as history points to a “relief rally” once the political overhang is removed. We see both Democrats and Republicans share strategic and even personal interests in advancing US AI leadership against competition (watch our latest CIO series for more details). We advise investors to brace through the final stretch of the midterm gauntlet and stay invested, with the possibility of a year-end rally still in play.
- Best performing sectors: Health Care (XLV) +5.2%, Utilities (XLU) +5.0%, and Real Estate (XLRE) +3.6%.
- Potential movers and shakers:
Positive | Microsoft (MSFT), Eli Lilly (LLY), AbbVie (ABBV), P&G (PG), Netflix (NFLX), Disney (DIS), SK Hynix (SKHY) |
Neutral | Amazon (AMZN), JPMorgan (JPM), Verizon (VZ) |
Negative | Alphabet (GOOGL) |
- Must Watch Events: US Midterm Elections (Nov 3), October Non-farm payrolls (Nov 6), October CPI (Nov 10), October PPI (Nov 13), October PCE (Nov 25). Earnings: AAPL (Nov 2), AMD (Nov 3), LITE (Nov 5), OXY (Nov 9), NVDA (Nov 17), WMT (Nov 19). Details below.
Date | Macro Data | Sector / Company Events |
Nov 2 | US Oct ISM Manufacturing PMI | Earnings: AAPL, PLTR, EL, TEM |
Nov 3 | US Midterm Elections, US Job Openings | Earnings: AMD, ANET, SHOP, BKNG, PFE |
Nov 4 | US Oct ISM Services PMI | Earnings: QCOM, APP, COHR, UBER, ARM, MCD |
Nov 5 | US Initial Jobless Claims | Earnings: LITE, NET |
Nov 6 | US Oct Nonfarm Payrolls, US Oct Unemployment Rate | Earnings: MRNA |
Nov 9 |
| Earnings: OXY, TTWO |
Nov 10 | US Oct CPI | Earnings: CRWV, SE |
Nov 11 |
| Earnings: CSCO |
Nov 12 |
| Earnings: NBIS, AMAT, CBRS |
Nov 13 | US Oct PPI |
|
Nov 16 | US Retail Sales |
|
Nov 17 |
| Earnings: NVDA, HD, DIS |
Nov 18 |
| Morgan Stanley Asia Pacific Summit 2026 Earnings: TGT, TJX |
Nov 19 | Oct FOMC Minutes | Earnings: WMT |
Nov 20 | US Consumer Sentiment Final |
|
Nov 25 | US Oct PCE, US Q3 GDP (2nd Estimate) |
|
Nov 27 | US Black Friday |
|
Best 3 S&P Sectors (Past 2 Weeks)
Ticker | Sector ETF | Past 2-Week Return | YTD Return | Stock Drivers Past 2-Weeks |
XLV.P | Health Care | 5.2% | 20.9% | Eli Lilly And Company (LLY.N) +14.3%, Johnson & Johnson (JNJ.N) +7.6%, Abbvie Inc. (ABBV.N) +4.3% |
XLU.P | Utilities | 5.0% | 3.9% | Nextera Energy, Inc. (NEE.N) +7.1%, Duke Energy Corporation (DUK.N) +6.8%, The Southern Company (SO.N) +5% |
XLRE.P | Real Estate | 3.6% | 9.6% | Public Storage (PSA.N) +9.8%, Simon Property Group, Inc. (SPG.N) +7.5%, Crown Castle Inc. (CCI.N) +9.4% |
Source: UOB Kay Hian and iFinD, as of October 30, 2026.
- Health Care came on top with broad-based pharmaceutical strength, rallying 5.2% over the past two weeks and extending its YTD return to 20.9%. This was spearheaded by Eli Lilly (LLY), which surged 14.3% with another beat-and-raise 3Q2026 earnings announcement, buoyed by sustained momentum in its GLP-1 franchise. Johnson & Johnson (JNJ) added 7.6% and AbbVie (ABBV) gained 4.3%, reflecting strong investor appetite for high-quality, defensive mega-caps with visible pipeline catalysts. As macro volatility persists before the midterms, XLV's dual role as a possible defensive and structural growth compounder remains compelling. We maintain both JNJ and LLY as our Core Recommendation.
- Utilities staged a sharp relief rally as yield fears subside and AI power demand persists. XLU rebounded sharply by 5.0% over the last two weeks, erasing its previous period's steep decline and pushing its YTD return back into positive territory at 3.9%. The recovery was partly driven by a temporary stabilization of long-term Treasury yields, restoring the relative appeal of Utilities as a high-dividend "bond proxy". NextEra Energy (NEE) led the charge with a 7.1% gain, while regulated peers Duke Energy (DUK) and The Southern Company (SO) also posted robust advances of 6.8% and 5.0%, respectively.
- Real Estate (XLRE) advanced 3.6% over the past two weeks, building on a solid 9.6% YTD gain, as the sector benefited from a broader relief due to the Fed’s rate pause in October. The rally was notably diversified across sub-sectors. Crown Castle (CCI) surged 9.4%, highlighting renewed investor enthusiasm for towers/infrastructure for 5G expansion and AI data center connectivity. Public Storage (PSA) jumped 9.8%, reflecting resilient domestic mobility and storage demand. Retail mall leader Simon Property Group (SPG) added 7.5%, underscoring the enduring strength of prime experiential retail assets despite broader consumer spending anxieties. Despite the relief rally, the sector remains sensitive to the Fed's rate decision and terminal rate trajectory, and we stay on the sideline.
Worst 3 S&P Sectors (Past 2 Weeks)
Ticker | Sector ETF | Past 2-Week Return | YTD Return | Stock Drivers Past 2-Weeks |
XLI.P | Industrials | 0.4% | 8.8% | Caterpillar Inc. (CAT.N) -14%, The Boeing Company (BA.N) -10.4%, Ge Vernova Inc. (GEV.N) -5.5% |
XLK.P | Information Technology | -3.5% | 25.1% | Servicenow, Inc. (NOW.N) -27.7%, Arista Networks, Inc. (ANET.N) -7.7%, Corning Incorporated (GLW.N) -7.1% |
XLC.P | Communication Services | -9.3% | -14.4% | At&T Inc. (T.N) -7.7%, The Walt Disney Company (DIS.N) +1.2%, Verizon Communications Inc. (VZ.N) +1.3% |
Source: UOB Kay Hian and iFinD, as of October 30, 2026.
- Industrials flatlined amid global cyclical fears. XLI managed a marginal 0.4% gain over the past two weeks, effectively stalling its momentum and resulting in a modest 8.8% YTD advance. The weakness was driven by a broad retreat in cyclical and capital goods names. Caterpillar (CAT) slumped 14.0% as investors priced in a potential slowdown in global construction and manufacturing amid sticky inflation and elevated diesel prices. Boeing (BA) dropped 10.4%, as it continued to face headwinds from lingering supply chain constraints and regulatory scrutiny. Meanwhile, GE Vernova (GEV) retreated 5.5%, experiencing a healthy tactical pullback as investors locked in profits following its massive year-to-date run in the power infrastructure space. We maintain GEV as our Core Recommendation.
- Information Technology (XLK) declined 3.5% over the past two weeks, marking a notable reversal from the previous period, though it still holds a robust 25.1% gain YTD. The pullback illustrates the "sorting mechanism" we highlighted in our previous outlook, where the market ruthlessly differentiates between AI winners and losers. ServiceNow (NOW) plummeted 27.7%, reflecting severe market anxiety that agentic AI could disrupt and displace traditional enterprise SaaS workflows. Networking and optical names also saw profit-taking, with Arista Networks (ANET) and Corning (GLW) retreating 7.7% and 7.1% respectively, as investors questioned the near-term pace of hyperscaler capex amid macro headwinds and growing free-cash-flow pressures.
- Communication Services (XLC) suffered a sharp 9.3% sell-off, pushing the sector deeper into negative territory at -14.4% YTD. The decline was heavily concentrated in traditional telecommunications, with AT&T (T) tumbling 7.7% as investors priced in mounting competitive pressure from SpaceX's Starlink, whose direct-to-cell and fixed wireless offerings are steadily eroding the incumbent carriers' subscriber growth and pricing power. Defensive and media names with resilient cash flows managed to edge higher: Walt Disney (DIS) gained 1.2%, supported by its streaming price hikes and franchise strength, while Verizon (VZ) added 1.3%, acting as a defensive haven. This divergence highlights the market's ongoing preference for high-quality, pricing-power businesses over legacy carriers facing structural disruption from satellite-based connectivity.
Stocks: Potential Movers and Shakers
Please note that not all stocks mentioned below are recommended by PWM Research / CIO Office. Please refer to the Appendix for our US Stock Model Portfolio and official recommendations. Equity investing involves significant risk. Investor discretion is advised.
Stock | Sector | PWM Research Recommendation | Type of News | Our Read on the News |
Microsoft (MSFT) | Information Technology | Core Recommendation | Earnings | Positive |
- Microsoft beat quarterly results, with Azure revenue growth accelerating to 48% yoy and Office 365 revenue +18% yoy, both ahead of expectations. Copilot daily active users (DAUs) grew 50% qoq, indicating broadening enterprise AI adoption. Our channel checks indicate several large enterprises are expanding Copilot seat purchases, amid early stages of deploying AI application.
- Microsoft expects FCF to remain positive through FY2027 (June), making it the only hyperscaler expected to do so. Microsoft's positive FCF reflects its disciplined approach to AI spending, including greater use of off-balance sheet leasing arrangements. However, we expect a higher mix of owned infrastructure investments over time, particularly into 2027. Microsoft’s latest earnings have largely reinforced our investment thesis that the company remains enduring enterprise AI leader (Garrick Li).
Stock | Sector | PWM Research Recommendation | Type of News | Our Read on the News |
SK Hynix (SKHY) | Information Technology | Investment Opportunity | Earnings | Positive |
- SK Hynix reported another strong quarter, with revenue beating consensus by 7% and operating profit beating by 9%. Management expects memory demand to outpace supply through 2030, reinforcing our view of the Memory Supercycle.
- Management also reiterated its commitment to share buybacks, and the Board approved a new 20 trillion won share repurchase. With ~4x forward PE, the aggressive share buyback and dividend are expected to bring down its 2028 valuation to 2-3 times earnings, which is close to its financial crisis level and looks increasingly compelling (Garrick Li).
Stock | Sector | PWM Research Recommendation | Type of News | Our Read on the News |
Amazon (AMZN) | Consumer Discretionary | Core Recommendation | Earnings | Neutral |
- Amazon shares declined after delivering a small miss on both revenue and cloud growth. 3Q revenue grew 12% yoy, missing consensus by ~1% as online retail only grew by 2%. Operating income grew 61% yoy, while operating margin reached a record 13.9% , driven largely by a richer mix from AWS (63% of total operating income). AWS revenue increased 39.3% yoy, compared with buyside expectations of 40%+, while operating margin remained a bright spot, coming in at 38.7%, ahead of the 37.0% consensus.
- While the results seem unexciting, they do not change our long-term investment thesis. Management continues to expect AWS growth to remain above 40% yoy in both 2027 and 2028 and highlighted that spending on Amazon Bedrock increased 7x yoy. This suggests that enterprises remain in the very early stages of deploying AI inference at scale, and inference already accounts for well over half of AWS's AI-related revenue and continues to grow rapidly.
- Free cash flow -USD 42 bn, worse than expected. We believe the key question is not the current level of FCF, but how quickly Amazon can convert its AI investments into revenue. Oracle recently guided for FCF to turn positive in 2H2028. Given Amazon's cost advantages and AWS's 38% operating margin, we believe Amazon could also achieve positive FCF by 2028. (Garrick Li)
Stock | Sector | PWM Research Recommendation | Type of News | Our Read on the News |
Alphabet (GOOGL) | Information Technology | Investment Opportunity | Earnings | Negative |
- Google missed 3Q revenue expectations by 6%, as advertising growth (Search + YouTube) slowed to 12% yoy and came in below expectations. However, Google Cloud surged 103%, ahead of buyside expectations of ~100%, driven by continuing strong AI demand (TPU, data and cybersecurity).
- As highlighted recently, Search is facing a structural shift in user behavior. Our channel checks suggest portions of advertising budgets are increasingly shifting from Google toward Meta. However, we believe Google can defend its position through its own AI offerings, similar to the rollout of AI Mode. Over time, we see AI agents becoming a new monetization and advertising growth opportunity rather than a simple disruption risk.
- We expect Google's TPU deployment to continue expanding capacity and supporting cloud growth in 2027. Notably, Google disclosed that Apple is now using TPUs to train AI models (Garrick Li).
Stock | Sector | PWM Research Recommendation | Type of News | Our Read on the News |
Eli Lilly & Co. (LLY) | Health Care | Core Recommendation | Earnings | Positive |
- Strong 3Q2026 beat and guidance raise. Revenue of USD 24.4bn beat consensus of USD 22.6bn, adjusted EPS of USD 7.48 came ahead of expectation of USD 6.26, led by Mounjaro (USD 10.72bn revenue) and Zepbound (USD 5.35bn revenue). FY2026 revenue guidance was raised by USD 5bn to USD 91bn to USD 92bn. EPS guidance was trimmed slightly on acquisition charges.
- Volume growth outpacing price erosion. Volumes rose 53%, offsetting a 15% decline in realised prices. Growth was supported by over 500,000 new Medicare patients and a 93% yoy jump in international Mounjaro sales to USD 5.7b.
- Foundayo (oral GLP-1) ramp still early. Foundayo sales of USD 184m missed estimates by about USD 30m, which management attributed to 2Q launch stocking. Underlying US demand more than tripled, and its new to brand prescription share doubled to about 40%.
- Constructive long-term outlook. We remain positive on LLY as strong injectable demand outweighs pricing pressure. Foundayo’s international rollout and Retatrutide’s 2027 filing should drive the next leg of growth (Tang Kai Jie).
Stock | Sector | PWM Research Recommendation | Type of News | Our Read on the News |
AbbVie Inc. (ABBV) | Health Care | No Recommendation | Earnings | Positive |
- Solid 3Q2026 beat and guidance raise. Revenue of USD 17.40bn and adjusted EPS of USD 3.82 topped estimates. FY2026 adjusted EPS guidance was raised to USD 13.95 to USD 13.99 from USD 13.76 to USD 13.96, despite a USD 0.69 YTD hit from acquired IPR&D and milestone expenses.
- Immunology and neuroscience driving growth. Skyrizi sales rose 22.7% yoy to USD 5.78bn, while Rinvoq delivered USD 2.71bn, in line with expectations. Together they continue to offset Humira erosion. Neuroscience revenue grew 19% to USD 3.39bn, led by Botox Therapeutic and Vraylar.
- Singapore biologics capacity expansion. AbbVie’s USD 223mn expansion of its Tuas site, its only manufacturing facility in Asia, is expected to begin operations in 2026. It adds 24,000L of biologics drug substance capacity to support current products and emerging immunology and oncology assets.
- Constructive long-term outlook. Wall Street is constructive on ABBV as Skyrizi and Rinvoq momentum sustains growth beyond Humira. Pipeline assets such as lutikizumab and obesity candidate ABBV-295, alongside expanded biologics capacity, support longer-term upside into the 2030s. (Tang Kai Jie)
Stock | Sector | PWM Research Recommendation | Type of News | Our Read on the News |
JPMorgan Chase | Financials | No Recommendation | Earnings | Neutral |
- JPMorgan Chase (JPM) reported 3Q2026 diluted EPS of USD 5.57, up 10% yoy and below market consensus of USD 5.92. It incurred USD 498mn of after-tax investment securities losses and missed consensus forecast for the first time in nearly three years. Excluding the losses, return on tangible common equity was 20%.
- Slowdown in dealmaking and bond market trading. Commercial & Investment Bank revenue moderated USD 2.1bn or 9% qoq in 3Q2026. Investment banking fees declined 9% qoq and fixed income markets revenue was down 11% qoq. However, Consumer & Community Banking revenue rose 9% yoy, supported by strong customer acquisition and card activity. Asset & Wealth Management also increased 14% yoy, with USD 263bn in client asset net inflows and assets under management reaching USD 5.2tr.
- Balance-sheet growth remained healthy. Average loans and deposits rose 10% and 8% yoy, respectively. Credit costs totalled USD 2.7b, including USD 2.2bn in net charge-offs and a USD 539mn reserve build. Capital remained solid with CET-1 ratio of 13.9%. JPMorgan distributed USD 4.4bn in common dividends and repurchased USD 664mn of common stock on a net basis.
- JPM is currently trading at a P/B of 2.55x, which is supported by its projected ROE of 18.7% for 2026. Key risks remain macro and geopolitical uncertainties, although we admire the strength of JPM’s fortress balance sheet. (Jonathan Koh)
Stock | Sector | PWM Research Recommendation | Type of News | Our Read on the News |
Procter & Gamble | Consumer Staples | Core Recommendation | Earnings | Positive |
- 1QFY2027 revenue and core EPS beat consensus by 2% and 6% respectively. Procter & Gamble reported 1QFY2027 net sales of USD 23.3bn, up 4% yoy on organic sales, beating consensus by 2%. Operating income was USD 5.9bn, up 1% yoy, with operating margin falling 0.7ppt yoy to 25.5%, core operating margin down 0.8ppt yoy to 25.9%, excluding non-core restructuring charges. Net income was USD 4.7bn, flat yoy, with net margin falling 0.9ppt yoy to 20.3%. Core EPS was USD 2.00, up 1% yoy, beating consensus by 6%. All five segments posted organic growth in 1QFY2027. By category, Beauty/Grooming/Health Care/Fabric & Home Care/Baby, Feminine & Family Care recorded organic sales growth of +5%/+5%/+3%/+5%/+3% yoy, respectively, in 1QFY2027.
- FY2027 organic sales and core EPS guidance maintained despite a larger cost headwind. Management maintained FY2027 organic sales growth of 1% to 3% and core EPS growth of 0% to 3%, and raised all-in sales growth guidance to 2% to 4% to include the Thorne acquisition.
- Key takeaways from earnings call: Middle East conflict costs are expected to intensify from 2QFY2027. The FY2027 commodity headwind was raised by USD 400m to USD 1.4bn, assuming oil at USD 100/barrel, with only partial flow-through in 1QFY2027. Management will offset this through record productivity and pricing with innovation, without jeopardising top-line momentum. Looking ahead, 1HFY2027 organic sales growth is expected at around 3%, implying a slowdown in 2QFY2027 as rising fuel prices pressure consumers.
- US and China recovery gaining momentum. In the US, over 70% of P&G’s top retail partners are now holding or growing share, up from around 50% in 2HFY2026, and management targets above 80% by end-2026. Greater China organic sales rose 8%, led by SK-II (+12%) and Pampers (close to +50%), though the latter was boosted by a competitor’s product issue.
- Expect sideways trading in the short to mid-term as the stock has already rallied close to the consensus target price. Post-earnings to date, PG’s share price has risen 3%, while the consensus target price has been revised up 8% to USD 173.32. Its 1-year forward PE currently stands at 22.7x, above the S&P 500’s current 18.3x and its 10-year historical average of 22.5x. We expect the stock to trade between USD 155 and USD 173 for some time, as investors may rotate away from consumer staples into more attractively valued sectors. (Ejann Hiew)
Stock | Sector | PWM Research Recommendation | Type of News | Our Read on the News |
Netflix Inc (NFLX) | Communication Services | No Recommendation | Earnings | Positive |
- Revenue growth and margin expansion support earnings outlook. Netflix reported 3Q2026 revenue growth of 12% year-on-year to USD 12.9bn, in line with its forecast. Operating margin increased to 34.6%, exceeding expectations primarily due to expense timing. For 2026, management expects revenue of USD 51.1bn, up 13%, and a 31.5% operating margin. Continued investment in differentiated series, films and live events should support engagement and long-term growth.
- Advertising improvements face rollout delays. Netflix announced enhanced advertising targeting and measurement capabilities, helping brands assess campaign effectiveness and reach relevant audiences. However, it lowered its 2026 advertising revenue forecast to approximately USD 2.7bn due to slower-than-expected rollout of some capabilities. Advertising remains a growth opportunity, although the revision highlights that near-term monetisation expectations may be affected.
- International content performance supports engagement and retention. Netflix reported that non-English content now accounts for more than a third of viewing. In India, 3Q viewing hours increased 24% year-on-year, while revenue grew approximately 18% on a currency-neutral basis and paid net additions reached a quarterly record. Strong local programming should support international growth, while churn improved globally and in the US.
- Positive on long-term earnings growth despite advertising delays. Improving profitability, healthy retention and successful international content support its Netflix’s earnings outlook. Advertising expansion provides further growth opportunities, although the reduced forecast highlights execution risks. Continued content investment and cost discipline should support long-term growth, while the timing of advertising improvements warrants monitoring. (Shaina Kamlesh Mahtani)
Stock | Sector | PWM Research Recommendation | Type of News | Our Read on the News |
Walt Disney (DIS) | Communication Services | No Recommendation | Sales / Products | Positive |
- Super Bowl LXI deepens sports and franchise integration. ESPN and Lucasfilm announced a Star Wars Funday Football alternate telecast for Super Bowl LXI, streaming live on Disney+. The animated broadcast will be available across more than 155 markets through live and on-demand viewing. Combining major sports with a popular franchise could attract families and younger viewers, strengthening Disney+’s offering and audience engagement.
- Channel 4 partnership expands Disney+ content offering. Disney and Channel 4 announced a partnership that will bring Channel 4’s linear channel and selected on-demand programming to Disney+ in the UK and Ireland from early 2027. Selected shows will also be available on Disney+ alongside their Channel 4 release. The partnership broadens Disney+’s local content offering and should support engagement and subscriber value.
- Strong football audiences reinforce ESPN’s sports appeal. ESPN reported that Monday Night Football averaged 19m viewers through seven weeks, up 26% year-on-year. The Cowboys–Eagles game attracted 18.8m viewers across its broadcast and streaming outlets, matching the strongest Week 7 audience of the ESPN era. Strong viewing should support advertiser demand and reinforce the value of Disney’s sports offering, although sports-rights costs remain a consideration.
- Positive on Disney’s long-term earnings outlook. Stronger sports audiences, broader local programming and integration of established franchises should support engagement and monetisation. The Channel 4 partnership strengthens Disney+’s content offering, while ESPN’s audience momentum supports its commercial appeal. These developments provide opportunities for longer-term earnings growth, although sports-rights costs, content spending and execution remain key considerations. (Shaina Kamlesh Mahtani)
Stock | Sector | PWM Research Recommendation | Type of News | Our Read on the News |
Verizon Comms Inc (VZ) | Communication Services | No Recommendation | Earnings | Neutral |
- Earnings and cash-flow growth support higher guidance. Verizon reported on 26 October that 3Q2026 revenue rose 1.5% year-on-year to USD 34.3bn, while adjusted EPS increased 8.3% to USD 1.31. Free cash flow grew 12.1% to USD 7.8bn, alongside 406,000 postpaid phone net additions. Management raised its full-year adjusted EPS growth forecast to 7–7.5% and expects free cash-flow growth approaching 12%, reflecting improving customer momentum and operating efficiency.
- Debt tender offers support balance-sheet management. Verizon announced on 29 October offers to repurchase five series of outstanding bonds for an aggregate purchase price of up to USD 500m. The offers are scheduled to expire on 4 November, with settlement expected on 9 November. If completed, the repurchases would reduce outstanding debt, although the impact will depend on participation and the amount accepted.
- Enhanced prepaid plans support customer acquisition and retention. Verizon’s Straight Talk announced upgraded unlimited plans, adding 5G Ultra Wideband access, larger hotspot allowances and expanded international benefits without increasing monthly base prices. Eligible customers also receive USD 10 monthly savings on bundled home internet. Better value should strengthen its appeal to customers, although additional benefits could limit margin improvement.
- Neutral as growth opportunities are balanced by ongoing pressures. Verizon’s stronger customer additions and cash generation should support earnings, while enhanced prepaid plans could help sustain demand. However, modest revenue growth, competition and network spending requirements temper the outlook, making cost discipline and profitable customer retention important to sustained improvement. (Shaina Kamlesh Mahtani)
Type of News | Explanation |
Channel Checks | Industry-wide or supply chain news with implications to a particular sector or company |
Corporate Action | Dividends, special dividends, stock splits, share buybacks, equity / bond financing, M&As, spin-offs and restructuring etc. |
Earnings | Quarterly earnings for US-listed companies. Semi-annual earnings for Hong Kong-listed companies |
Insider Dealing | Company insiders’ buying / selling of stocks and derivatives of the company |
Investor Action | Leading investor buying / selling including activist investor actions |
Investor Roadshow | Deal and non-deal roadshows, reverse roadshows (analyst days), and company meetings at investment conferences |
Legal / Regulatory | Lawsuits, legislature/regulation changes, other regulatory events |
Macro / Industry Data | Regular economic or industry data related to the sector or stock |
Sales / Products | Sales or product related news, such as monthly sales or new product launches |
Public Event | Public speeches and appearances by companies in the media or industry conferences |
Appendix A – US Stock Model Portfolio
Analyst
Wendy Chen
wendy.chen@uobkh.comAnalyst
Wang Qi, CFA
qi.wang@uobkh.comAnalyst
In collaboration with UOBKH Institutional Research
Disclosures and disclaimers
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


