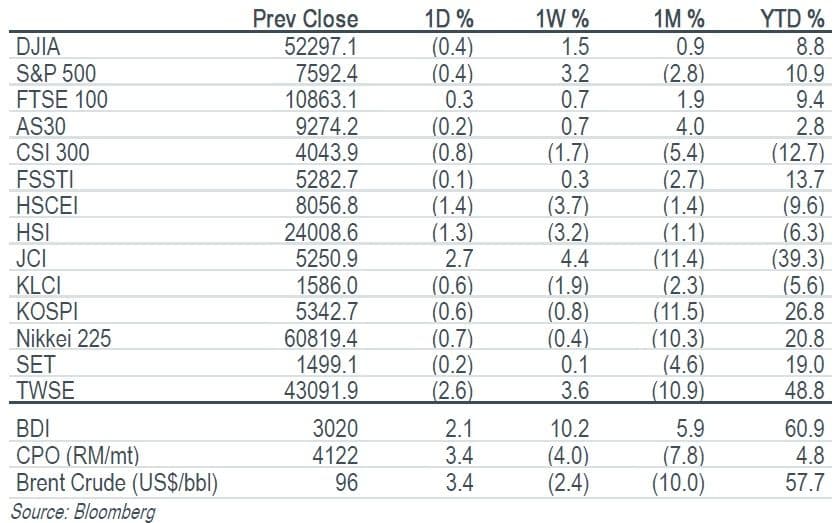
Key Indices
Top Stories
Company Results | Asset World Corporation (AWC TB/BUY/Bt3.18/Target: Bt3.90)
- AWC reported a core profit of Bt457m, supported by 17.6% yoy hotel revenue growth and 25.4% RevPar growth, driven by Chinese tourist recovery and major events such as Gastech. Lower refinancing costs also supported margin expansion. We expect a strong 4Q26 hotel performance, with forward bookings indicating 20% yoy room revenue growth, boosted by major events in Bangkok and Pattaya, including the IMF-World Bank Group Annual Meetings and Tomorrowland. Maintain BUY with a target price of Bt3.90.
Company Results | Charoen Pokphand Foods (CPF TB/BUY/Bt20.20/Target: Bt25.00)
- CPF reported a 3Q26 net profit of Bt5.2b (+0.8% yoy, +28.2% qoq), significantly exceeding our estimate, mainly driven by a higher-than-expected share of profit from the restructuring of its swine business in China. We remain positive on its 2027 earnings outlook on the back of: a) an upward livestock price cycle in Thailand and Vietnam, and b) lower losses from its China swine operations following the disposal of underperforming farms. Maintain BUY with a target price of Bt25.00.
Company Results | WHA Corporation (WHA TB/BUY/Bt5.10/Target: Bt6.10)
- WHA reported a 3Q26 net profit of Bt756m (+19% yoy, +15% qoq), missing our and consensus forecasts by 15% and 19% respectively due to weaker-than-expected revenue and gross margin. Total revenue reached Bt2.26b, up 17% yoy but down 19% qoq. Land sales rose 40% qoq to 346 rai, bringing 9M26 sales to 62% of its full-year target. Maintain BUY with an unchanged target price of Bt6.10.
Company Update | Thai Oil (TOP TB/BUY/Bt59.00/Target: Bt100.00)
- We expect GRM to recover, supported by stronger middle distillate demand during the winter season and extensive refinery maintenance shutdowns across the US and Asia in 1H27. The CFP project continues to make steady progress, with TOP's management maintaining its target for full COD by 3Q28. Meanwhile, a conclusion on the ERU project is expected by end-Jan 27. TOP also maintains a strong financial position, and we estimate a 2027 dividend of Bt4.00/share. Maintain BUY. Target price: Bt100.00.
What’s Inside
Company Results | Berli Jucker (BJC TB/BUY/Bt19.00/Target: Bt24.50)
- BJC’s 3Q26 core profit came in at Bt1.27b, up 36% yoy, in line with our forecast. Modern retail was the key earnings driver, with both Big C and MMVN showing a recovery. We expect core profit to grow 21% yoy in 2027, driven primarily by Big C’s earnings recovery following cost reduction initiatives. Full-year consolidation of MMVN will provide an additional earnings boost. Maintain BUY with a target price of Bt24.50, based on 2027F PE of 17x.
Company Results | Bumrungrad Hospital (BH TB/BUY/Bt193.00/Target: Bt240.00)
- BH reported a net profit of Bt2.07b (+1.5% yoy, +9.3% qoq), in line with expectations, on revenue of Bt6.7b (+2.8% yoy). We expect stronger Middle Eastern patient inflow in 4Q26, while Bangladeshi patient arrivals are recovering following visa normalisation. BH is also expanding its Bangladesh presence through a new clinic and may enter Iraq following a GOP agreement with its government. Maintain BUY with a target price of Bt240.00, based on 18.0x 2027F EV/EBITDA.
Company Results | GFPT Plc. (GFPT TB/BUY/Bt9.70/Target: Bt11.40)
- GFPT’s core profit came in at Bt631m (-11.2% yoy, +8.4% qoq). Core profit was 8% above our estimate due to a better-than-expected gross profit margin. Expect 4Q26 earnings to decline qoq but increase yoy on the back of higher ASPs for chicken and by-products, as well as export shipments that were postponed from 3Q26 to 4Q26. Maintain BUY with a target price of Bt11.40.
Company Results | Plan B Media (PLANB TB/BUY/Bt8.60/Target: Bt9.80)
- PLANB reported a 3Q26 net profit of Bt320m (+10.2% yoy, +7.7% qoq). Earnings came in 17% above both our estimate and the market consensus. We expect PLANB’s 4Q26 earnings to reach a record high, driven by peak-season OOH demand, growth in high-margin engagement revenue, and a fullquarter contribution from COM7. The investment in COM7 also diversifies PLANB’s media business and provides exposure to Thailand’s growing IT retail sector. Maintain BUY with a higher target price of Bt9.80.
Company Results | PTT (PTT TB/BUY/Bt38.25/Target: Bt48.00)
- PTT reported 3Q26 net profit of Bt40.55b, down 23% qoq, in line with our estimate and 9% above consensus. The qoq decline was mainly attributable to seasonally lower sales volumes and higher gas costs. Meanwhile, earnings contributions from subsidiaries and affiliates increased both qoq and yoy, particularly from the refinery businesses, which benefitted from strong market GIM. However, we expect PTT's 4Q26 net profit to decline qoq. We forecast a 2026 dividend of Bt3.00/share. Maintain BUY; target price: Bt48.00.
Company Results | Thai Airways (THAI TB/BUY/Bt5.15/Target: Bt6.80)
- THAI reported a weaker-than-expected net loss of Bt432m in 3Q26, mainly due to flood compensation and operating expenses, while core profit stood at Bt60m excluding these items. Around 40% of 4Q26 fuel consumption is hedged, with further protection from potential fuel surcharge adjustments. THAI is also leveraging its cost advantage to capture domestic market share amid resilient business and premium leisure demand. Maintain BUY with a target price of Bt6.80, supported by an improving 4Q26 outlook and high-season travel demand.
Top Stories
Company Results | Asset World Corporation (AWC TB/BUY/Bt3.18/Target: Bt3.90)
- AWC reported a core profit of Bt457m, supported by 17.6% yoy hotel revenue growth and 25.4% RevPar growth, driven by Chinese tourist recovery and major events such as Gastech. Lower refinancing costs also supported margin expansion. We expect a strong 4Q26 hotel performance, with forward bookings indicating 20% yoy room revenue growth, boosted by major events in Bangkok and Pattaya, including the IMF-World Bank Group Annual Meetings and Tomorrowland. Maintain BUY with a target price of Bt3.90.
Company Results | Charoen Pokphand Foods (CPF TB/BUY/Bt20.20/Target: Bt25.00)
- CPF reported a 3Q26 net profit of Bt5.2b (+0.8% yoy, +28.2% qoq), significantly exceeding our estimate, mainly driven by a higher-than-expected share of profit from the restructuring of its swine business in China. We remain positive on its 2027 earnings outlook on the back of: a) an upward livestock price cycle in Thailand and Vietnam, and b) lower losses from its China swine operations following the disposal of underperforming farms. Maintain BUY with a target price of Bt25.00.
Company Results | WHA Corporation (WHA TB/BUY/Bt5.10/Target: Bt6.10)
- WHA reported a 3Q26 net profit of Bt756m (+19% yoy, +15% qoq), missing our and consensus forecasts by 15% and 19% respectively due to weaker-than-expected revenue and gross margin. Total revenue reached Bt2.26b, up 17% yoy but down 19% qoq. Land sales rose 40% qoq to 346 rai, bringing 9M26 sales to 62% of its full-year target. Maintain BUY with an unchanged target price of Bt6.10.
Company Update | Thai Oil (TOP TB/BUY/Bt59.00/Target: Bt100.00)
- We expect GRM to recover, supported by stronger middle distillate demand during the winter season and extensive refinery maintenance shutdowns across the US and Asia in 1H27. The CFP project continues to make steady progress, with TOP's management maintaining its target for full COD by 3Q28. Meanwhile, a conclusion on the ERU project is expected by end-Jan 27. TOP also maintains a strong financial position, and we estimate a 2027 dividend of Bt4.00/share. Maintain BUY. Target price: Bt100.00.
What’s Inside
Company Results | Berli Jucker (BJC TB/BUY/Bt19.00/Target: Bt24.50)
- BJC’s 3Q26 core profit came in at Bt1.27b, up 36% yoy, in line with our forecast. Modern retail was the key earnings driver, with both Big C and MMVN showing a recovery. We expect core profit to grow 21% yoy in 2027, driven primarily by Big C’s earnings recovery following cost reduction initiatives. Full-year consolidation of MMVN will provide an additional earnings boost. Maintain BUY with a target price of Bt24.50, based on 2027F PE of 17x.
Company Results | Bumrungrad Hospital (BH TB/BUY/Bt193.00/Target: Bt240.00)
- BH reported a net profit of Bt2.07b (+1.5% yoy, +9.3% qoq), in line with expectations, on revenue of Bt6.7b (+2.8% yoy). We expect stronger Middle Eastern patient inflow in 4Q26, while Bangladeshi patient arrivals are recovering following visa normalisation. BH is also expanding its Bangladesh presence through a new clinic and may enter Iraq following a GOP agreement with its government. Maintain BUY with a target price of Bt240.00, based on 18.0x 2027F EV/EBITDA.
Company Results | GFPT Plc. (GFPT TB/BUY/Bt9.70/Target: Bt11.40)
- GFPT’s core profit came in at Bt631m (-11.2% yoy, +8.4% qoq). Core profit was 8% above our estimate due to a better-than-expected gross profit margin. Expect 4Q26 earnings to decline qoq but increase yoy on the back of higher ASPs for chicken and by-products, as well as export shipments that were postponed from 3Q26 to 4Q26. Maintain BUY with a target price of Bt11.40.
Company Results | Plan B Media (PLANB TB/BUY/Bt8.60/Target: Bt9.80)
- PLANB reported a 3Q26 net profit of Bt320m (+10.2% yoy, +7.7% qoq). Earnings came in 17% above both our estimate and the market consensus. We expect PLANB’s 4Q26 earnings to reach a record high, driven by peak-season OOH demand, growth in high-margin engagement revenue, and a fullquarter contribution from COM7. The investment in COM7 also diversifies PLANB’s media business and provides exposure to Thailand’s growing IT retail sector. Maintain BUY with a higher target price of Bt9.80.
Company Results | PTT (PTT TB/BUY/Bt38.25/Target: Bt48.00)
- PTT reported 3Q26 net profit of Bt40.55b, down 23% qoq, in line with our estimate and 9% above consensus. The qoq decline was mainly attributable to seasonally lower sales volumes and higher gas costs. Meanwhile, earnings contributions from subsidiaries and affiliates increased both qoq and yoy, particularly from the refinery businesses, which benefitted from strong market GIM. However, we expect PTT's 4Q26 net profit to decline qoq. We forecast a 2026 dividend of Bt3.00/share. Maintain BUY; target price: Bt48.00.
Company Results | Thai Airways (THAI TB/BUY/Bt5.15/Target: Bt6.80)
- THAI reported a weaker-than-expected net loss of Bt432m in 3Q26, mainly due to flood compensation and operating expenses, while core profit stood at Bt60m excluding these items. Around 40% of 4Q26 fuel consumption is hedged, with further protection from potential fuel surcharge adjustments. THAI is also leveraging its cost advantage to capture domestic market share amid resilient business and premium leisure demand. Maintain BUY with a target price of Bt6.80, supported by an improving 4Q26 outlook and high-season travel demand.
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


