Periodic/Sector reports
Retail: A Sign Of Structural Improvement In The Thai Retail Industry
OVERWEIGHT (Upgraded)
Analyst
Highlights
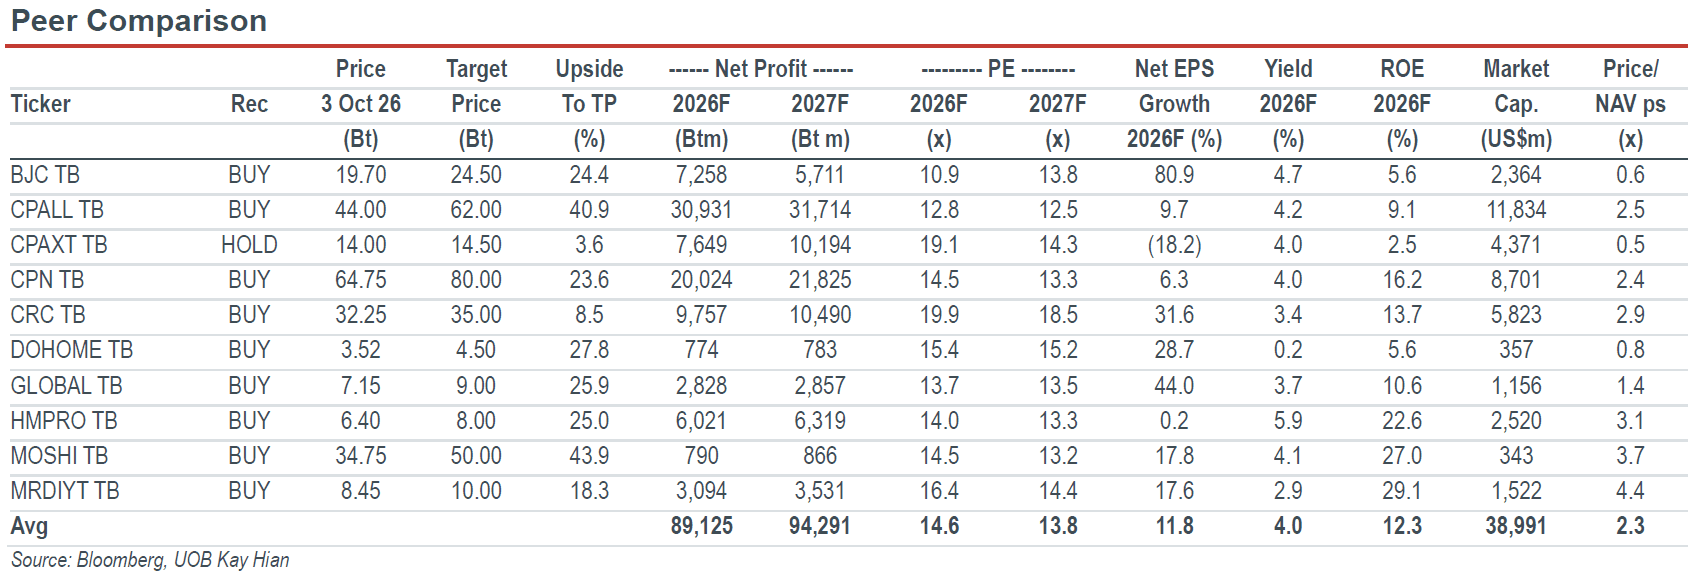
- Upgrade to OVERWEIGHT; we favour BJC, CPN and GLOBAL, with BJC as our top pick on the back of a structural recovery.
- The easing of competition in the modern grocery segment, margin enhancement in home improvement, and attractive valuations in lifestyle retail underpin our positive outlook for the retail sector.
- In Oct 26, SSSG turned positive in almost all segments, with 4Q26 expected to be promising.
- We raise BJC’s 2027 core earnings by 13% to reflect the structural recovery in the modern retail business and raise target price to Bt24.50.
Analysis
- The top performing sector over the past 30 days. The retail sector’s share prices rose 2.3% in Oct 26, outperforming the SET Index (-5.7%) and making it the top performing sector over the past 30 days. Fund flows rotated out of growth and cyclical stocks, such as electronics (-27.6%) and petrochemicals (-11.1%), into laggard sectors, including retail (+2.3%). Outperforming stocks included our top picks BJC (+13.6%), GLOBAL (+8.3%), and CRC (+6.7%), supported by specific structural improvements. Foreign ownership in the retail sector also increased by 13bp to 19.9%. The sector’s outperformance was supported by fund flows and improving fundamentals.
- In Oct 26, SSSG turned positive in almost all segments, with 4Q26 expected to be promising. For modern grocery, supermarket- and hypermarket-based retailers such as BJC and CRC outperformed convenience store-based CPALL in Oct 26. Supply chain disruptions following the Bangkok floods had a less severe impact on hypermarkets and supermarkets, given their significantly higher inventory levels. Food categories were the key outperformers, while non-food categories, particularly home-related products, also performed well on stronger demand for home repairs. We expect modern grocery same-store sales growth (SSSG) to remain strong throughout 4Q26, supported by a low base in 4Q25 following the Half-Half Plus co-payment scheme, which diverted spending from modern trade to traditional mom-and-pop stores. Home improvement retailers saw SSSG surge in Oct 26, driven by post-flood demand for home repairs and renovations, with HMPRO being the key beneficiary. Lifestyle retailers’ SSSG improved in Oct 26 following the disruption caused by the Bangkok floods in Sep 26. With continued gross margin expansion and lower interest expenses, we expect 4Q26 core earnings to improve.
Highlights
- Upgrade to OVERWEIGHT; we favour BJC, CPN and GLOBAL, with BJC as our top pick on the back of a structural recovery.
- The easing of competition in the modern grocery segment, margin enhancement in home improvement, and attractive valuations in lifestyle retail underpin our positive outlook for the retail sector.
- In Oct 26, SSSG turned positive in almost all segments, with 4Q26 expected to be promising.
- We raise BJC’s 2027 core earnings by 13% to reflect the structural recovery in the modern retail business and raise target price to Bt24.50.
Analysis
- The top performing sector over the past 30 days. The retail sector’s share prices rose 2.3% in Oct 26, outperforming the SET Index (-5.7%) and making it the top performing sector over the past 30 days. Fund flows rotated out of growth and cyclical stocks, such as electronics (-27.6%) and petrochemicals (-11.1%), into laggard sectors, including retail (+2.3%). Outperforming stocks included our top picks BJC (+13.6%), GLOBAL (+8.3%), and CRC (+6.7%), supported by specific structural improvements. Foreign ownership in the retail sector also increased by 13bp to 19.9%. The sector’s outperformance was supported by fund flows and improving fundamentals.
- In Oct 26, SSSG turned positive in almost all segments, with 4Q26 expected to be promising. For modern grocery, supermarket- and hypermarket-based retailers such as BJC and CRC outperformed convenience store-based CPALL in Oct 26. Supply chain disruptions following the Bangkok floods had a less severe impact on hypermarkets and supermarkets, given their significantly higher inventory levels. Food categories were the key outperformers, while non-food categories, particularly home-related products, also performed well on stronger demand for home repairs. We expect modern grocery same-store sales growth (SSSG) to remain strong throughout 4Q26, supported by a low base in 4Q25 following the Half-Half Plus co-payment scheme, which diverted spending from modern trade to traditional mom-and-pop stores. Home improvement retailers saw SSSG surge in Oct 26, driven by post-flood demand for home repairs and renovations, with HMPRO being the key beneficiary. Lifestyle retailers’ SSSG improved in Oct 26 following the disruption caused by the Bangkok floods in Sep 26. With continued gross margin expansion and lower interest expenses, we expect 4Q26 core earnings to improve.
OVERWEIGHT (Upgraded)
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


