

Periodic/Sector reports
Banking: 3Q26: Results In Line; Continued Improvement In Asset Quality
OVERWEIGHT (Maintained)
Analyst
Analyst
Panjarat Thaweesriprasert
Highlights
- Banks reported a combined net profit of Bt63.8b, down 10% yoy and flat qoq.
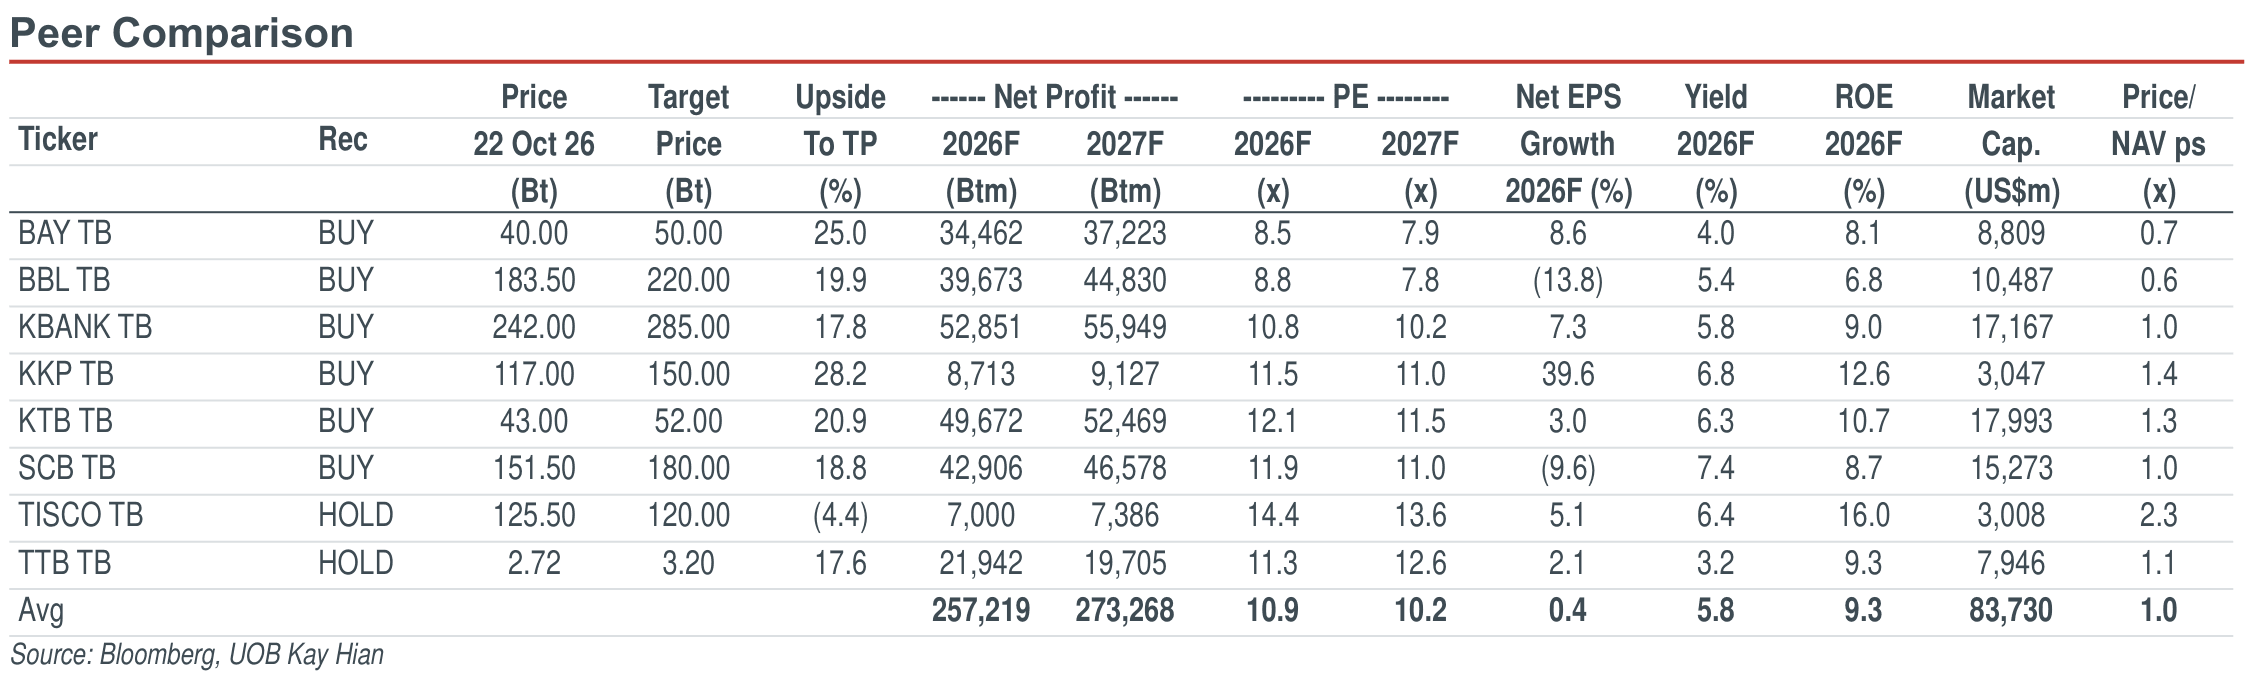
- Maintain OVERWEIGHT on the sector. Top picks: KBANK and KTB.
Analysis
- Results in line. In 3Q26, banks under our coverage reported a combined net profit of Bt63.8b, down 10% yoy and flat qoq, in line with our and market’s expectation. Net interest income (NII) dropped 5% yoy but was up 2% qoq. NIM widened from 3.42% in 2Q26 to 3.45% in 3Q26. Meanwhile, non-interest income (non-II) declined 14% yoy and 9% qoq. The banking sector’s pre-provision operating profit (PPOP) declined 9% yoy and 3% qoq in 3Q26.
- An impressive improvement in NII. In 3Q26, all banks under our coverage reported an increase of 2% qoq in NII. Only KBANK and KTB have reported a 1bp qoq reduction in NIM. However, many banks guided that there is limited room to decrease funding costs.
- Strong yoy increase in net fee and service income in 3Q26. Banks under our coverage reported an increase of 7% yoy in net fee and service income but declined 1% qoq. Almost all banks reported an increase yoy in net fee and service income except TISCO, which reported a reduction 2% yoy. Banks attributed this mainly to the wealth business, which benefitted from favourable US and domestic stock markets. Meanwhile, some banks reported a reduction qoq in net fee and service income due to less favourable wealth management and capital market conditions and the impact from new standardised fee regulations. KKP reported a jump in net fee and service income by 47% yoy and 21% qoq, mainly driven by the wealth business. We expect banks to continue to focus on growing the wealth business to help boost non-II going forward.
- Continued improvement in asset quality for the banking sector. The banking sector reported a 24bp yoy and 8bp qoq reduction in credit cost. Meanwhile, NPL ratio for the banking sector improved slightly by 2bp qoq in 3Q26. Banks said they have adequate provisions to cushion against many uncertainties including flooding in Bangkok in late-Sep 26. As banks are likely to remain cautious with lending, we still expect to see a further improvement in banking asset quality and credit cost in 4Q26.
- Rooms for capital management. We reiterate our view that banks will at least maintain their dividend payout ratio (DPR) in 2026. TTB has just announced its fifth share buyback programme, with a total budget of Bt14b through a general offer. KBANK has utilised 40% of its total share buyback budget and ended the programme early. We expect to see an increase in dividend payment from the remaining buyback budget.
Highlights
- Banks reported a combined net profit of Bt63.8b, down 10% yoy and flat qoq.
- Maintain OVERWEIGHT on the sector. Top picks: KBANK and KTB.
Analysis
- Results in line. In 3Q26, banks under our coverage reported a combined net profit of Bt63.8b, down 10% yoy and flat qoq, in line with our and market’s expectation. Net interest income (NII) dropped 5% yoy but was up 2% qoq. NIM widened from 3.42% in 2Q26 to 3.45% in 3Q26. Meanwhile, non-interest income (non-II) declined 14% yoy and 9% qoq. The banking sector’s pre-provision operating profit (PPOP) declined 9% yoy and 3% qoq in 3Q26.
- An impressive improvement in NII. In 3Q26, all banks under our coverage reported an increase of 2% qoq in NII. Only KBANK and KTB have reported a 1bp qoq reduction in NIM. However, many banks guided that there is limited room to decrease funding costs.
- Strong yoy increase in net fee and service income in 3Q26. Banks under our coverage reported an increase of 7% yoy in net fee and service income but declined 1% qoq. Almost all banks reported an increase yoy in net fee and service income except TISCO, which reported a reduction 2% yoy. Banks attributed this mainly to the wealth business, which benefitted from favourable US and domestic stock markets. Meanwhile, some banks reported a reduction qoq in net fee and service income due to less favourable wealth management and capital market conditions and the impact from new standardised fee regulations. KKP reported a jump in net fee and service income by 47% yoy and 21% qoq, mainly driven by the wealth business. We expect banks to continue to focus on growing the wealth business to help boost non-II going forward.
- Continued improvement in asset quality for the banking sector. The banking sector reported a 24bp yoy and 8bp qoq reduction in credit cost. Meanwhile, NPL ratio for the banking sector improved slightly by 2bp qoq in 3Q26. Banks said they have adequate provisions to cushion against many uncertainties including flooding in Bangkok in late-Sep 26. As banks are likely to remain cautious with lending, we still expect to see a further improvement in banking asset quality and credit cost in 4Q26.
- Rooms for capital management. We reiterate our view that banks will at least maintain their dividend payout ratio (DPR) in 2026. TTB has just announced its fifth share buyback programme, with a total budget of Bt14b through a general offer. KBANK has utilised 40% of its total share buyback budget and ended the programme early. We expect to see an increase in dividend payment from the remaining buyback budget.
OVERWEIGHT (Maintained)
Analyst
Analyst
Panjarat Thaweesriprasert
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


