Company Coverage
Tisco Financial Group (TISCO TB): 3Q26: Results In Line; Clean Asset Quality With A High Buffer
HOLD (Maintained)
Current price:
Target price:
Upside:
Bt124.50
Bt120.00
-3.6%
Analyst
Highlights
- TISCO reported a net profit of Bt1.8b in 3Q26, up 4% yoy and 2% qoq.
- Expect limited impact from the flooding in late-Sep 26.
- Maintain HOLD with a target price of Bt120.00.
Analysis
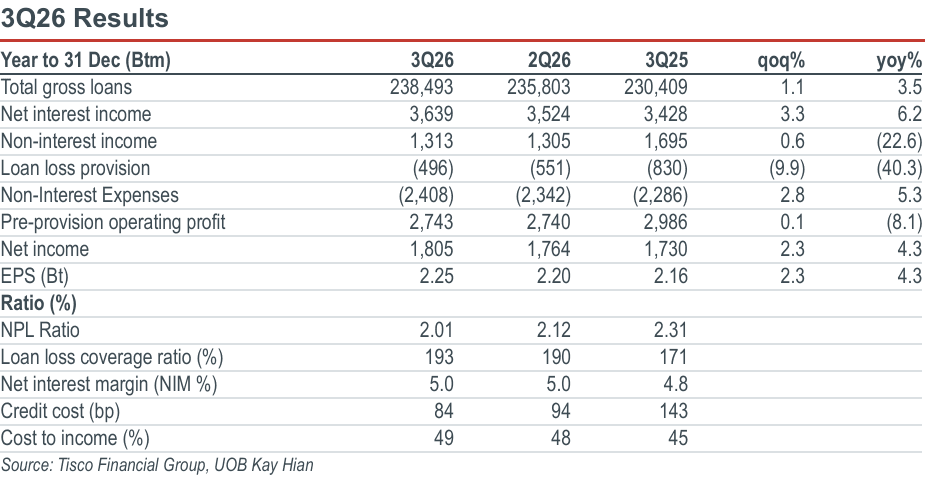
- 3Q26 results in line. TISCO Financial Group (TISCO) posted a 3Q26 net profit of Bt1.8b (+4% yoy, +2% qoq), in line with our and market expectations. Pre-provision operating profit declined by 8% yoy but was flat qoq in 3Q26.
- Neutral tone during analyst meeting. Management stated that there should be limited impact from the flooding in late-Sep 26. The bank is confident that its provisioning is sufficient. Its current coverage ratio is adequate to buffer against uncertainties. TISCO is also less concerned about asset quality compared with during 1H26.
- Loan portfolio grew yoy and qoq. TISCO’s loan portfolio grew 3.5% yoy and 1% qoq. Corporate loans grew 4.7% qoq. Meanwhile, SME loans grew 2.6% qoq. New-car hire-purchase (HP) was flat qoq in 3Q26 (+2.4% ytd). Meanwhile, motorcycle HP rose 2.7% qoq in 3Q26 (+11.2% ytd). The increase in HP is in line with the company’s guidance. TISCO also guided that these two segments should see continued loan growth.
Highlights
- TISCO reported a net profit of Bt1.8b in 3Q26, up 4% yoy and 2% qoq.
- Expect limited impact from the flooding in late-Sep 26.
- Maintain HOLD with a target price of Bt120.00.
Analysis
- 3Q26 results in line. TISCO Financial Group (TISCO) posted a 3Q26 net profit of Bt1.8b (+4% yoy, +2% qoq), in line with our and market expectations. Pre-provision operating profit declined by 8% yoy but was flat qoq in 3Q26.
- Neutral tone during analyst meeting. Management stated that there should be limited impact from the flooding in late-Sep 26. The bank is confident that its provisioning is sufficient. Its current coverage ratio is adequate to buffer against uncertainties. TISCO is also less concerned about asset quality compared with during 1H26.
- Loan portfolio grew yoy and qoq. TISCO’s loan portfolio grew 3.5% yoy and 1% qoq. Corporate loans grew 4.7% qoq. Meanwhile, SME loans grew 2.6% qoq. New-car hire-purchase (HP) was flat qoq in 3Q26 (+2.4% ytd). Meanwhile, motorcycle HP rose 2.7% qoq in 3Q26 (+11.2% ytd). The increase in HP is in line with the company’s guidance. TISCO also guided that these two segments should see continued loan growth.
HOLD (Maintained)
Current price:
Target price:
Upside:
Bt124.50
Bt120.00
-3.6%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


