Company Coverage
Stecon Group (STECON TB): 3Q26: Record-high Revenue
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt18.40
Bt26.50
44.02%
Bt22.00
Analyst
Analyst
Panjarat Thaweesriprasert
Highlights
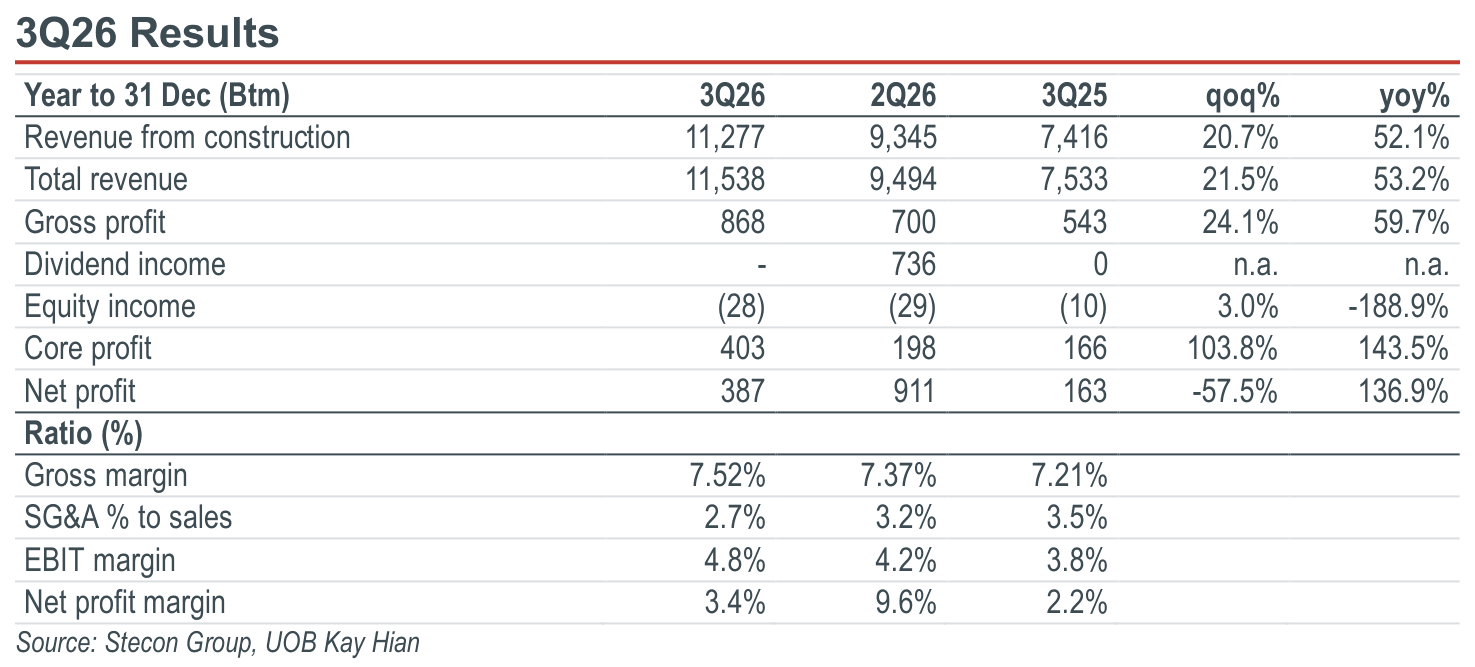
- STECON reported 3Q26 earnings of Bt387m (+137% yoy, -58% qoq).
- Revenue reached a record high of Bt11.5b (+53% yoy, +22% qoq), supported by strong progress in ongoing construction projects.
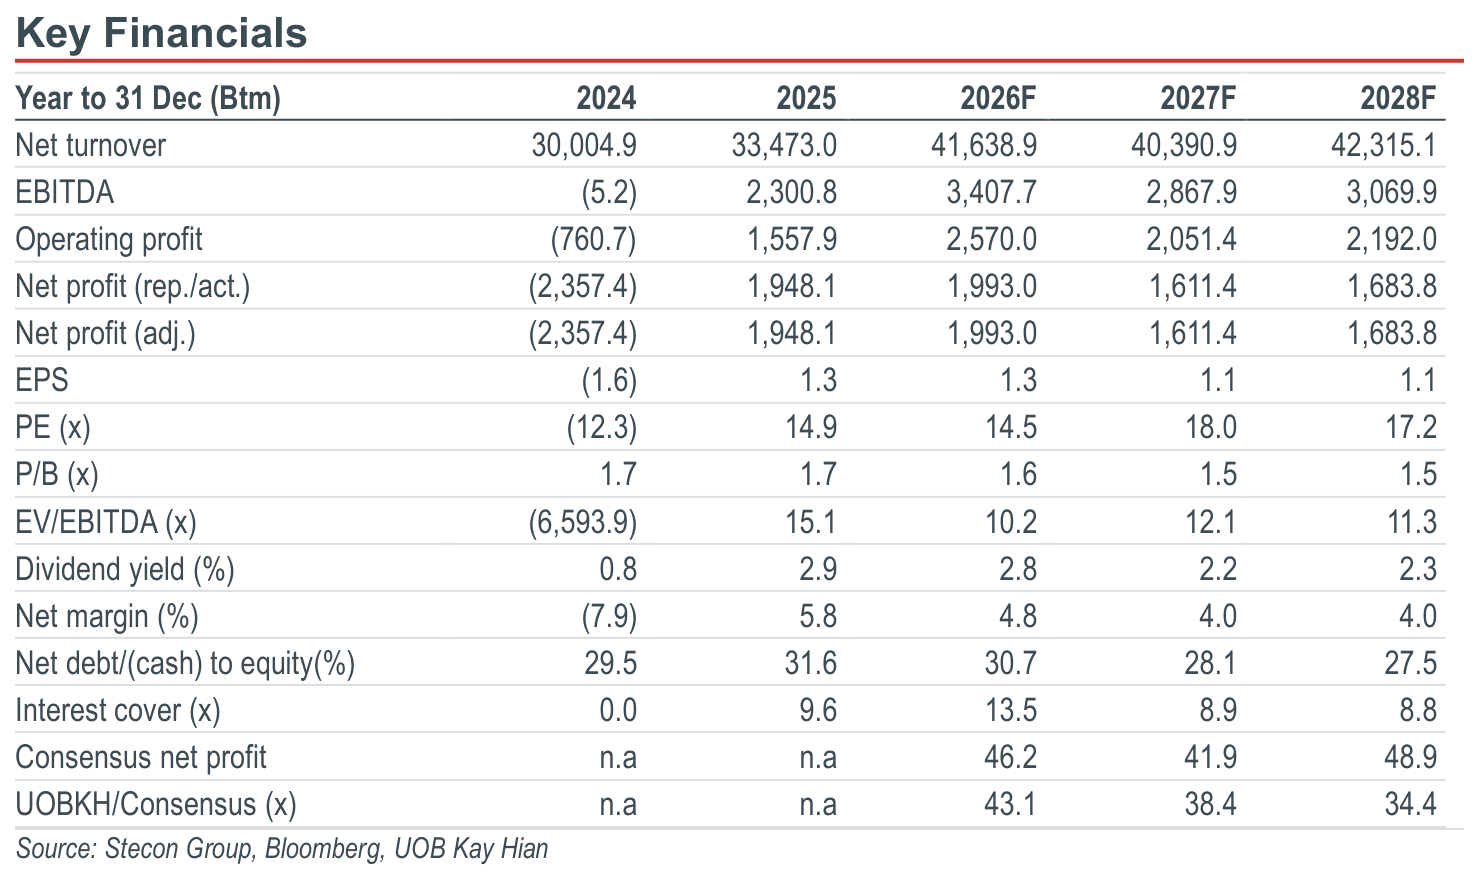
- Maintain BUY and roll over to 2027 with a target price of Bt26.50 (previously Bt22.00).
Analysis
- 3Q26 results beat. Stecon Group (STECON) reported 3Q26 net profit of Bt387m (+137% yoy, -58% qoq). The qoq decline was mainly due to the absence of dividend income from Gulf Development (GULF) received in 2Q26. Excluding dividend income and equity income, core profit reached Bt403m (+144% yoy, +104% qoq).
- Record-high quarterly revenue. STECON reported 3Q26 total revenue of Bt11.5b (+53% yoy, +22% qoq), driven by construction revenue of Bt11.3b (+52% yoy, +21% qoq). The strong growth was supported by progress in ongoing projects, including DCs, mass transit rail and clean energy projects. We expect construction revenue to remain strong at above Bt10b in 4Q26, supported by seasonally higher construction activity.
Highlights
- STECON reported 3Q26 earnings of Bt387m (+137% yoy, -58% qoq).
- Revenue reached a record high of Bt11.5b (+53% yoy, +22% qoq), supported by strong progress in ongoing construction projects.
- Maintain BUY and roll over to 2027 with a target price of Bt26.50 (previously Bt22.00).
Analysis
- 3Q26 results beat. Stecon Group (STECON) reported 3Q26 net profit of Bt387m (+137% yoy, -58% qoq). The qoq decline was mainly due to the absence of dividend income from Gulf Development (GULF) received in 2Q26. Excluding dividend income and equity income, core profit reached Bt403m (+144% yoy, +104% qoq).
- Record-high quarterly revenue. STECON reported 3Q26 total revenue of Bt11.5b (+53% yoy, +22% qoq), driven by construction revenue of Bt11.3b (+52% yoy, +21% qoq). The strong growth was supported by progress in ongoing projects, including DCs, mass transit rail and clean energy projects. We expect construction revenue to remain strong at above Bt10b in 4Q26, supported by seasonally higher construction activity.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt18.40
Bt26.50
44.02%
Bt22.00
Analyst
Analyst
Panjarat Thaweesriprasert
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


