Company Coverage
KCE (Thailand) (KCE TB): Management Guides A Strong 4Q26-2027 Outlook; More Attractive Valuation Presents Trading Opportunities
BUY (Upgraded)
Current price:
Target price:
Upside:
Previous TP :
Bt58.25
Bt70.00
20.17%
Bt80.00
Analyst
Analyst
Sirithat Prasertwuti
Highlights
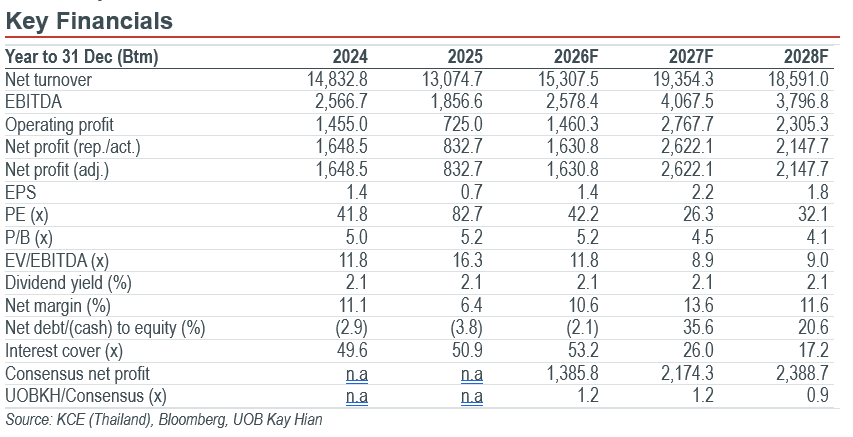
KCE reported a 3Q26 net profit of Bt485m (+63% yoy, +76% qoq) last Thursday. Despite the strong earnings growth, the earnings miss was mainly due to the floods in late 3Q26.|
The tone during the analyst meeting was slightly positive. Management expects to raise PCB prices by 13-15% qoq in 4Q26 (vs its previous guidance of 8-10%), with a further 8-10% increase expected in 2027.
We upgrade KCE to BUY with a target price of Bt70.00, as we see trading buy opportunities in 4Q26-1Q27. Its current valuation appears more attractive following the recent semiconductor sector sell-off.
Analysis
Strong 3Q26 earnings driven by higher PCB prices, but missed expectations due to minor order delays caused by floods in late-September and higher raw material prices. KCE reported a 3Q26 net profit of Bt485m (+63% yoy, +76% qoq), below our and consensus estimates by 8% and 5%. Total revenue came in at Bt3.91b (+13.6% yoy, +9.5% qoq), below our and consensus estimates by 5% and 7% respectively. Overall, despite the strong earnings growth, the earnings miss was mainly due to: a) temporary logistics issues caused by the floods in late-3Q26, which delayed some orders into 4Q26, and b) a lower-than-expected gross margin of 22.4% (vs management's 2H26 guidance of 24-25%) due to continued increases in the prices of raw materials during the quarter, which are expected to be passed on to customers via higher PCB prices in the next quarter. Currently, KCE's backlog stands at around 9% of sales (Bt330m). The backlog of finished goods that was delayed from 3Q26 (accounting for 3.2% of sales) is expected to be delivered in 4Q26.
Tone was slightly positive; 4Q26 earnings is expected to be strong, driven by expected second PCB price increase of 13-15% qoq and strong volume shipments. Overall, the tone during the analyst meeting was slightly positive. 4Q26 earnings are expected to be very strong as management has guided for sales growth of 24-27% qoq in 4Q26, driven by a 13-15% qoq increase in PCB prices (vs previous 8-9% qoq guidance) and 10% qoq growth in PCB shipment volumes, supported by expected market share gains. Higher PCB price increases in 4Q26 reflect a continued increase in raw maw material, which rose every month by 15-25% mom during 3Q26. Qtd, management has received orders totalling 7.6m sf (vs 6.3m sf in 3Q26), but targets shipments of only 7m sf due to the ongoing raw material constraints and the usual five-day factory shutdown ahead of the New Year holiday.
Highlights
KCE reported a 3Q26 net profit of Bt485m (+63% yoy, +76% qoq) last Thursday. Despite the strong earnings growth, the earnings miss was mainly due to the floods in late 3Q26.|
The tone during the analyst meeting was slightly positive. Management expects to raise PCB prices by 13-15% qoq in 4Q26 (vs its previous guidance of 8-10%), with a further 8-10% increase expected in 2027.
We upgrade KCE to BUY with a target price of Bt70.00, as we see trading buy opportunities in 4Q26-1Q27. Its current valuation appears more attractive following the recent semiconductor sector sell-off.
Analysis
Strong 3Q26 earnings driven by higher PCB prices, but missed expectations due to minor order delays caused by floods in late-September and higher raw material prices. KCE reported a 3Q26 net profit of Bt485m (+63% yoy, +76% qoq), below our and consensus estimates by 8% and 5%. Total revenue came in at Bt3.91b (+13.6% yoy, +9.5% qoq), below our and consensus estimates by 5% and 7% respectively. Overall, despite the strong earnings growth, the earnings miss was mainly due to: a) temporary logistics issues caused by the floods in late-3Q26, which delayed some orders into 4Q26, and b) a lower-than-expected gross margin of 22.4% (vs management's 2H26 guidance of 24-25%) due to continued increases in the prices of raw materials during the quarter, which are expected to be passed on to customers via higher PCB prices in the next quarter. Currently, KCE's backlog stands at around 9% of sales (Bt330m). The backlog of finished goods that was delayed from 3Q26 (accounting for 3.2% of sales) is expected to be delivered in 4Q26.
Tone was slightly positive; 4Q26 earnings is expected to be strong, driven by expected second PCB price increase of 13-15% qoq and strong volume shipments. Overall, the tone during the analyst meeting was slightly positive. 4Q26 earnings are expected to be very strong as management has guided for sales growth of 24-27% qoq in 4Q26, driven by a 13-15% qoq increase in PCB prices (vs previous 8-9% qoq guidance) and 10% qoq growth in PCB shipment volumes, supported by expected market share gains. Higher PCB price increases in 4Q26 reflect a continued increase in raw maw material, which rose every month by 15-25% mom during 3Q26. Qtd, management has received orders totalling 7.6m sf (vs 6.3m sf in 3Q26), but targets shipments of only 7m sf due to the ongoing raw material constraints and the usual five-day factory shutdown ahead of the New Year holiday.
BUY (Upgraded)
Current price:
Target price:
Upside:
Previous TP :
Bt58.25
Bt70.00
20.17%
Bt80.00
Analyst
Analyst
Sirithat Prasertwuti
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


