Company Coverage
HANA (Thailand) (HANA TB): Strong AI Pipeline And Sustained High Utilisation To Drive Earnings Growth In 2027-28
BUY (Maintained)
Current price:
Target price:
Upside:
Bt43.50
Bt56.00
28.74%
Analyst
Analyst
Sirithat Prasertwuti
Highlights
- Last week, HANA reported a 3Q26 net profit of Bt693m (+4,588% yoy, +112% qoq), beating expectation by roughly 100%.
- HANA’s AI exposure reached 6% of 3Q26 total revenue, mainly driven by high-density PCBA, while cooling sales needs time to ramp up in 4Q26-1Q27.
- HANA has signed a third contract for a solid-state cooling project with Phononics and substantial new customer for IC, expected to start in 3Q27.
- With high IC utilisation rate at 72% and PCBA utilisation nearly at full capacity, management guides for aggressive capex in 2027.
- Maintain BUY with a target price of Bt56.00.
Analysis
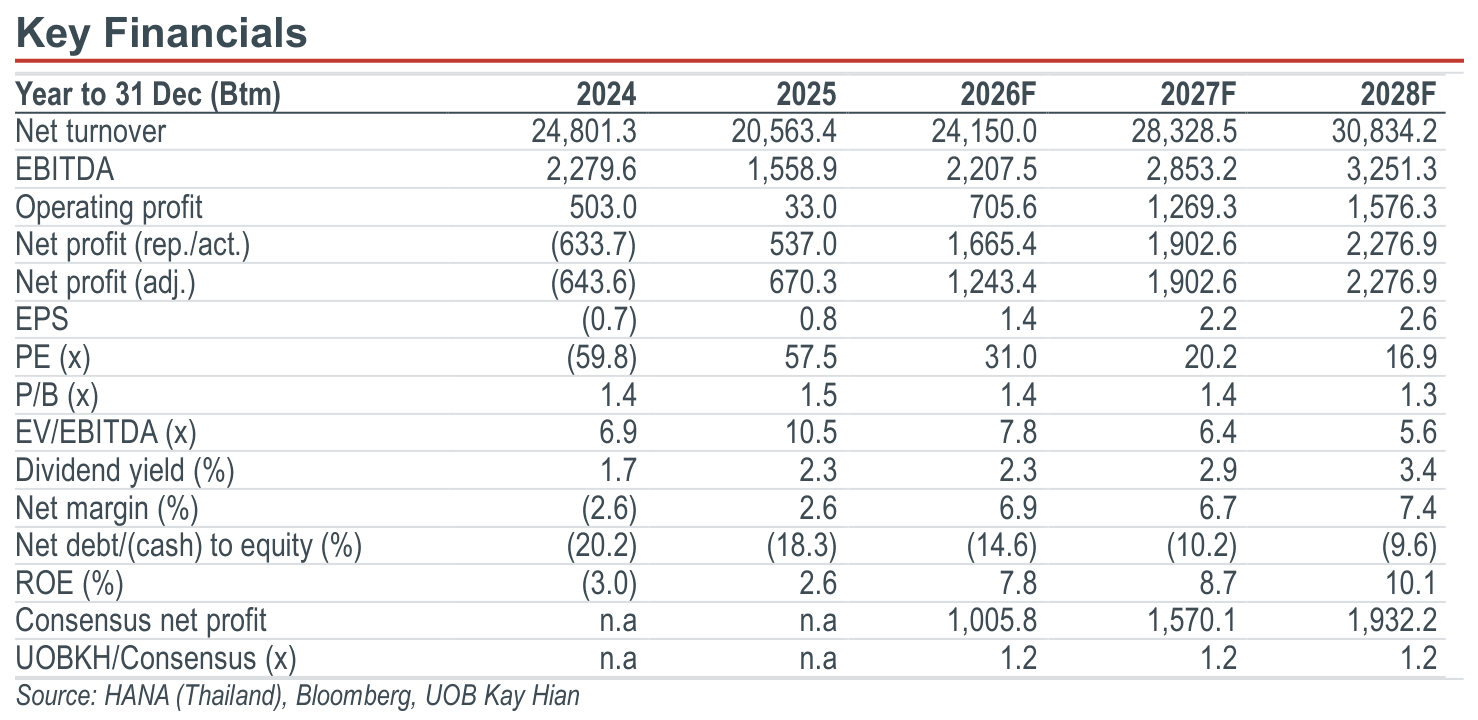
- Recap: 3Q26 earnings beat expectations, driven by strong operating margin improvement from resilient PCBA sales and IC margin recovery. On 11 Nov 26, HANA (Thailand) (HANA) reported a 3Q26 net profit of Bt693m (+4,588% yoy, +112% qoq), above our and Bloomberg consensus by 111% and 100%, respectively. The strong yoy growth came from a very low base last year due to significant losses from the Power Master business. The strong qoq earnings growth came from sales significantly beating expectations across all segments, especially PCBA (Printed Circuit Board Assembly) and IC (integrated circuit) sales. Sales came in at Bt7.3b (+38% yoy, +36% qoq), above our and Bloomberg by 26.3% and 25%, respectively. Excluding a major customer turning back from a consignment model to a turnkey model (buy-and-sell), sales were at Bt6.12b (+16% yoy, +14% qoq). We are positive on the strong recovery in core operating margin of 7.0% in 3Q26 (vs -0.3%/ 4.7% in 1Q26-2Q26, 0.2% in 3Q25). PMS (Power Master Semiconductor Co) and Microdisplay’s gross profits remain quite stable qoq at -Bt126m in 3Q26 (vs -Bt323m in 3Q25 and -Bt116m in 2Q26).
- AI-related project remains on track; AI exposure reaches 6% of sales in 3Q26 and is expected to ramp up further in 4Q26-2027. First, with two AI-related projects starting to ramp up in 3Q26, HANA’s AI exposure reached 6% of total sales, mainly driven by high-density PCBA, while solid-state cooling sales (thermoelectric coolers, or TECs, produced in partnership with Phononic) were still quite low. HANA has signed a third contract with production capacity equivalent to its first and second contracts combined. Although the solid-state cooling contribution remains small, management expects it to accelerate in 4Q26-1Q27, with the first two contracts reaching full output by end-1Q27. For the third contract, equipment is expected to arrive by end-2Q27, with production ramping up to maximum output by end-3Q27. Second, we remain positive on the IC business, as HANA has signed a substantial new contract with a customer expected to become one of the top three customers at its Ayutthaya plant by end-27. Equipment is expected to arrive in 3Q27.
Highlights
- Last week, HANA reported a 3Q26 net profit of Bt693m (+4,588% yoy, +112% qoq), beating expectation by roughly 100%.
- HANA’s AI exposure reached 6% of 3Q26 total revenue, mainly driven by high-density PCBA, while cooling sales needs time to ramp up in 4Q26-1Q27.
- HANA has signed a third contract for a solid-state cooling project with Phononics and substantial new customer for IC, expected to start in 3Q27.
- With high IC utilisation rate at 72% and PCBA utilisation nearly at full capacity, management guides for aggressive capex in 2027.
- Maintain BUY with a target price of Bt56.00.
Analysis
- Recap: 3Q26 earnings beat expectations, driven by strong operating margin improvement from resilient PCBA sales and IC margin recovery. On 11 Nov 26, HANA (Thailand) (HANA) reported a 3Q26 net profit of Bt693m (+4,588% yoy, +112% qoq), above our and Bloomberg consensus by 111% and 100%, respectively. The strong yoy growth came from a very low base last year due to significant losses from the Power Master business. The strong qoq earnings growth came from sales significantly beating expectations across all segments, especially PCBA (Printed Circuit Board Assembly) and IC (integrated circuit) sales. Sales came in at Bt7.3b (+38% yoy, +36% qoq), above our and Bloomberg by 26.3% and 25%, respectively. Excluding a major customer turning back from a consignment model to a turnkey model (buy-and-sell), sales were at Bt6.12b (+16% yoy, +14% qoq). We are positive on the strong recovery in core operating margin of 7.0% in 3Q26 (vs -0.3%/ 4.7% in 1Q26-2Q26, 0.2% in 3Q25). PMS (Power Master Semiconductor Co) and Microdisplay’s gross profits remain quite stable qoq at -Bt126m in 3Q26 (vs -Bt323m in 3Q25 and -Bt116m in 2Q26).
- AI-related project remains on track; AI exposure reaches 6% of sales in 3Q26 and is expected to ramp up further in 4Q26-2027. First, with two AI-related projects starting to ramp up in 3Q26, HANA’s AI exposure reached 6% of total sales, mainly driven by high-density PCBA, while solid-state cooling sales (thermoelectric coolers, or TECs, produced in partnership with Phononic) were still quite low. HANA has signed a third contract with production capacity equivalent to its first and second contracts combined. Although the solid-state cooling contribution remains small, management expects it to accelerate in 4Q26-1Q27, with the first two contracts reaching full output by end-1Q27. For the third contract, equipment is expected to arrive by end-2Q27, with production ramping up to maximum output by end-3Q27. Second, we remain positive on the IC business, as HANA has signed a substantial new contract with a customer expected to become one of the top three customers at its Ayutthaya plant by end-27. Equipment is expected to arrive in 3Q27.
BUY (Maintained)
Current price:
Target price:
Upside:
Bt43.50
Bt56.00
28.74%
Analyst
Analyst
Sirithat Prasertwuti
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


